


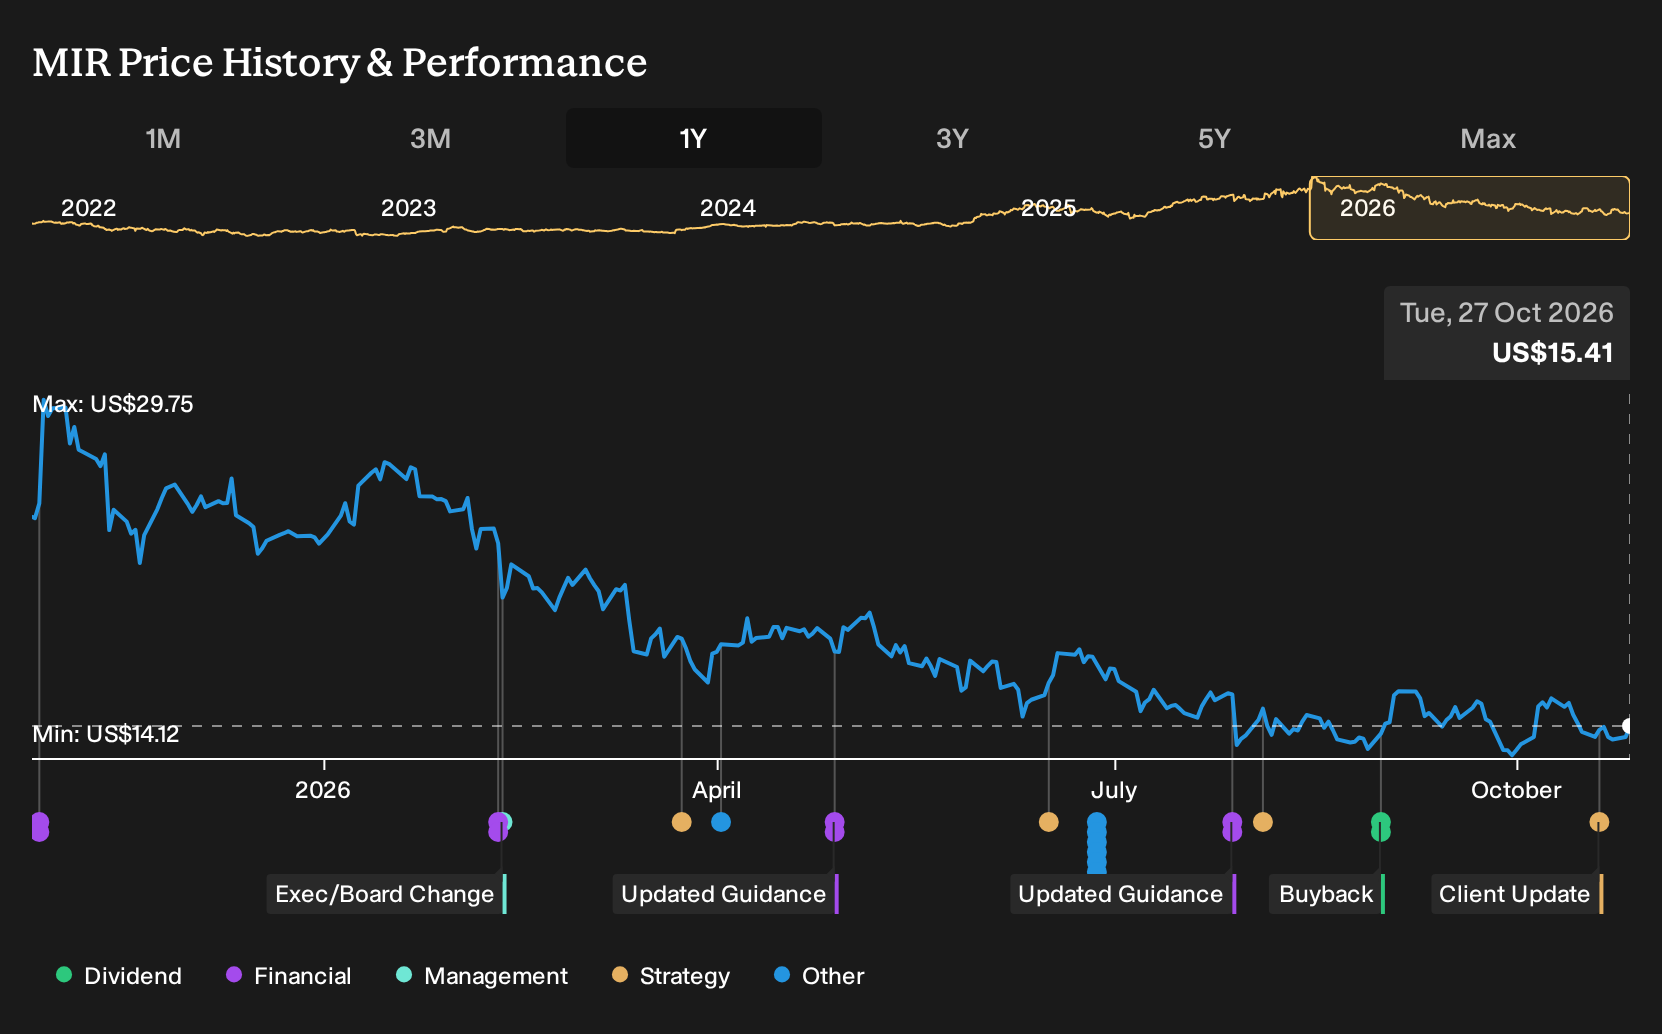
- Mirion Technologies reported Q3 2026 revenue of US$277.8 million and net income of US$7.4 million, then raised full year revenue growth guidance to about 24% to 25%.
- Management pointed to strong nuclear related orders and higher demand for reactor fleet reinvestment as key drivers of the updated outlook.
- The next focus will be how Mirion Technologies’ upgraded revenue outlook interacts with its nuclear heavy growth narrative and acquisition playbook.
Scan Mirion Technologies’ peers riding the same nuclear reinvestment theme and see which ones made the cut in our 16 nuclear energy infrastructure stocks.
Mirion Technologies Investment Narrative Recap
To own Mirion Technologies, you need to be comfortable with a business that leans heavily on nuclear reinvestment and radiation related safety demand. The latest quarter, with US$277.8 million in revenue and US$7.4 million in net income, keeps that thesis intact rather than transforming it. The upgraded 2026 revenue growth outlook to about 24% to 25% reinforces that near term execution looks solid.
The key short term swing factor now is whether strong nuclear orders actually translate into sustained organic growth as acquisitions get absorbed. The biggest operational risk still sits around concentration in nuclear, alongside debt that is not well covered by operating cash flow if order momentum or project timing softens.
The most relevant recent development is Mirion Technologies’ support for the IAEA Rays of Hope initiative, using SunCHECK Machine software and QA hardware from its medical arm. This does not move near term earnings on its own, but it does underline how Mirion is embedded in radiation therapy workflows and safety standards.
For you as an investor, that IAEA engagement matters because it ties the medical segment into long running cancer care programs and global dosimetry standards. That can reinforce recurring usage of Mirion’s software and QA tools while also exposing the business to funding and policy risk in health systems where budgets can tighten or shift toward alternative imaging technologies.
Mirion Technologies’ analyst narrative points to revenue of US$1.4b and earnings of US$213.4 million by 2029, based on 10.5% yearly revenue growth and an earnings increase of about 8.7x from US$24.5 million today.
Uncover why Mirion Technologies' fair value indicates a 61% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You also need to weigh a more cautious angle. The most bearish analysts leaned on order risk and weaker hardware demand, and were only projecting about 9.6% yearly revenue growth and roughly US$152.3 million in earnings by 2029. That is a far more restrained Mirion Technologies story, which this new guidance and Q3 update may eventually reshape.
Explore 3 other Mirion Technologies fair value estimates, including one that suggests it could be worth just $19.90!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mirion Technologies research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Mirion Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mirion Technologies' overall financial health at a glance.
Looking For More Ideas Beyond Mirion Technologies?
If Mirion Technologies is on your radar, it can help to keep a bench of other candidates ready so you are not relying on a single story.
The Simply Wall St Screener lets you filter the market quickly using fundamentals, so you can line up a short list that fits your own risk, quality, and income preferences.
- For investors hunting for income strength, scan companies with resilient payouts and balance sheets using our 5 dividend fortresses.
- If capital preservation is front of mind, narrow the field to businesses with sturdier financial profiles through the 30 resilient stocks with low risk scores.
- When you want potential upside backed by fundamentals, sort for under followed quality using the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com