


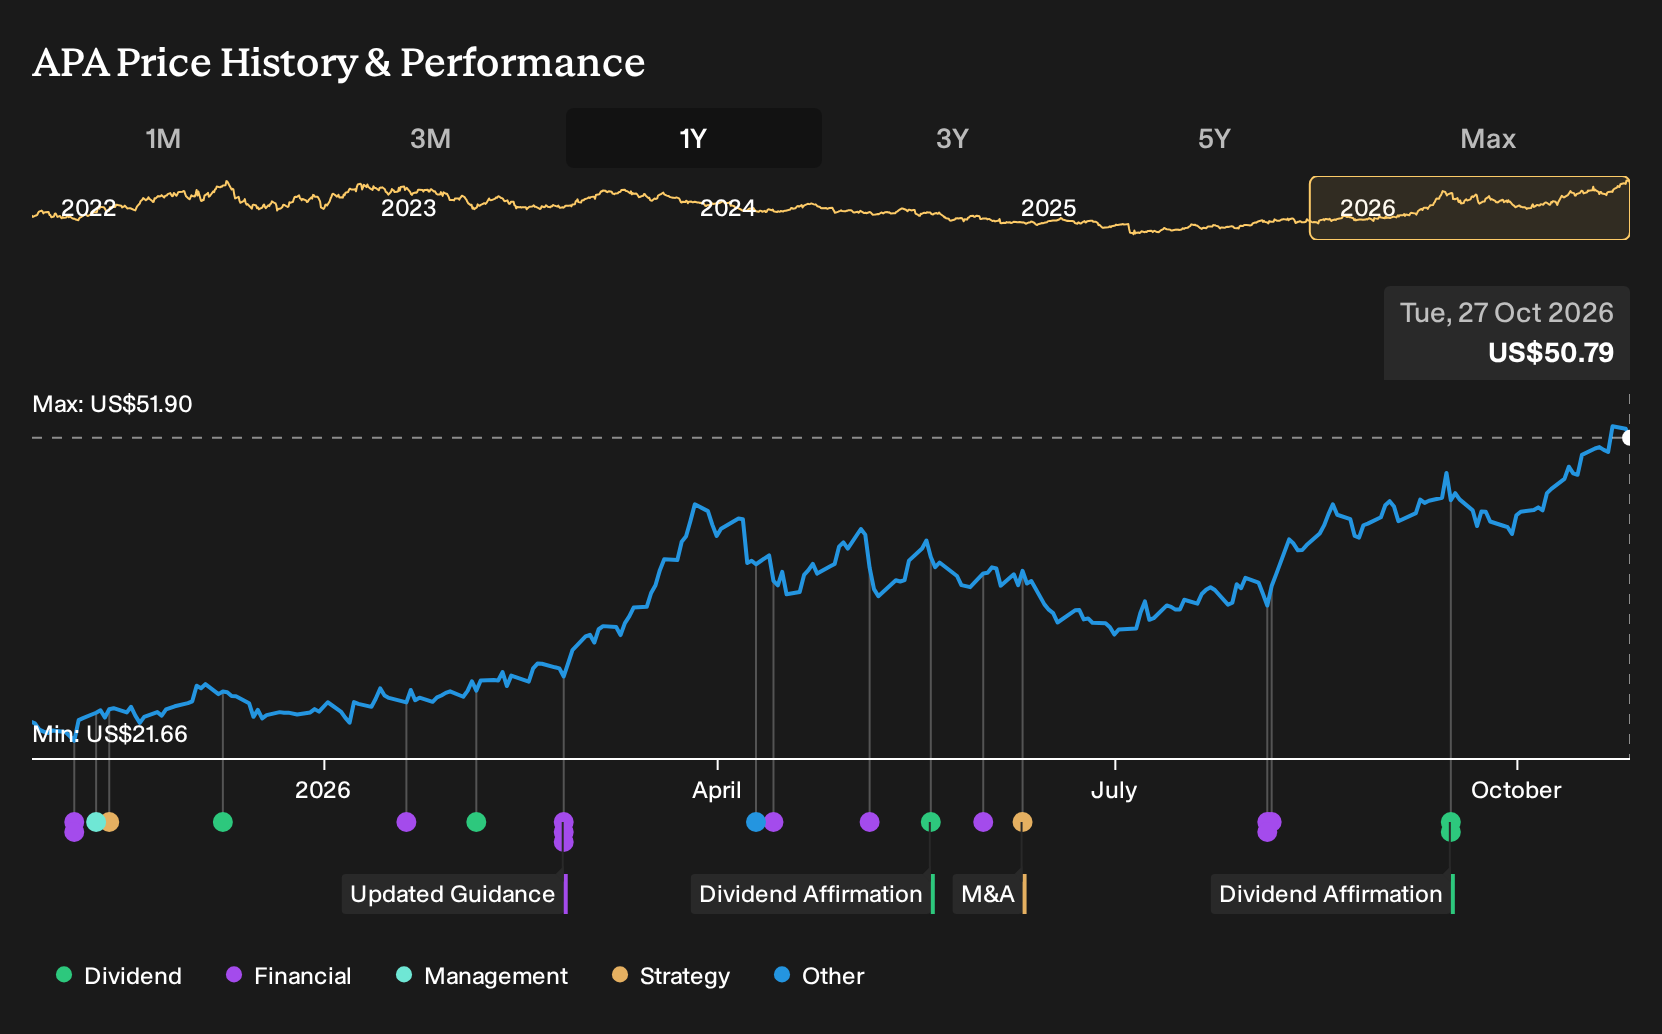
- APA is preparing to report quarterly results for the period ended September 2026, with analysts expecting higher earnings alongside stronger revenue.
- The focus now is on how APA's cost structure and asset mix, including gas weighted output and Suriname projects, align with these forecasts.
- We will now assess how APA's investment narrative could be influenced by the upcoming earnings release and the expected year over year earnings gains.
Scan beyond APA and line up other potential earnings movers with the 29 high quality undervalued stocks that analysts are watching closely this season.
APA Investment Narrative Recap
To own APA today, you need to be comfortable with a gas weighted portfolio that leans on Egypt, the Permian and future Suriname volumes, while carrying a meaningful debt load and exposure to carbon and policy risk. The near term story hinges on keeping operating costs in check and protecting cash generation even if commodity prices stay choppy.
The upcoming November 4 earnings release is the clearest short term catalyst, because it will show whether recent cost savings and asset mix are translating into steadier margins. The biggest risk right now remains concentration in Egypt and gas markets, where pricing or regulatory shocks could quickly offset efficiency gains.
The most relevant update tied to this earnings season is APA’s push toward about US$500 million of annualized run rate savings by the end of 2026 while holding a lower rig count and aiming to sustain oil production. Your focus into the print is whether operating costs and capital spending trends line up with that ambition.
Those planned savings sit alongside other moving parts, including Suriname GranMorgu progressing toward mid 2028 first oil and roughly US$500 million a year of gas focused capital in Egypt. Taken together, these projects and efficiency targets frame the next few years of catalysts and also sharpen execution risk if schedules, budgets or gas pricing slip.
APA's narrative projects US$7.9 billion of revenue and US$1.5 billion of earnings by 2029, based on analyst estimates that assume revenue declines at 2.6% per year and profit margins stay near 19.6%. This implies earnings today of about US$1.7 billion, with a decrease of roughly US$200 million needed to reach the current consensus forecast.
Uncover how APA's fair value indicates a 7% potential downside to its current price, suggesting a valuation premium that leaves little room for error.
Exploring Other Perspectives
For APA, the alternate story leans hard on gas price risk rather than cost savings. The most cautious analysts had pencilled in revenue of about US$7.2b and earnings near US$690.3 million by 2029, far below consensus. That gap shows just how far opinions can stretch and why this earnings report may reshape some of those views.
Explore 4 other APA fair value estimates, including one that suggests as much as 27% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your APA research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for APA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate APA's overall financial health at a glance.
Looking for more investment ideas beyond APA?
Once you have a view on APA, it can help to line it up against other opportunities on the Simply Wall St Screener so you can see where the risk and reward trade off feels most comfortable for you.
- For investors who want potential upside without ignoring balance sheet strength, scan the 21 high quality undiscovered gems that combine quality fundamentals with room for the story to develop.
- If capital preservation and steadier profiles matter most to you, filter for 30 resilient stocks with low risk scores that may better match a lower volatility approach.
- Income focused readers can zero in on 5 dividend fortresses to see which companies pair higher yields with more robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com