


PepsiCo has faced a mixed share price story over the past few years, and the question now is how well the current US$133.50 quote lines up with the earnings behind it. With recent news ranging from renewed partnerships to cost cutting and guidance resets, the stock invites a closer look at what investors are really paying for its profit stream.
- Over the last 3 years, PepsiCo shares have slipped about 8.9%, which puts more focus on whether the current valuation is properly anchored to the business it earns from today.
- The renewal of the long term Taco Bell beverage agreement, alongside plant closures and a lower medium term earnings growth outlook, can reshape expectations for PepsiCo's future margins and cash generation profile.
- Your read on PepsiCo is one view; the desks covering it have another. See what analysts think PepsiCo's shares could be worth.
The stock's next move may depend on whether PepsiCo's present earnings are strong enough to justify the price investors are being asked to pay today.
If you are weighing PepsiCo's recent KFC loss, Taco Bell renewal, and earnings reset, it can help to compare this setup with companies screened for our screener containing 21 high quality undiscovered gems.
Does PepsiCo Look Undervalued on Earnings?
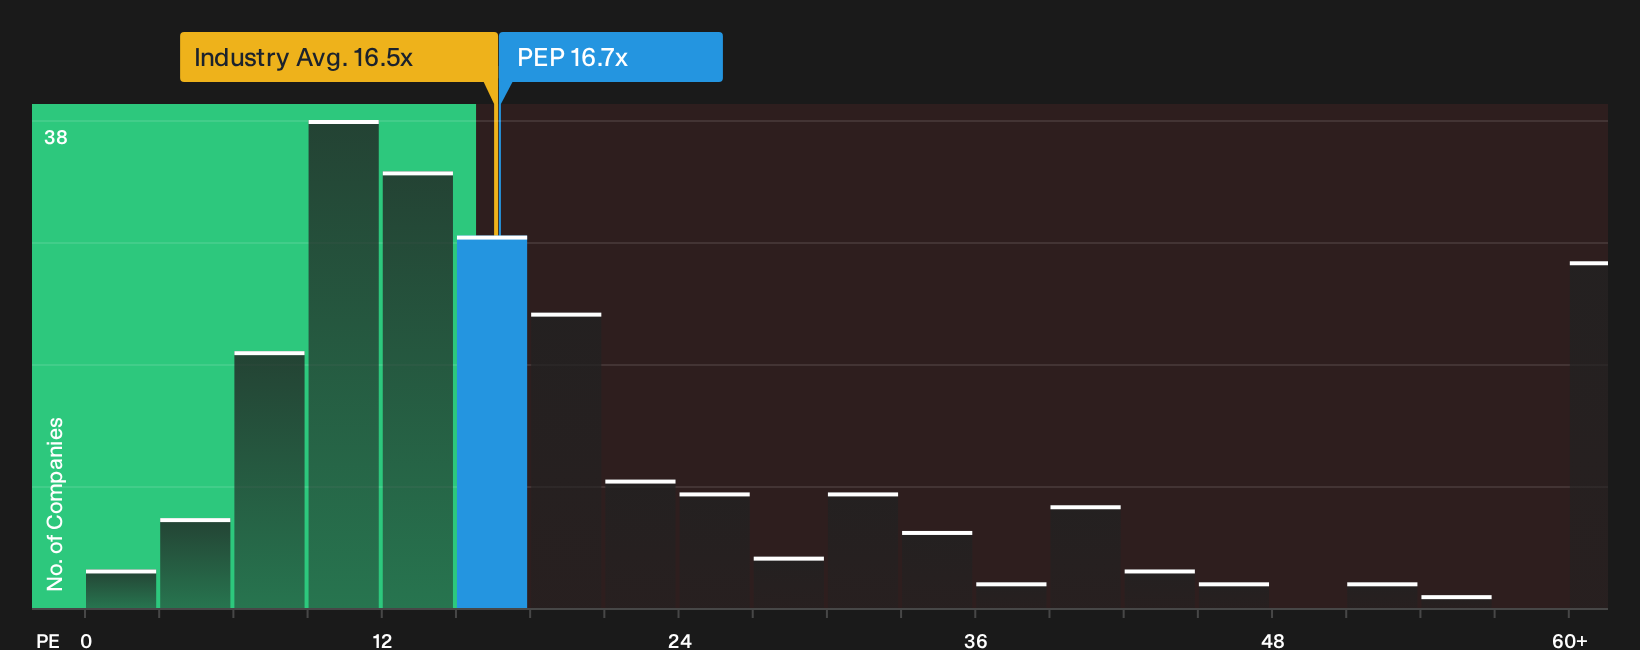
The P/E ratio suits PepsiCo because earnings remain the key lens investors use for mature consumer brands with steady profit streams. On that measure, PepsiCo trades at about 16.7x earnings, which is very close to the Beverage industry average of 16.5x. The stock also changes hands at a lower multiple than the wider peer set, which screens at roughly 30.6x.
Because the fair P/E for PepsiCo, based on its own growth profile, margins, size and risks, screens higher than the current level, the shares come through as undervalued on this earnings yardstick. Despite the renewed Taco Bell partnership helping sentiment around the long term beverage pipeline, the P/E still prices PepsiCo below what this framework suggests for the business. Explore the numbers behind PepsiCo's P/E valuation.
The PepsiCo Narrative: What Would Justify Today's Price?
Narratives pick up where PepsiCo's valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the shares to look meaningfully cheaper or richer than today. Each scenario links a fair value estimate to a clear storyline about possible catalysts and risks, so you can track over time which version of PepsiCo's future is actually unfolding.
PepsiCo attracts two very different readings, with some investors seeing cost and international progress as underappreciated while others focus on flat demand and portfolio risk.
Bull case: 6% undervalued
"Execution of the One North America integration, including combined mixing centers, shared warehousing and transportation, and potential refranchising, is intended to structurally lower logistics and operating costs…"
Discover why this Narrative puts PepsiCo at 6% undervalued.
Bear case: 15% overvalued
"Given both tailwinds (popularity of functional drinks) and headwinds (health conscious consumers), overall revenue is expected to remain broadly flat…"
Explore why this Narrative puts PepsiCo at 15% overvalued.
One more check for PepsiCo beyond the share price
Numbers only tell part of the story, since the people setting PepsiCo's priorities and how they are rewarded can strongly influence how those figures evolve over time. See who runs PepsiCo and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com