


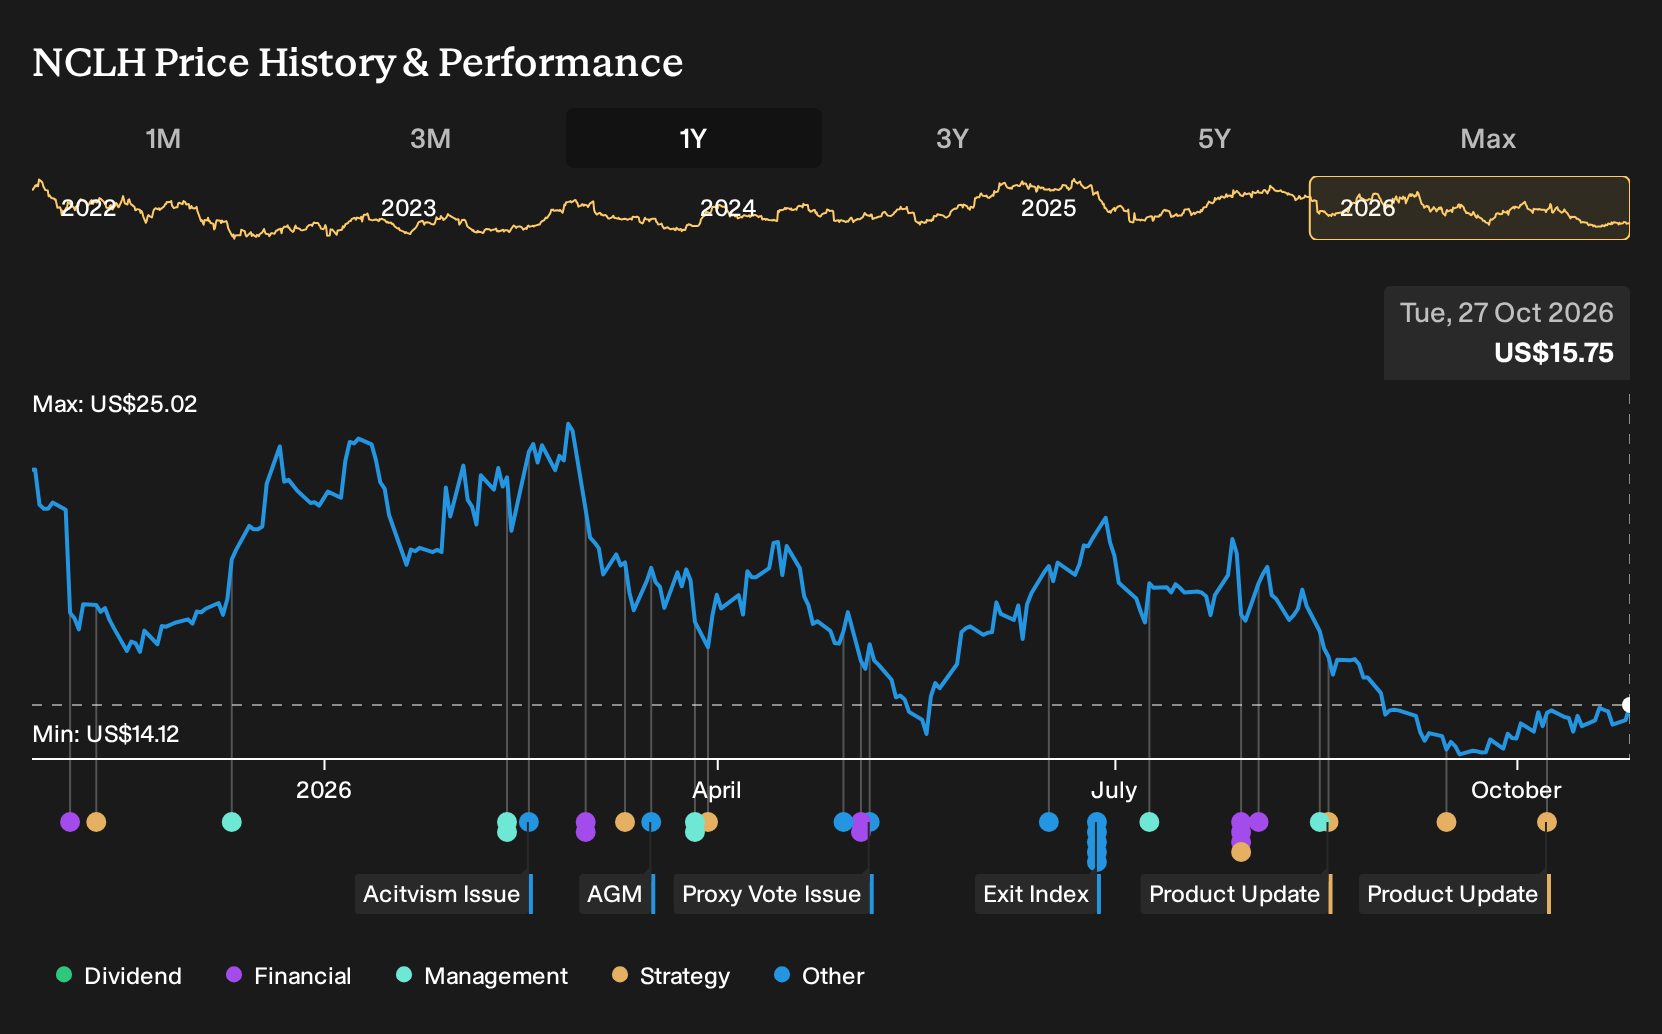
- Norwegian Cruise Line Holdings is due to report third quarter 2026 results, with analysts expecting earnings per share around $0.91 to $0.92 on revenue near $2.87b, both lower than the prior year alongside softer net yields and weaker booking trends in key European itineraries.
- An additional consideration is that, despite these operational pressures and recently reduced forecasts, earnings models still point to a possible upside surprise relative to consensus, helped by Norwegian Cruise Line Holdings' recent record of outpacing analyst EPS estimates in three of the last four quarters.
- The following section examines how Norwegian Cruise Line Holdings' investment narrative could shift as investors weigh weaker yields against a possible earnings beat.
Scan beyond Norwegian Cruise Line Holdings and compare its setup with a curated group of travel and leisure stocks that currently screen as 29 high quality undervalued stocks
Norwegian Cruise Line Holdings Investment Narrative Recap
To own Norwegian Cruise Line Holdings, you need to believe the commercial reset can offset current pressure on yields and occupancy. The immediate swing factor is whether weaker European demand and softer net yields stabilize as the new revenue management system and marketing approach filter through. The upcoming quarter looks like a checkpoint rather than a turning point.
The biggest near term risk is that yield pressure and a softer booking curve linger while leverage stays high and interest expense absorbs much of the operating profit. If that happens, cost savings, private island upgrades and premium brand strength matter less, because less cash is left to reduce debt.
The current Q3 setup, with expected earnings per share around US$0.91 to US$0.92 and revenue near US$2.87b, directly ties into this debate. Estimates already reflect weaker net yields, lower occupancy and softer booking trends. The short term catalyst is simple: investors want to see if operational changes show up in ticket pricing, onboard spend and booking curves despite that pressure.
Norwegian Cruise Line Holdings has outpaced earnings expectations in three of the last four quarters, which keeps the door open for another beat. Yet even a stronger print would not remove the structural issues around leverage, refinancing needs and yield recovery. It would just buy more time for the cost program, fleet renewal and commercial overhaul to do their job.
Norwegian Cruise Line Holdings Through the 2029 Lens
Norwegian Cruise Line Holdings' analyst playbook hinges on modest expansion rather than a quick fix. Consensus models build in annual revenue growth of 4.5% over the next three years while keeping profit margins flat at 7.5%. This effectively indicates that the extra dollars of sales are not assumed to come with richer profitability for now.
Forecasts today point to earnings rising from US$760.8 million to US$868.6 million by 2029. That is an earnings increase of roughly US$108 million, a move that looks incremental rather than transformational when set against the leverage and refinancing tasks already flagged for the business.
Valuation work in those same models leans heavily on what investors are willing to pay for those future profits. The consensus framework assumes Norwegian Cruise Line Holdings trades on a P/E of 15.0x in 2029 compared with 9.3x today. This multiple still sits below the quoted 19.7x level for the broader US Hospitality group in the report, but it would still require a higher pricing of the earnings stream than the stock currently receives.
Norwegian Cruise Line Holdings' narrative projects US$11.6b revenue and US$868.6 million earnings by 2029. This requires 4.5% yearly revenue growth and an earnings increase of roughly US$108 million from US$760.8 million today.
Uncover why Norwegian Cruise Line Holdings' fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Norwegian Cruise Line Holdings leans heavily on margin pressure. The most cautious analysts were expecting 3.6% annual revenue growth and earnings of about US$527.3 million by 2029, which is far below the US$868.6 million consensus path. That gap shows how far opinions can spread and why this Q3 report could reset both stories.
Explore 4 other Norwegian Cruise Line Holdings fair value estimates, including one that suggests as much as 76% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Norwegian Cruise Line Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Norwegian Cruise Line Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Norwegian Cruise Line Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Norwegian Cruise Line Holdings?
If Norwegian Cruise Line Holdings has sharpened your focus on risk, reward and timing, it can be useful to line it up against other opportunities with very different profiles. The Simply Wall St Screener helps you do that quickly by narrowing the market to a handful of focused sets you can research in more detail.
- If capital preservation and steadier price behavior matter most to you right now, consider starting with a group of stocks screened as 30 resilient stocks with low risk scores
- If you are hunting for quality at a discount and want to compare Norwegian Cruise Line Holdings against companies with stronger cash generation and pricing, check out a curated group flagged as 29 high quality undervalued stocks
- If you prefer resilient balance sheets and want to stress test your portfolio against financial shocks, review a focused list of solid balance sheet and fundamentals (24 results)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com