


Kennametal has delivered a strong share price recovery in recent years, which naturally raises the question of whether the current US$29.87 level is well supported by the cash the business can generate. With the focus squarely on its cash flows, the valuation story now matters as much as the share chart.
- The stock has returned about 41.7% over the past 3 years, putting real weight on whether that climb is backed by the company’s underlying cash flow profile.
- Fresh expectations for higher future sales alongside the drive to secure tungsten supply can influence how reliably Kennametal may turn those revenues into cash and when that cash shows up.
- If you'd rather focus on earnings, this one's for you. See what Kennametal's 6.6x P/E says about the price.
The stock's next move may depend on whether those recent share price gains line up with what a Discounted Cash Flow (DCF) view of Kennametal’s cash generation suggests is a justified level.
If you want a wider watchlist alongside Kennametal while still focusing on cash generation and balance sheet strength, a focused stock screen built around solid balance sheet and fundamentals stocks screener (24 results) can be a useful next step.
Is Kennametal a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here is built around the cash Kennametal can return to shareholders over time. Latest twelve month free cash flow was a loss of $105.16 million, so the whole exercise rests on a recovery story rather than steady state assumptions. The projections used in the model point to future free cash flow in the hundreds of millions of dollars each year, then easing back toward a more mature run rate instead of climbing in a straight line.
That pattern means the gap between depressed recent cash generation and the model’s healthier outer year numbers does a lot of the work in explaining why the DCF output sits meaningfully above the current US$29.87 share price. Because the tungsten sourcing deadline from January 2027 adds supply risk around a key input, the difference between the current share price and the model’s output can be viewed in light of that risk even as the model implies stronger long term cash flow. Find out what Kennametal could be worth using our Discounted Cash Flow (DCF) estimate.
The Kennametal Narrative: What Would Justify Today's Price?
Narratives pick up where Kennametal's DCF puzzle leaves off and spell out which paths for future growth, profitability and earnings would need to hold for the shares to look meaningfully higher or lower than today's price, all hosted on Simply Wall St's Community page.
Each scenario anchors its number to a specific view on how Kennametal's expansion, margins and key risks could evolve, giving you something concrete to revisit as fresh results and news update the picture.
One of the top community narratives on Kennametal: 8% undervalued
"The main priority is that Kennametal continues to turn its aerospace and defense focus, tungsten integration and restructuring into durable margin support..."
Discover why this Narrative puts Kennametal at 8% undervalued.
The Kennametal story has one more question investors usually check
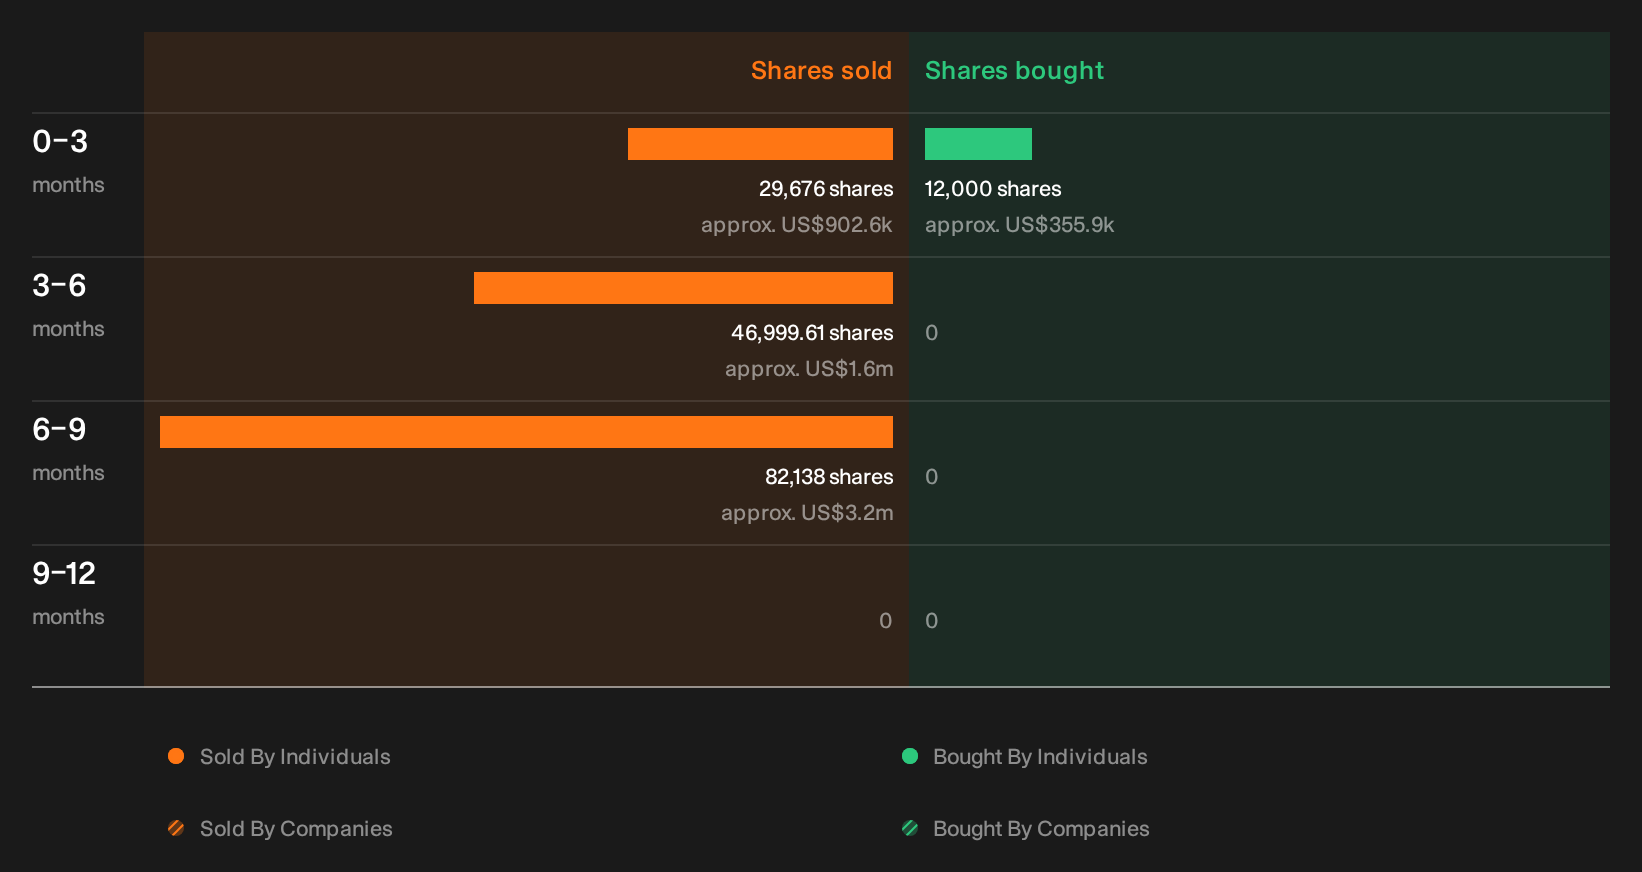
Valuation work only goes so far without knowing what the people running Kennametal are doing with their own holdings, and recent insider share sales flagged by our checks leave the sellers, sizes and possible interpretations for you to review. See the recent insider selling flagged for Kennametal.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com