


Samsung Electronics has logged a powerful share price run in recent years, which puts a spotlight on a simple question for anyone looking at the stock today. Is the current price being carried more by enthusiasm around its earnings story or by the earnings themselves?
- Over the past 5 years the stock has returned about 278.7%, which puts a lot of weight on whether the current earnings base and its trajectory can support that kind of re-rating.
- Recent focus on Samsung's memory and storage products for AI inference, including higher performance solutions for data heavy workloads, can shape expectations for how quickly earnings might grow and how resilient future cash generation could be.
- The analysts covering Samsung Electronics have run their own numbers. See what analysts think Samsung Electronics's shares could be worth.
The issue now is whether Samsung Electronics' share price around ₩242,000 is justified by the earnings investors are paying for today.
If you are weighing whether Samsung Electronics' earnings justify this price, it can help to benchmark that question across 55 AI infrastructure stocks.
Is Samsung Electronics Still Cheap on Earnings?
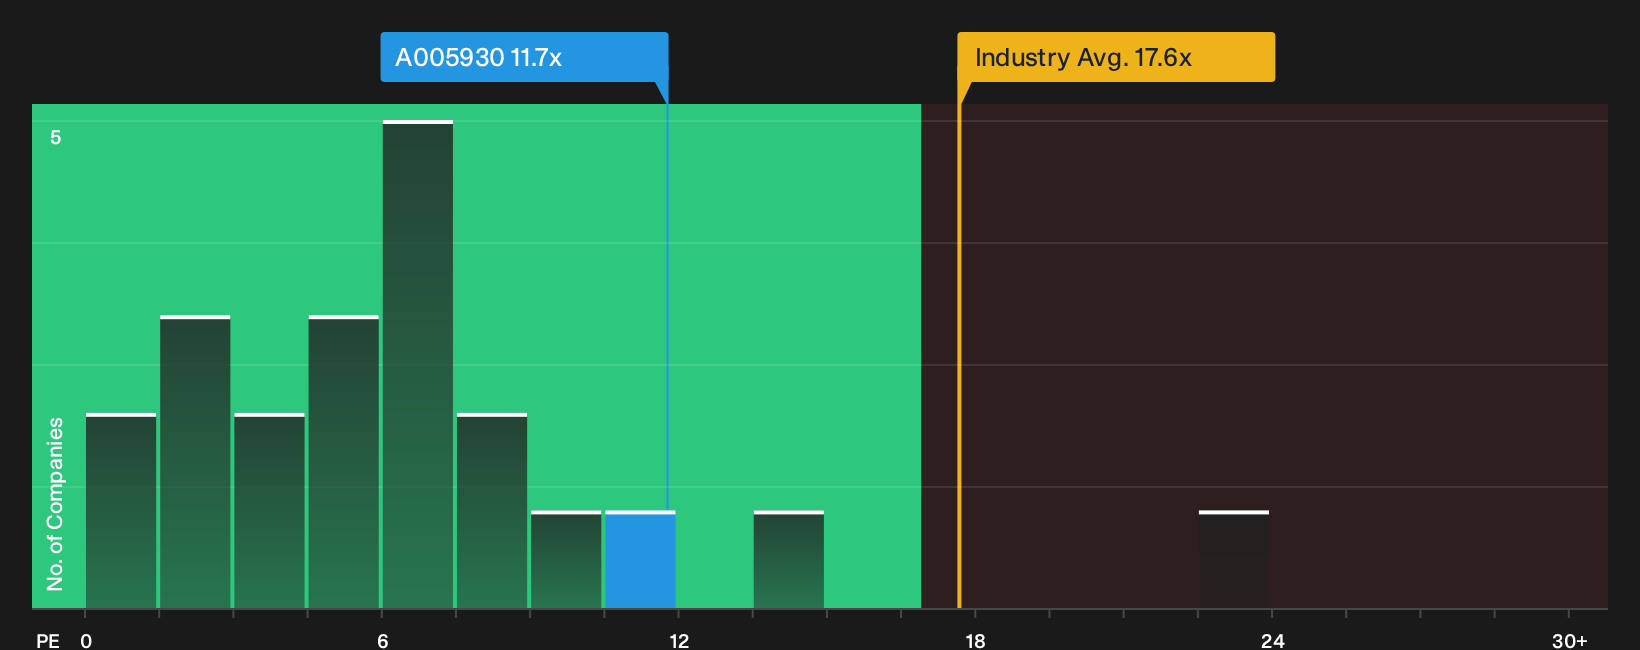
The P/E ratio fits Samsung Electronics because earnings remain the main anchor for how investors look at large chip manufacturers. On this yardstick, the stock trades on about 11.8x earnings, compared with roughly 18.9x for the broader Tech sector and a much richer 53.8x across closer peers. That gap suggests investors are paying a lower price for each unit of Samsung Electronics' profit than for many comparable technology stocks.
The Fair Ratio model, which blends information on growth, profitability, size and risk, points to a higher multiple than the market is currently assigning. As a result, the shares screen undervalued against that tailored yardstick. Because recent headlines around potential threats to global AI infrastructure have unsettled Korean chipmakers, the current discount hints that investors are still pricing in extra risk even as the P/E implies a lower bar for Samsung Electronics' earnings power. Explore the numbers behind Samsung Electronics's P/E valuation.
The Samsung Electronics Narrative: What Would Justify Today's Price?
Narratives for Samsung Electronics pick up where this valuation gap leaves off and spell out which combinations of future growth, profitability and earnings paths would need to hold for the shares to trade meaningfully above or below today's level. Each scenario links its implied number to a clear view on how Samsung Electronics' revenue expansion, margin profile and risk picture could shift next, providing a reference point you can revisit as fresh information becomes available.
Community views on Samsung Electronics split between one group that sees a discounted AI memory leader and another that thinks most of the story is already priced in.
Bull case: 46% undervalued
"Samsung's competitors like TSMC, SKHY, MU, and INTC are not capable of what Samsung can..."
Discover why this Narrative puts Samsung Electronics at 46% undervalued.
Bear case: 16% overvalued
"Memory chips are largely a commodity, so performance depends heavily on how well supply matches demand..."
Explore why this Narrative puts Samsung Electronics at 16% overvalued.
Samsung Electronics’ valuation still leaves one crucial piece offstage
Price and earnings only tell you so much about Samsung Electronics, because the people deciding where to invest cash and how they are rewarded for those choices can push the story in very different directions. See who runs Samsung Electronics and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com