


Teck Resources (TSX:TECK.B) is back in focus after more than 1,200 unionized workers began strike action at its Highland Valley Copper operations in British Columbia, leaving the site operating at reduced capacity.
The labour action has landed just as Teck Resources’ share price has been on a strong run, with a 32.43% year-to-date share price return and a 46.13% total shareholder return over the past 12 months, signalling solid momentum despite a 6.48% share price decline over the past 30 days.
Scan how other materials producers are handling labour, cost, and production risks by reviewing our curated list of solid balance sheet and fundamentals (7 results) alongside Teck Resources’ current situation.
Teck Resources has climbed hard over the past year, yet the current CA$87.39 price still trails both analyst targets and intrinsic estimates. Is that gap meaningful value, or just risk not fully priced in?
Most Popular Narrative: 4.8% Undervalued
On the most followed view, Teck Resources screens modestly below an implied fair value of CA$91.82, compared with the last close at CA$87.39. That gap rests on very specific copper projects and the proposed Anglo American merger rather than broad sector optimism.
The Highland Valley Copper Mine Life Extension project is now largely engineered, with most procurement awarded and significant 2026 capital allocated. This supports a long production profile that can underpin revenue visibility and earnings from copper for Teck Resources.
See why 34 investors see Teck Resources as 5% undervalued.
Result: Fair Value of CA$91.82 (UNDERVALUED)
Still, heavy 2026 capex, alongside any delays at Highland Valley or Quebrada Blanca, could squeeze free cash flow and challenge the current Teck Resources narrative.
Find out about the key risks to this Teck Resources narrative.
Another View On Teck Resources: Earnings Quality Versus Pricing Risk
The earlier fair value work paints Teck Resources as about 3.3% below intrinsic value, with CA$87.39 against an estimated CA$90.34, which points to slight undervaluation. The earnings based lens tells a different story on what investors are paying for each dollar of profit.
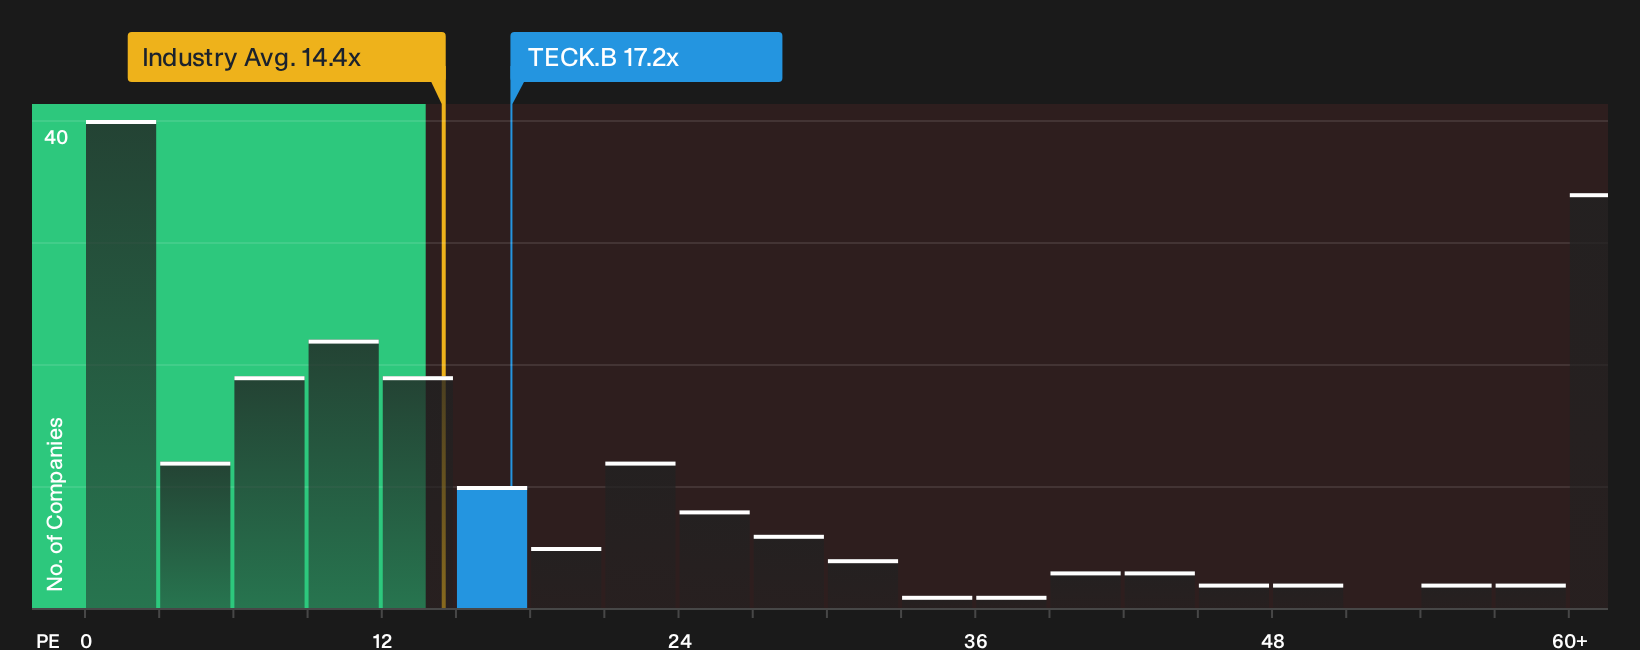
On a P/E of 17.2x, Teck Resources trades above the Canadian Metals and Mining industry at 14.2x and above its own fair ratio of 13.9x. That means the market is already paying a premium multiple, even though earnings are forecast to decline by 3.8% a year and revenue is expected to fall 0.9% annually. How comfortable are you with paying up for high quality past earnings in a business where forward growth expectations are soft?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Teck Resources so far, with premium pricing on earnings and fresh labour trouble on the ground. If you want to move fast and judge the balance of concerns against potential upside for yourself, start by weighing the 2 key rewards and 1 important warning sign.
Ready for more ideas beyond Teck Resources?
If Teck Resources has your attention, do not stop here. Broader opportunities often appear where pricing, quality, and risk come together in unexpected ways.
- Target quality at a discount by scanning our market wide list of 3 high quality undervalued stocks before prices shift away from you.
- Secure potential income streams by focusing on companies in the 3 dividend fortresses that pair yield with underlying business strength.
- Prioritise resilience by filtering for businesses on the 8 resilient stocks with low risk scores so downside risk does not blindside your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com