


Arm Holdings (ARM) will release its fiscal 2027 second-quarter earnings on Nov. 4. While profit booking following a significant rally has led to a correction in its stock price, its solid Q2 performance and strong Arm AGI CPU demand could spur a recovery.
Arm continues to see strong customer demand across its business, which indicates solid growth ahead. Moreover, it has signed multiple high-value agreements that will support long-term growth.
Arm's Q2 Outlook
Arm entered fiscal 2027 on a strong footing, led by solid momentum across its business. Strong demand for ARM-based computing architectures across cloud infrastructure, consumer electronics, automotive systems, and emerging AI applications positions it well to deliver solid growth in Q2 and beyond.
Arm reported first-quarter revenue of $1.29 billion, up 22% year-over-year (YoY). The top line benefited from solid performance in the royalty business. Its royalty revenue increased 22% YoY to $715 million, with cloud AI and data center infrastructure emerging as the primary growth engines. Data center royalty revenue more than doubled from the previous year, supported by the expanding adoption of ARM-based server processors among major hyperscalers.
In addition, the growing deployment of data processing units (DPUs) and SmartNICs is providing another growth source, as Arm technology is incorporated into a broad range of leading data center networking products.
In the consumer segment, Edge AI royalties continued to expand despite weakness in the smartphone market. Higher royalty rates, driven by growing adoption of Armv9 architectures and compute subsystems, helped offset softer smartphone sales and the pressure from elevated memory prices. Physical AI also contributed positively, with continued adoption of ARM-based technologies in advanced driver-assistance systems (ADAS) and autonomous applications supporting demand across the automotive ecosystem.
Licensing revenue is another key growth driver. License and other revenue reached $574 million, up 23% YoY, reflecting strong customer demand for next-generation architectures and deeper strategic relationships with major technology companies. Arm also secured multiple high-value agreements as existing customers renewed long-term licenses. These arrangements, involving hyperscalers, automotive and robotics companies, and handset manufacturers, strengthen Arm's competitive position.
Demand for Arm's AGI CPU offering is also gaining traction, with reported demand exceeding $2 billion. The addition of customers across the U.S. and China, alongside an expanding overall pipeline, points to strong growth ahead.
Looking ahead, management expects the growth trajectory to remain strong in the second quarter of fiscal 2027. Arm forecasts revenue of $1.38 billion, representing approximately 22% YoY growth. Licensing and other revenue are projected to rise about 30%, while royalty revenue is expected to grow at a low-teens rate.
The earnings outlook is also solid, with management projecting adjusted earnings per share (EPS) of $0.47 for Q2, up 21% YoY.
Why ARM Stock Appears Compelling Ahead of Q2
Arm’s upcoming Q2 earnings could be a key catalyst for a stock-price recovery, supported by strong customer demand, expanding data center adoption, and growing traction for its AGI CPU offering.
Arm is expected to deliver solid revenue and earnings growth, driven by strength in royalty revenue. Higher licensing revenue and long-term agreements with major technology companies also highlight its solid growth prospects. Moreover, rising adoption of ARM-based architectures across AI infrastructure, automotive systems, and consumer electronics provides multiple avenues for sustained growth.
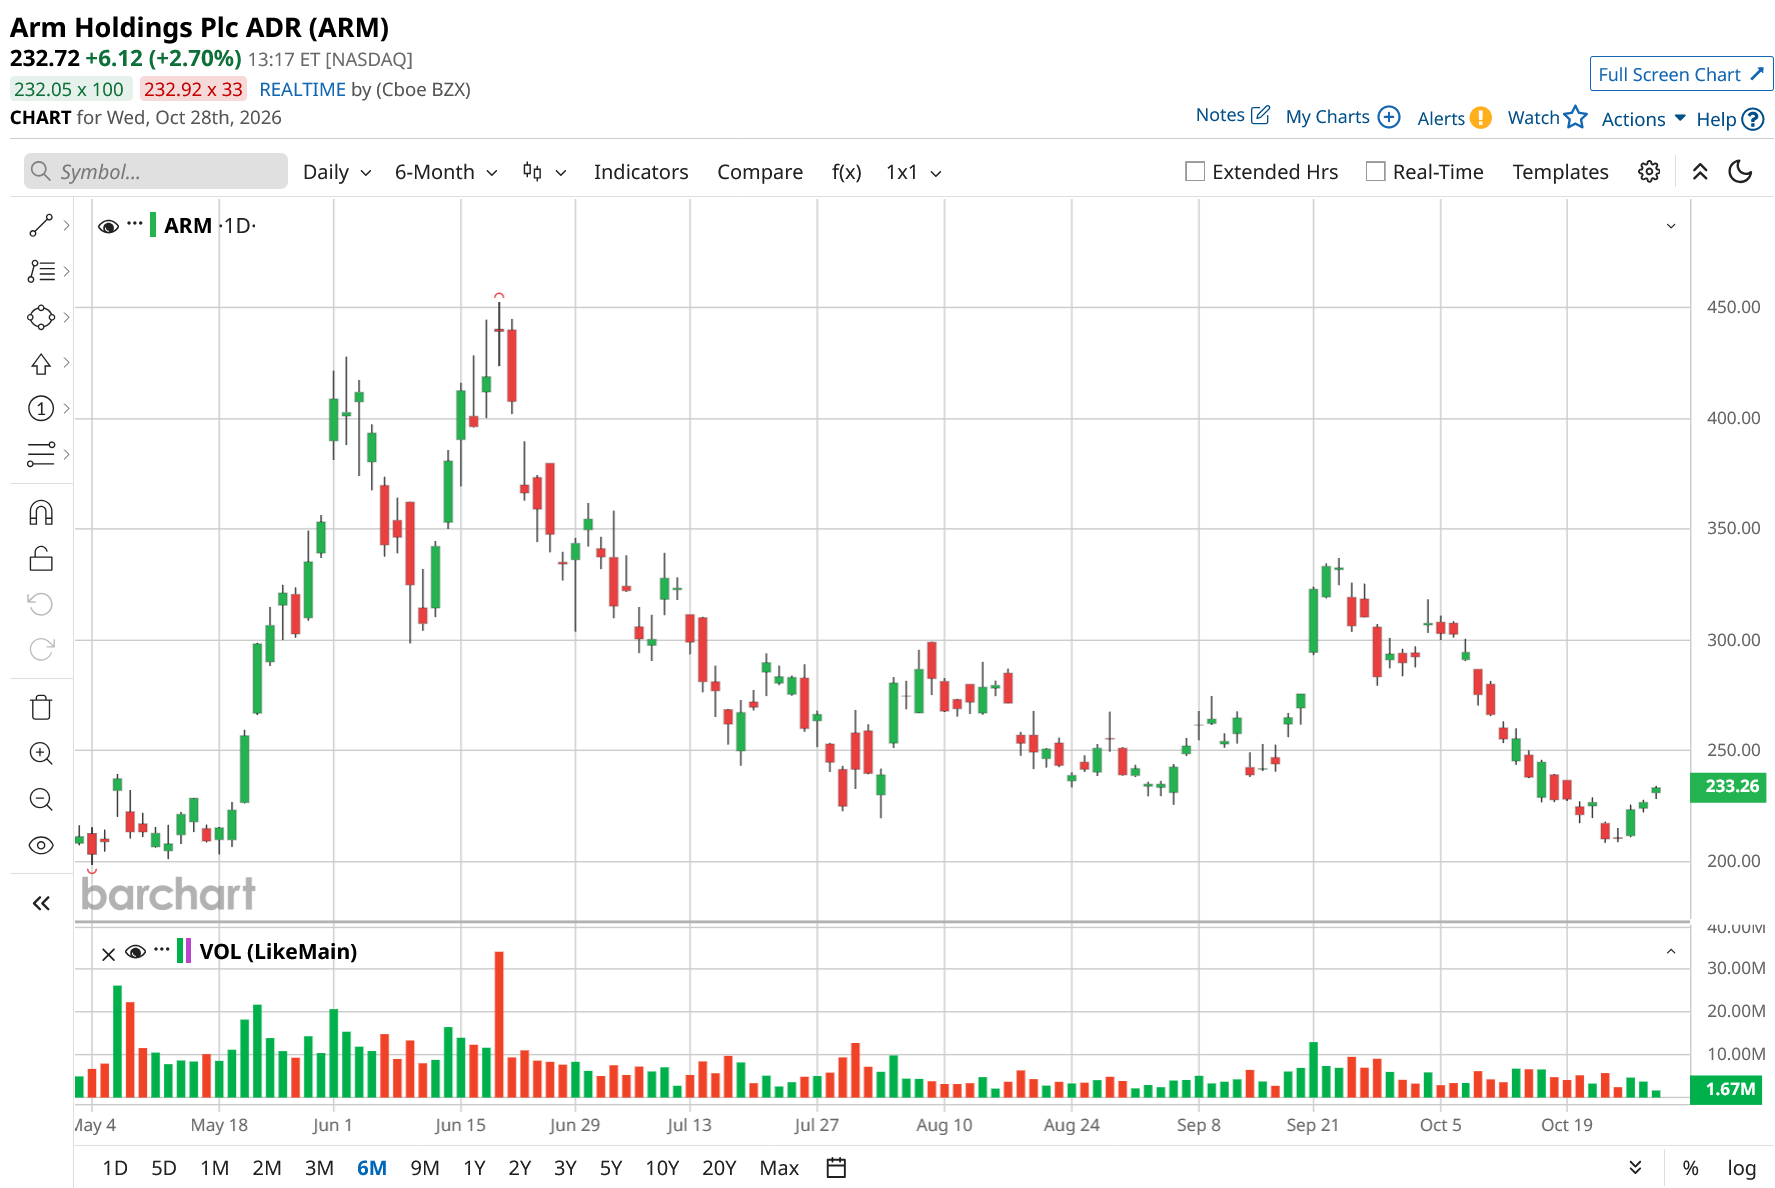
Although ARM stock still trades at a high valuation, the 49% decline from its 52-week high has eased some of these concerns ahead of the earnings announcement.
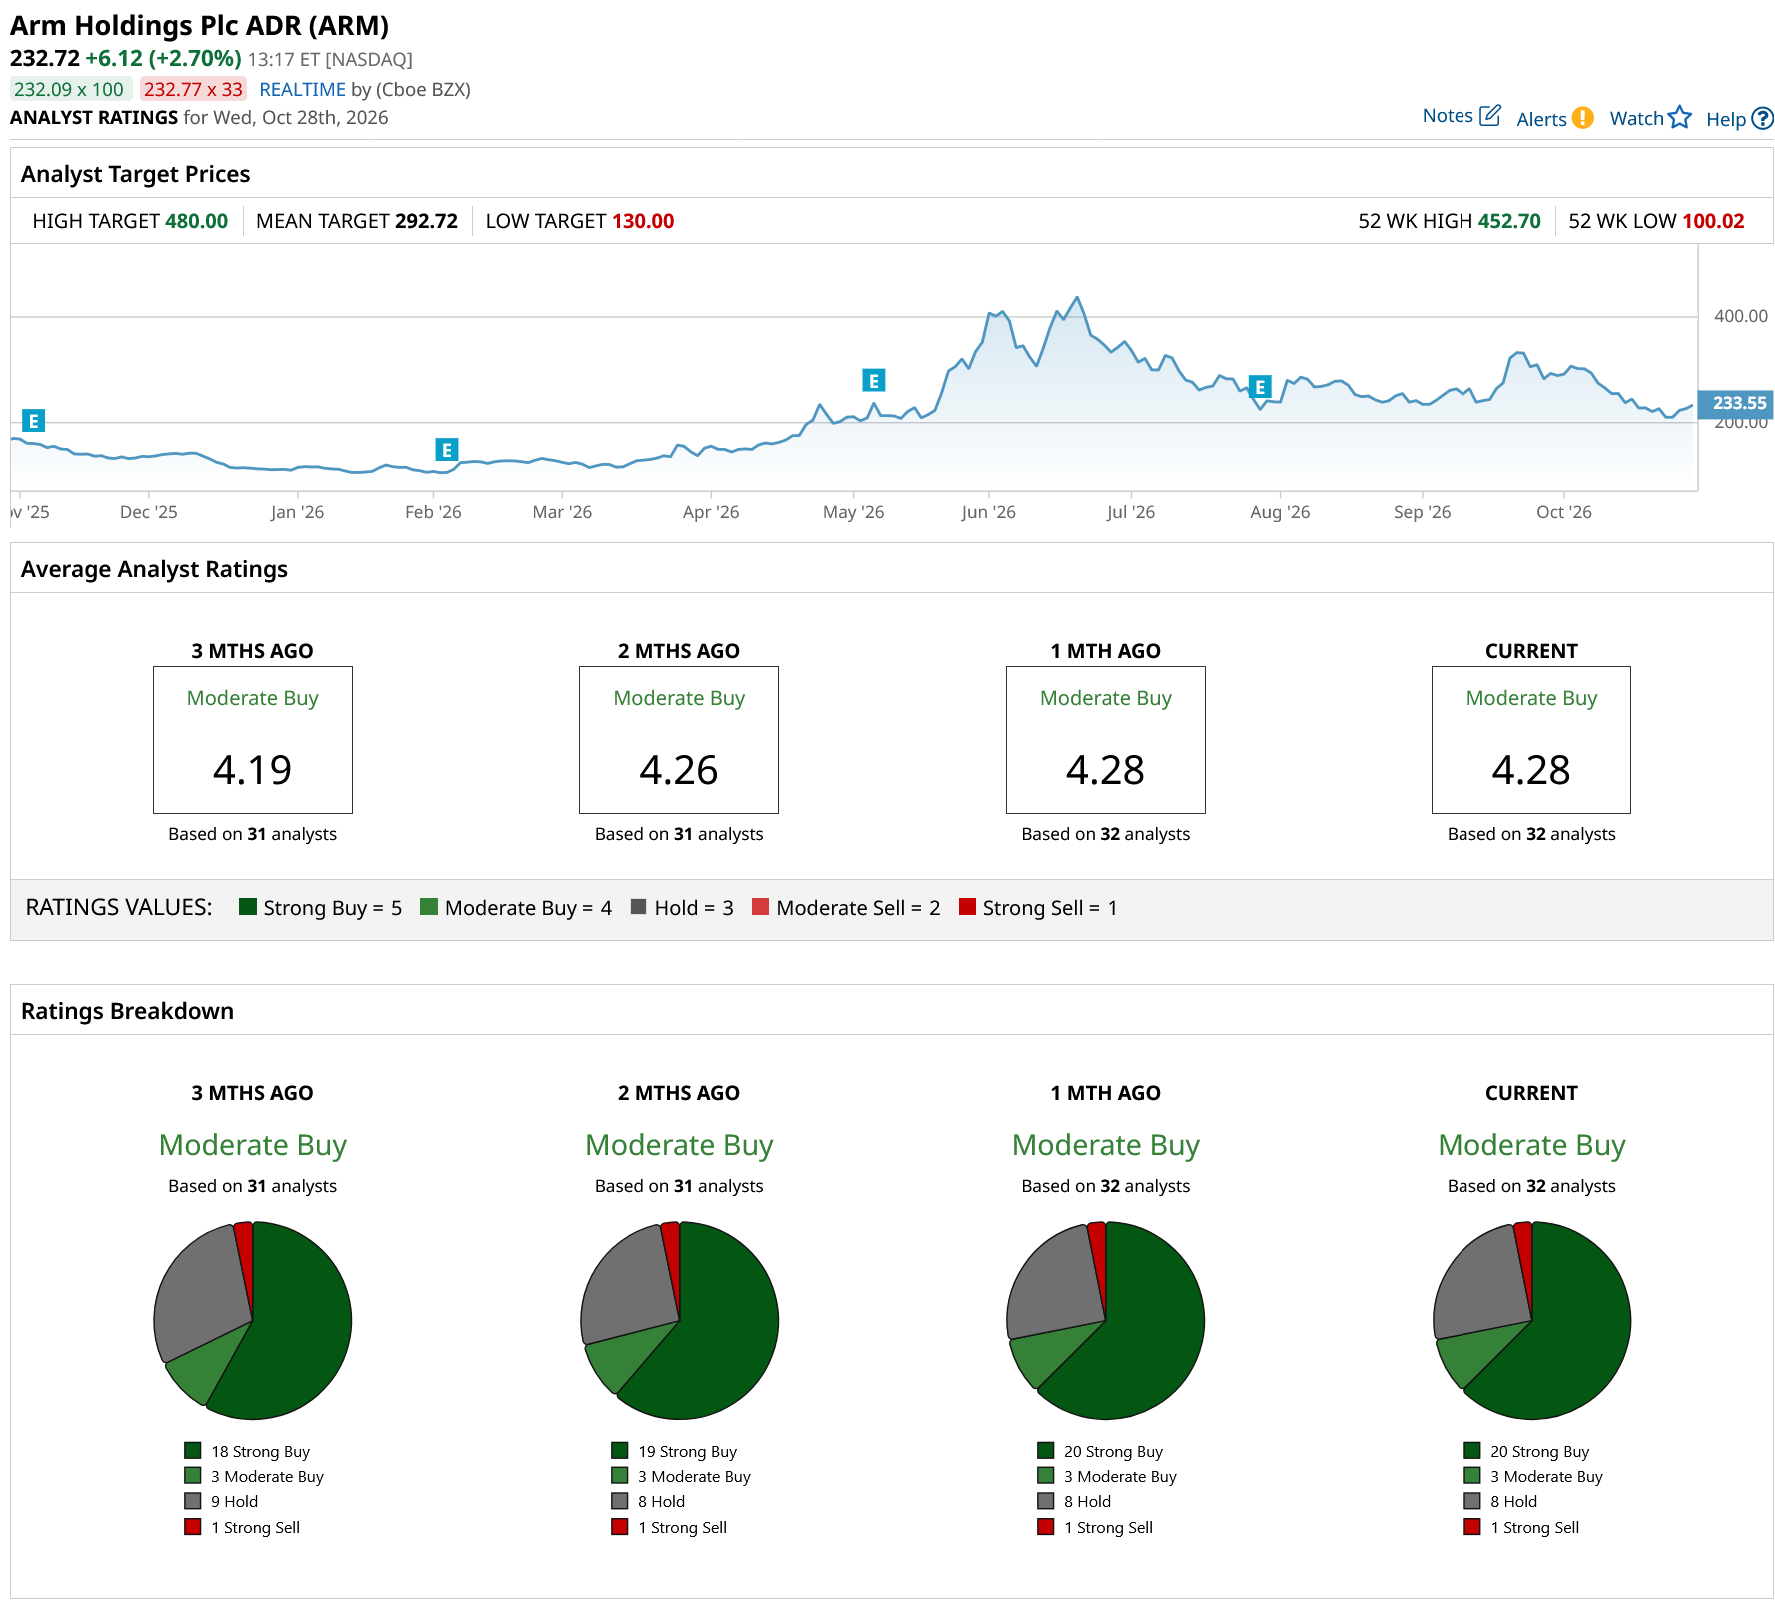
Analysts currently have a “Moderate Buy” consensus rating on ARM stock and a mean price target of $292.72.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.