


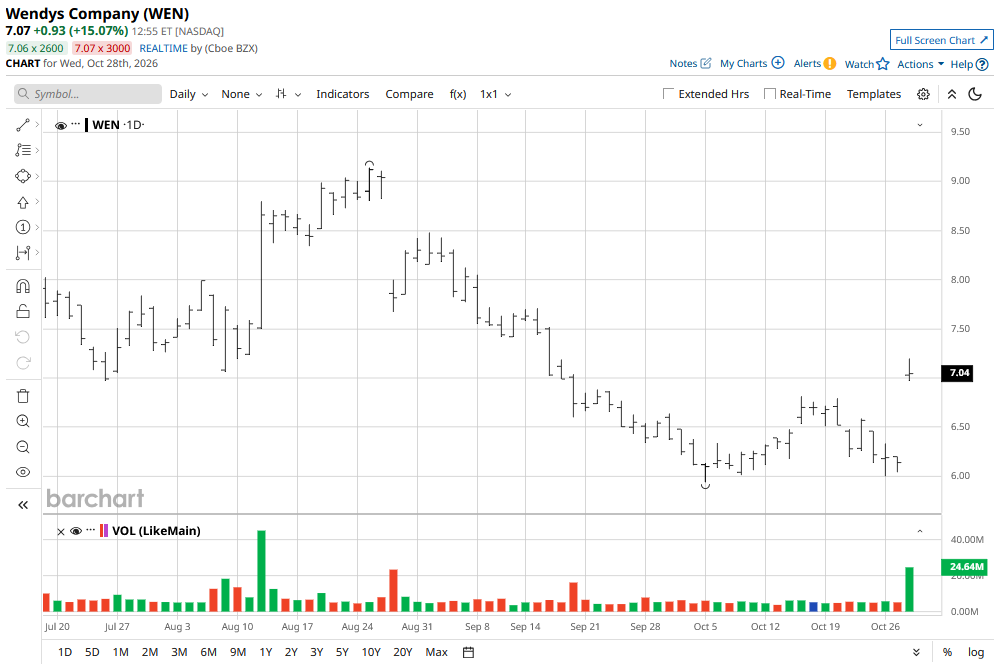
Wendy’s (WEN) stock charged higher on Wednesday after a consortium led by activist investor Nelson Peltz offered to take the burger chain private in a deal valued at about $1.4 billion. The all-cash proposal values WEN shares at $7.35 each, representing a $20 premium on the company’s previous close.
That said, Wendy’s is still trading at a more than 10% discount compared to its price at the start of this year.
What the Take-Private Proposal Means for WEN Stock
Peltz’s activist hedge fund Trian Fund Management has teamed up with Flynn Group, BlueFive Capital, and Sixth Street Partners on the proposed acquisition. Together, they already control roughly 16.3% of Wendy’s, giving the approach backing from substantial existing shareholders.
The bullish argument starts with the cash premium: shareholders could receive an immediate uplift without waiting for a restaurant turnaround to deliver.
The consortium also said its proposed structure would require no new debt — with Wendy’s existing securitization financing expected to remain in place.
Private ownership would provide longer-term capital to address competitive pressures and rebuild performance, it added.
Is There Any Further Upside Left in Wendy’s Shares?
As of this writing, Wendy’s shares are trading at about $7.10, down about 3.4% versus the buyout price. This means much of the immediate takeover premium has already been captured in Wednesday’s surge.
A materially bigger gain would likely require a higher offer, a competing proposal, or confidence in Wendy’s standalone prospects — none of which is assured.
Importantly, this remains a non-binding proposal. Definitive agreements have yet to be negotiated, and the filing says equity financing arrangements remain under discussion. There’s a possibility, therefore, that investors end up revising or even abandoning the buyout plans.
For new investors, this signals a relatively modest potential payout against a risk that negotiations fail and takeover enthusiasm unwinds.
Wall Street’s Consensus View on Wendy’s
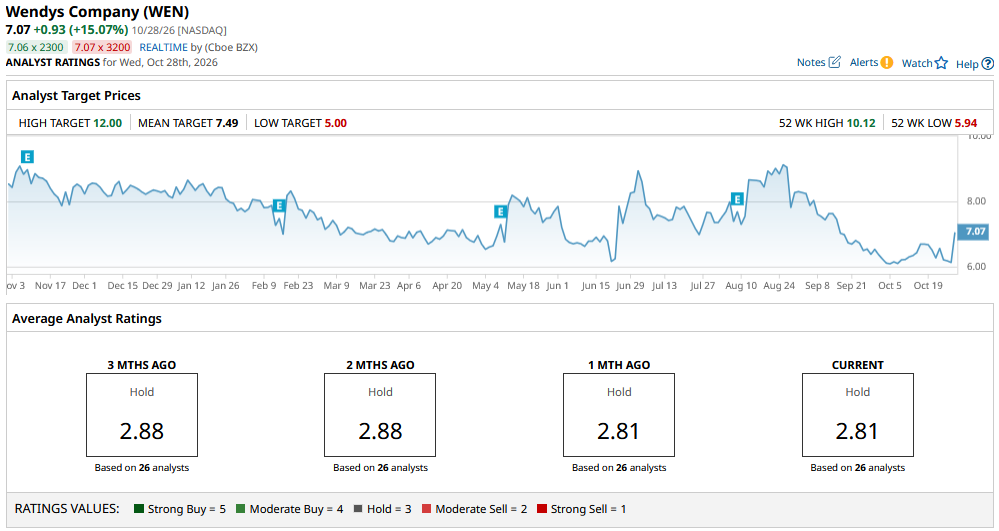
Heading into Oct. 28, Wall Street had a consensus “Hold” rating on WEN shares, with a mean price target of about $7.49. This suggests analysts did not expect Wendy’s to be worth significantly more than the valuation assigned to it in its buyout proposal.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.