


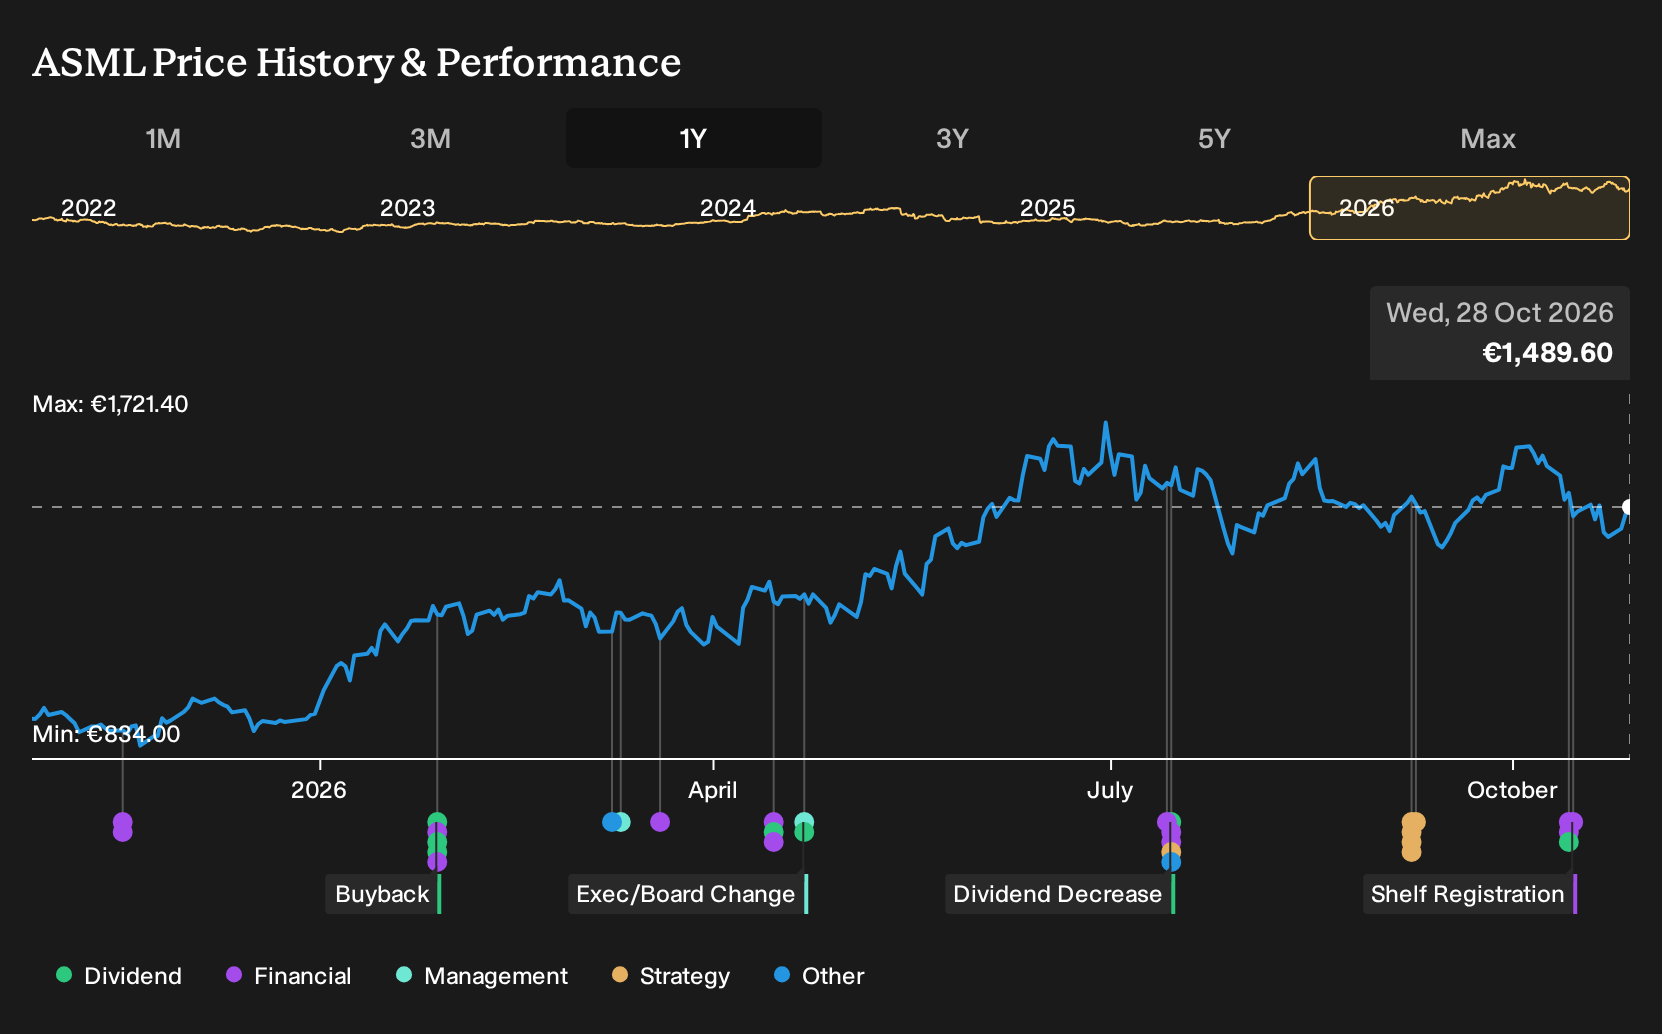
- ASML Holding reported third quarter 2026 revenue of €11,662 million and net income of €4,960.4 million, issued higher fourth quarter and full-year sales guidance, continued its 2026 share buyback program, and confirmed an interim dividend of €1.88 per ordinary share payable on November 4, 2026.
- The business remains the sole supplier of advanced lithography tools for leading-edge chips. As a result, strong AI infrastructure demand and export control risks are directly shaping ASML Holding’s order patterns, pricing power, and long-term role in the Dutch economy.
- This article examines how ASML Holding’s updated earnings guidance and AI-related lithography demand are influencing the way investors frame the company’s current investment narrative.
Scan beyond ASML Holding and track other AI infrastructure beneficiaries with the hand picked 55 AI infrastructure stocks that are also tied directly to this capex wave.
ASML Holding Investment Narrative Recap
To own ASML Holding, you have to believe that demand for advanced EUV and High NA tools, plus installed base services, will keep absorbing the firm’s expanding capacity and that AI related capex remains supportive. The Q3 2026 results and higher full year guidance reinforce that this thesis still rests mainly on execution, not on a change in story.
The clearest near term swing factor is how quickly chipmakers convert AI driven plans into concrete orders for high value systems and upgrades. The biggest operational risk remains export restriction uncertainty around China, which could affect regional orders, but the latest quarterly update does not materially change that risk profile.
The earnings guidance issued on 14 October 2026 looks most relevant here. Management now expects Q4 2026 net sales between €14.2b and €15.2b with gross margin around 57%, and full year 2026 sales between €44b and €45b with margin around 56%. That frames how much AI infrastructure demand is currently flowing into the order book.
For you as a shareholder, this outlook connects directly to the catalysts around EUV adoption, High NA ramp and Installed Base Management growth. Execution toward those targets can influence how investors judge the durability of ASML Holding’s pricing power and cash generation, while any disruption from geopolitics or slower High NA uptake would test that confidence.
What The Current ASML Holding Forecasts Assume
ASML Holding's narrative projects €72.8b revenue and €29.5b earnings by 2029. Analysts are building this on 22.6% yearly revenue growth and an earnings increase of about €16.0b from €13.5b today.
Uncover why ASML Holding's fair value indicates a 43% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on ASML Holding focuses less on export risk and more on how far AI driven demand could stretch earnings. The most optimistic analysts were pencilling in €92.0b revenue and €40.8b earnings by 2029, well above consensus. Those forecasts came before this guidance and dividend news, so the story they tell may still evolve.
Explore 22 other ASML Holding fair value estimates, including one that suggests as much as 77% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your ASML Holding research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for ASML Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ASML Holding's overall financial health at a glance.
Looking for more investment ideas beyond ASML Holding?
If the ASML Holding story has sharpened your view on AI infrastructure and semiconductor spending, it can help to compare it with other businesses that share some of the same cash flow, balance sheet, or income characteristics. The Simply Wall St Screener lets you move from a single stock narrative to a watchlist of opportunities that fit your own risk and return preferences.
- For investors who want potential mispricings backed by solid fundamentals, start with a curated set of value opportunities using the 195 high quality undervalued stocks.
- If capital preservation and financial resilience sit higher on your list, narrow your focus to companies with strong balance sheets using the 223 resilient stocks with low risk scores.
- When you are hunting for future compounders that are not yet widely followed, cast a wider net with the 610 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com