


Dropbox (DBX) shares came under pressure on Wednesday after the cloud-storage firm announced a fresh wave of layoffs alongside its tech chief’s departure. About 200 positions are being eliminated as DBX management redirects resources toward growth initiatives. The job cuts span engineering, product, design, and administrative teams.
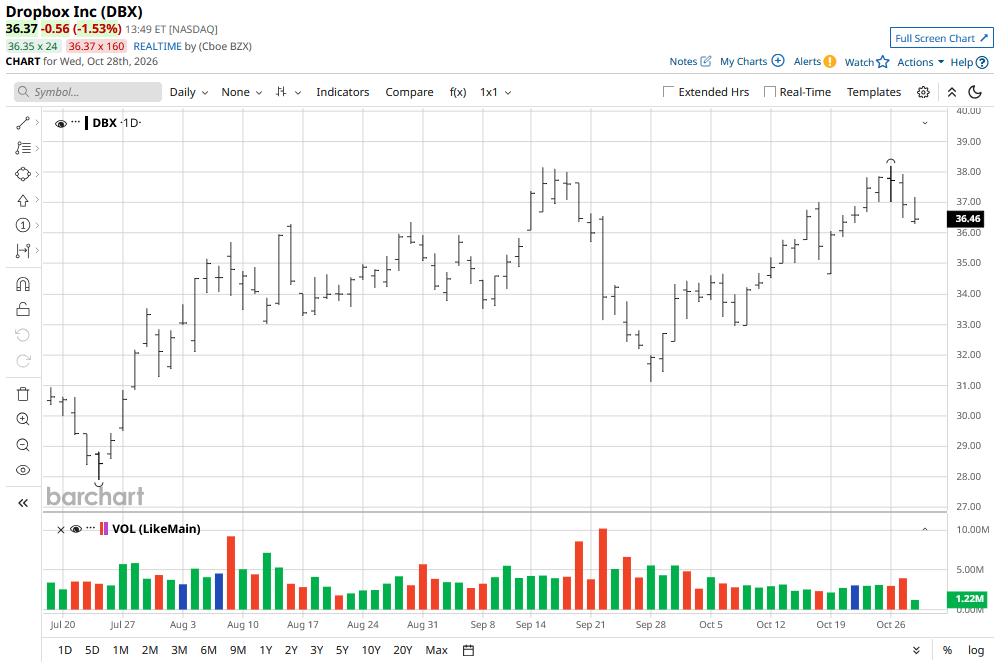
Dropbox stock has been a lucrative investment in 2026, currently up more than 60% versus its year-to-date low.
Significance of the Layoffs for Dropbox Stock
In its press release, Dropbox said the announced restructuring will affect roughly 9% of its global workforce, and that its chief technology officer (CTO) will leave on Nov. 18.
The company estimates cash expenditures of about $30 million, including severance and employee benefits, with incremental expenses totaling up to $25 million. Most payments and substantially all incremental expenses are expected in the final quarter of 2026.
For shareholders, the potential benefit is a lower ongoing cost base that could support profitability. However, severance creates an immediate cash burden, while reductions across engineering and product divisions introduce execution risks.
DBX stock is in the red as investors evaluate whether they believe a smaller team can deliver on management’s growth priorities heading into 2027.
Should You Buy the Dip in DBX Shares?
Today’s pullback alone offers limited grounds for buying Dropbox shares, especially since they’re still trading at a premium price-to-earnings (P/E) multiple of nearly 20x.
The corporate update did have an encouraging signal, though. Management expects Q3 revenue and adjusted operating margin to meet or exceed its previous guidance.
Dropbox is scheduled to post its complete financial release for the current quarter on Nov. 5.
From a technical perspective, DBX looks attractive, with the share price keeping decisively above the major moving averages (MAs) and an RSI in the early 50s indicating significant buying pressure.
What Analysts Expect From Dropbox Moving Forward
Wall Street analysts nonetheless warrant some caution in playing Dropbox at current levels.
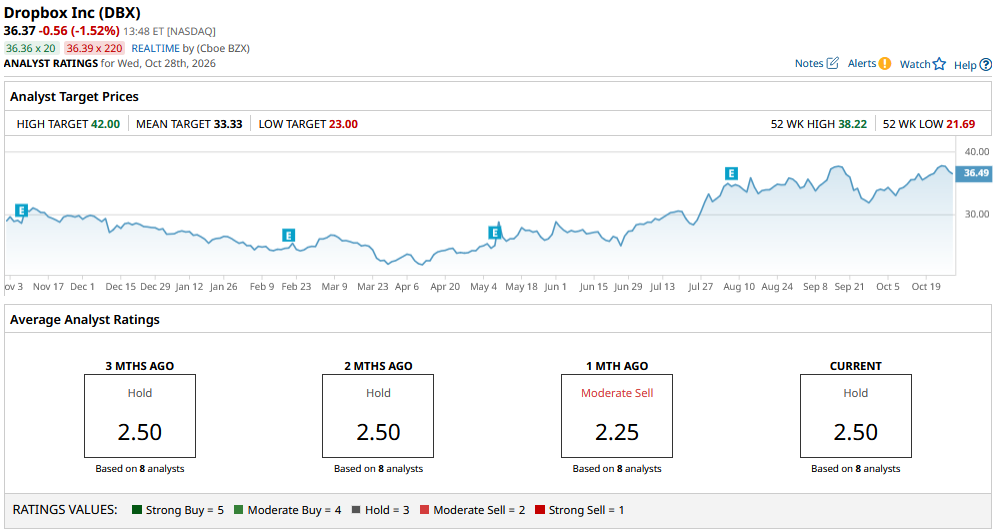
According to Barchart, the consensus rating on DBX shares sits at “Hold,” with the mean price target of about $33 indicating potential for a 9% decline from current levels.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.