


Ball has delivered a solid share price run in recent years, and that leaves investors asking whether the current US$64.10 level is supported by the earnings the packaging group generates today. With the spotlight firmly on profitability and cash generation, the key issue is how much of that recent gain is already pricing in the business performance that lies ahead.
- Over the past 3 years the stock has returned 38.7%, which puts real weight on the question of whether Ball's current earnings can carry that track record further.
- The business relies heavily on converting earnings into steady cash flow to fund its capital intensive operations, which can shape how much investors are prepared to pay for each dollar of profit.
- Your read on Ball is one view; the desks covering it have another. See what analysts think Ball's shares could be worth.
The issue now is whether Ball's present share price is justified by the level and quality of its earnings.
If you are weighing Ball against other options that also focus on earnings and valuation, a focused stock screen can be a useful starting point, especially with the 29 high quality undervalued stocks.
Is Ball Fairly Priced on Earnings?
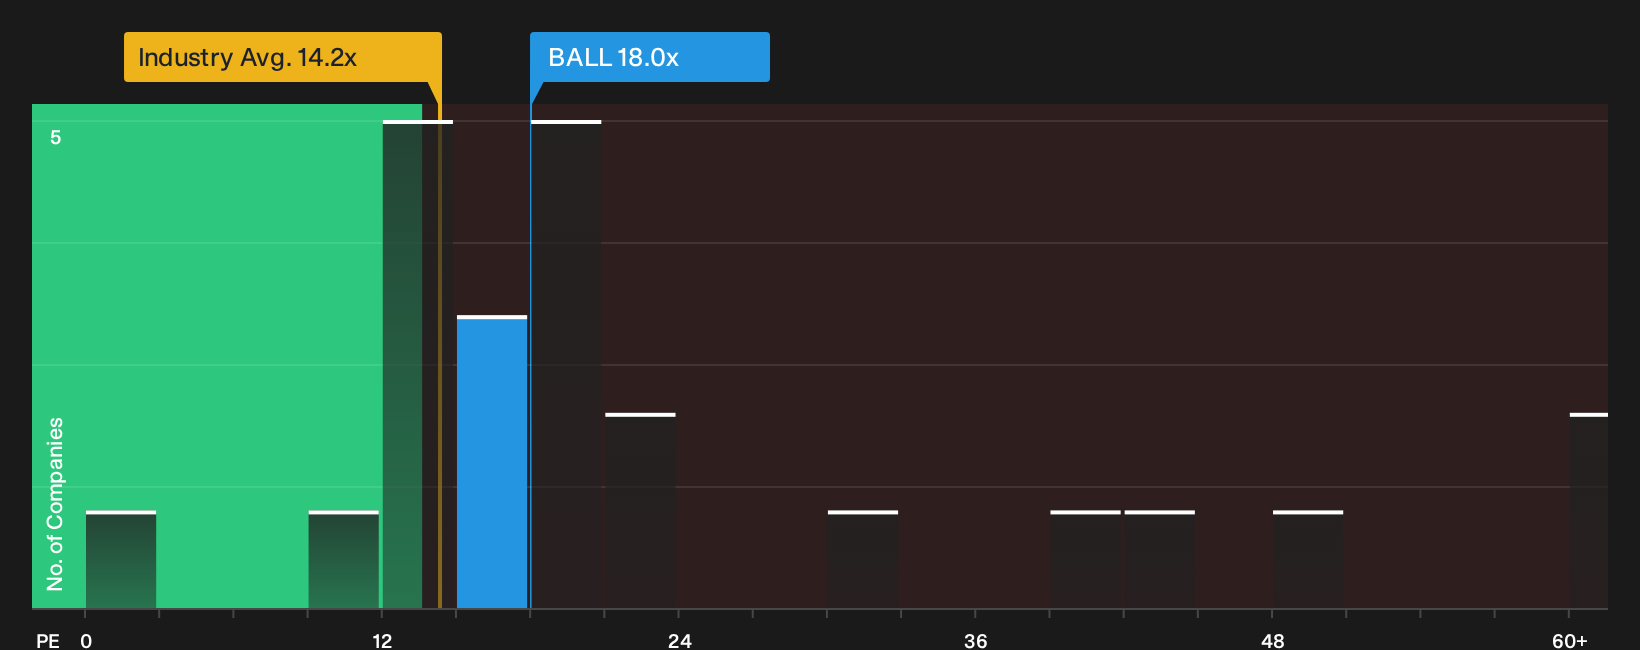
P/E fits Ball reasonably well because earnings remain a central reference point for how the group funds its capital heavy can making operations. On this measure, the stock trades on a P/E of 18.0x, which is above the packaging industry average of 14.2x and very close to the 18.4x level seen across immediate peers.
The tailored fair multiple, which blends Ball’s sector, profitability profile, scale and risk into a single reference point, suggests the current P/E sits broadly in line with what would be expected for this type of business. That keeps the focus on whether the quality and resilience of Ball’s earnings match what the market is already paying for each dollar of profit, and whether you are comfortable owning a packaging stock that prices more like its peer group than the wider sector. Explore the numbers behind Ball's P/E valuation.
The Ball Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E debate leaves off for Ball and spell out what would need to happen to future earnings, growth and profitability for the current share price to look either conservative or stretched. Instead of focusing on a single multiple or valuation line, each narrative lays out the assumptions behind its fair value view so you can compare those expectations with Ball's actual results as they are reported on Simply Wall St's Community page.
Community views on Ball are split between those who see more upside left in the current setup and others who are more cautious on the cash story.
Bull case: 12% undervalued
"Post divestiture focus on core aluminum packaging and the roll out of the Ball Business System, which now targets $500 million of gross productivity savings by the end of 2026 and ongoing 1% to 2% annual supply chain cost reductions…"
Discover why this Narrative puts Ball at 12% undervalued.
Bear case: roughly fairly valued
"While global shipped beverage can volumes grew 4.3% year over year in Q2 2026 and the substrate shift shows cans gaining 2% to 3% share in a flat North American packaged beverage market, Ball’s gross margin around 21.3% trails peers and may cap how much this volume and mix shift actually improves net margins and earnings…"
Explore why this Narrative puts Ball at roughly fairly valued.
Ball's valuation leaves one crucial angle unresolved
Price multiples tell you what investors pay for Ball today, but the next layer is how professional analysts expect its earnings profile to look a few years from now. Explore where analysts expect Ball to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com