


Applied Digital has seen a sharp swing in sentiment, and with the share price around US$19.51 after a rocky year, the key question now is how well that market value lines up with what the business is generating in sales. With AI infrastructure demand in the spotlight and capital for neocloud operators getting tighter, the relationship between Applied Digital’s revenue base and its stock price has moved front and center for anyone looking at this ticker.
- Over the past 3 years the share price has climbed close to 3x, which puts real pressure on the numbers to show that Applied Digital’s sales can carry that kind of move.
- The joint venture with Soluna to build a 50 MW wind powered AI data center in Texas may support higher long term revenue, but it also concentrates more capital and execution risk into Applied Digital’s push to scale its infrastructure.
- There is a second opinion on Applied Digital worth weighing. See what analysts think Applied Digital's shares could be worth.
For investors, the debate is whether Applied Digital’s current share price is justified by the level and trajectory of its sales.
If you are weighing whether Applied Digital’s US$19.51 share price lines up with its sales, it can help to compare that question across 55 AI infrastructure stocks.
Has Applied Digital Run Too Far on Sales?
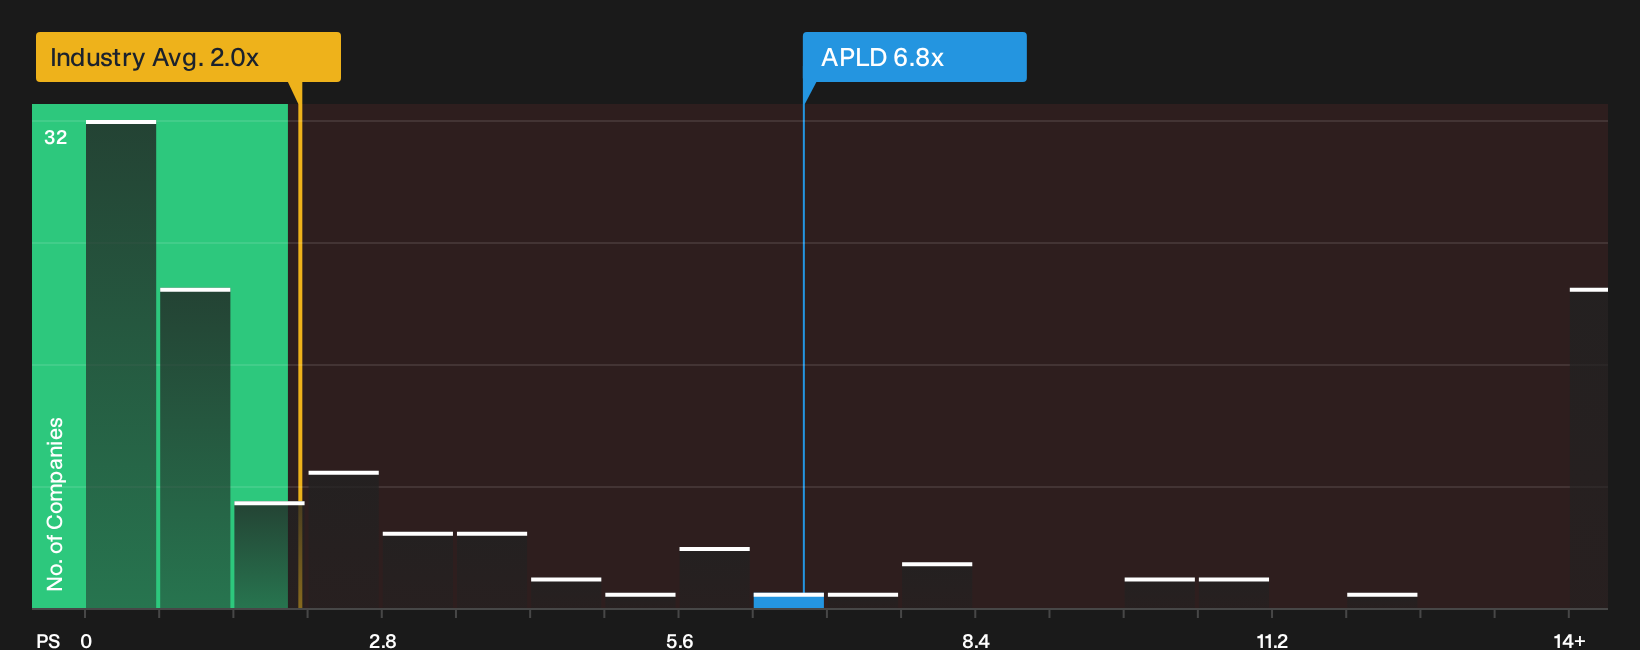
P/S fits Applied Digital because investors are mainly paying for revenue capacity rather than current profits. On this lens, the stock trades on a P/S of 6.8x, which is meaningfully higher than the IT sector average of 2.0x and also above the peer group on 5.7x. That suggests the market is already attaching a premium to each dollar of Applied Digital’s sales.
The fair multiple implied by the valuation model, which blends the company’s growth profile, margins, size and risk, sits below where the current P/S is. Because of that gap, the shares screen as overvalued on this sales metric, even after recent sector optimism lifted Applied Digital alongside other AI infrastructure plays. For anyone tracking neocloud headlines and joint ventures, the key question is whether future execution can justify paying this kind of mark up on today’s revenue base. Explore the numbers behind Applied Digital's P/S valuation.
The Applied Digital Narrative: What Would Justify Today's Price?
Narratives for Applied Digital pick up where the P/S puzzle leaves off by spelling out which revenue growth paths, margin profiles and future earnings power would need to play out for the stock to be worth materially more or less than today’s price. They sit on Simply Wall St’s Community page as a way to track that thinking over time. Each one treats fair value as a thesis about the business that can be revisited as new information emerges, rather than a single frozen estimate.
One of the top community narratives on Applied Digital: 69% undervalued
"Long term AI hyperscaler contracts, efficient building processes, and strategic locations drive revenue growth, margin expansion, and sustainability advantages..."
Discover why this Narrative puts Applied Digital at 69% undervalued.
Applied Digital's price tag still hinges on one missing piece
Big data center plans only matter if the people in charge are aligned with you, and how the leadership team is rewarded can quietly tilt decisions in powerful ways. See who runs Applied Digital and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com