


GE HealthCare Technologies has spent 2026 in reverse, with the share price down year to date even as headlines focus on product launches, acquisitions and a sizeable order book. That mix of a weaker chart and active execution raises a straightforward question for you as an investor: is the current valuation adequately supported by the company’s earnings profile?
- The stock is down 14.1% year to date, which puts more attention on whether today’s multiple on its profits still lines up with what you are paying now.
- Recent deals, new imaging systems and a growing order backlog can influence how reliably future income converts into cash, which feeds directly into how much investors might be willing to pay for each dollar of earnings.
- There is a second opinion on GE HealthCare Technologies worth weighing. See what analysts think GE HealthCare Technologies's shares could be worth.
The issue now is whether the current price for GE HealthCare Technologies is justified by its earnings when set against the Fair Ratio benchmark.
If you want a broader watchlist while you assess whether GE HealthCare Technologies’ current earnings multiple still works for you, a focused screener built around 34 healthcare AI stocks can be a useful second reference point.
Does GE HealthCare Technologies Look Undervalued on Earnings?
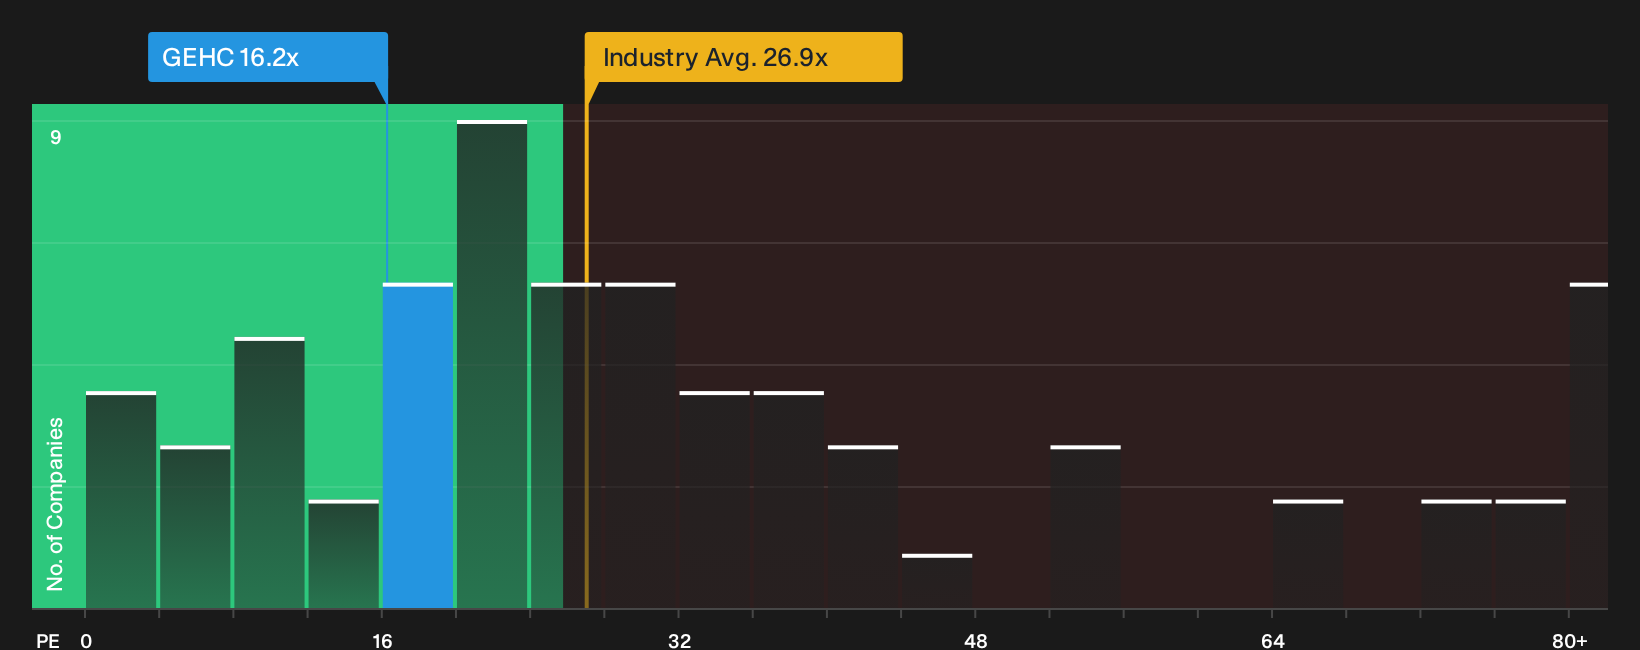
The P/E ratio works well for GE HealthCare Technologies because earnings are a key lens for large, established medical equipment providers. The stock trades on a P/E of 16.2x, which is well below the Medical Equipment industry average of 26.9x and the peer group at 29.8x. Against the tailored Fair Ratio benchmark that reflects GE HealthCare Technologies’ own mix of growth prospects, margins, scale and risk, the current earnings multiple screens as undervalued rather than stretched.
Because the recent Q3 2026 update flagged stronger than expected results and higher full year guidance, the gap between the current 16.2x and broader sector pricing suggests the optimism in the headlines is not fully reflected in what you are paying per dollar of earnings. For an investor weighing GE HealthCare Technologies against other large healthcare equipment stocks, that discount on the preferred P/E yardstick is the key number to test against your view of the order backlog, AI roll out and acquisition pipeline. Explore the numbers behind GE HealthCare Technologies's P/E valuation.
The GE HealthCare Technologies Narrative: What Would Justify Today's Price?
Narratives on GE HealthCare Technologies work as the missing link between the current P/E puzzle and the assumptions that could justify a very different share price. They spell out which paths for growth, profitability and earnings would need to hold for the stock to be worth materially more or less than it is today on Simply Wall St's Community page. Each scenario ties a specific valuation to a clear set of potential catalysts and pressure points so you can track which storyline is closest to how the business actually develops.
Community views on GE HealthCare Technologies are split between those who see more upside in the backlog and product cycle and those who think current expectations already reflect most of the story.
Bull case: 14% undervalued
"The current narrative that GE HealthCare Technologies is undervalued implies that the share price does not fully reflect the record backlog, the contribution from higher margin Advanced Imaging Solutions and Pharmaceutical Diagnostics, and the expected multiyear contribution from Flyrcado and other new products..."
Discover why this Narrative puts GE HealthCare Technologies at 14% undervalued.
Bear case: roughly fairly valued
"While the company is bringing a broad wave of new CT and MR systems to market, the long lag between regulatory clearance, order conversion and site readiness means much of the expected revenue is pushed into 2027 and beyond..."
Explore why this Narrative puts GE HealthCare Technologies at roughly fairly valued.
One more filter for GE HealthCare Technologies before you move on
The last piece that can change how you read GE HealthCare Technologies is who is in charge and how their incentives line up with your goals. See who runs GE HealthCare Technologies and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com