


Why the new earnings guidance matters for China Nonferrous Mining
China Nonferrous Mining (SEHK:1258) just flagged a sharp reset in profitability expectations. Management now guides for profit attributable to shareholders of about US$634 million for the nine months to 30 September 2026, up roughly 78% year-on-year.
This jump in earnings guidance lands even as production volumes for key products such as copper cathodes, blister copper, anodes, sulphuric acid and cobalt hydroxide all moved lower compared with the same period a year earlier.
China Nonferrous Mining’s share price has slipped over the year despite the upgraded earnings outlook, with a 30-day share price return of down 14.94% and a year-to-date share price return of down 16.12%. At the same time, the 3-year total shareholder return is a little over 20x and the 5-year total shareholder return is more than 5x, which suggests long-term holders are sitting on very large gains while short-term momentum has faded.
Spot opportunities beyond China Nonferrous Mining by scanning a curated 16 top copper producer stocks that could also be sensitive to the same copper price tailwinds driving this new earnings guidance.China Nonferrous Mining now trades well below both analyst targets and some intrinsic value estimates, even after the recent pullback. Is that a simple mispricing, or a rational discount on suddenly copper-fuelled earnings?
Preferred Price-to-Earnings of 11x: Is it justified for China Nonferrous Mining?
On simple earnings multiples, China Nonferrous Mining trades on a P/E of 11x, which looks rich compared with several reference points even though the share price is down over the year. That gap between the tag on the shares and the rest of the Hong Kong metals and mining space raises a clear question about what the market is pricing in.
The P/E ratio compares what investors are paying for each dollar of earnings. It matters a lot for a business like China Nonferrous Mining because profits can swing with commodity prices and operating efficiency, so the multiple often acts as a shorthand for how durable the current profit run rate is perceived to be.
Against that backdrop, the stock changes hands on 11x earnings while the Hong Kong metals and mining industry sits at 8.7x and the peer group average is 7.1x. That is a steep premium. Our fair P/E estimate sits at 10.2x, which implies the market valuation could eventually gravitate closer to that level if expectations cool.
Explore the SWS fair ratio for China Nonferrous Mining.
Result: Price-to-Earnings of 11x (OVERVALUED)
Still, China Nonferrous Mining faces clear pressure points if copper pricing eases or if operational issues in Zambia and the DRC disrupt leaching and smelting output.
Find out about the key risks to this China Nonferrous Mining narrative.
Another view on China Nonferrous Mining’s value
While the 11x P/E makes China Nonferrous Mining look expensive compared with the Hong Kong metals and mining group at 8.7x and peers at 7.1x, the SWS DCF model suggests a different perspective. On that future cash flow lens, the shares trade well below an estimated fair value of HK$51.39. Which signal should carry more weight for you as an investor?
Look into how the SWS DCF model arrives at its fair value.
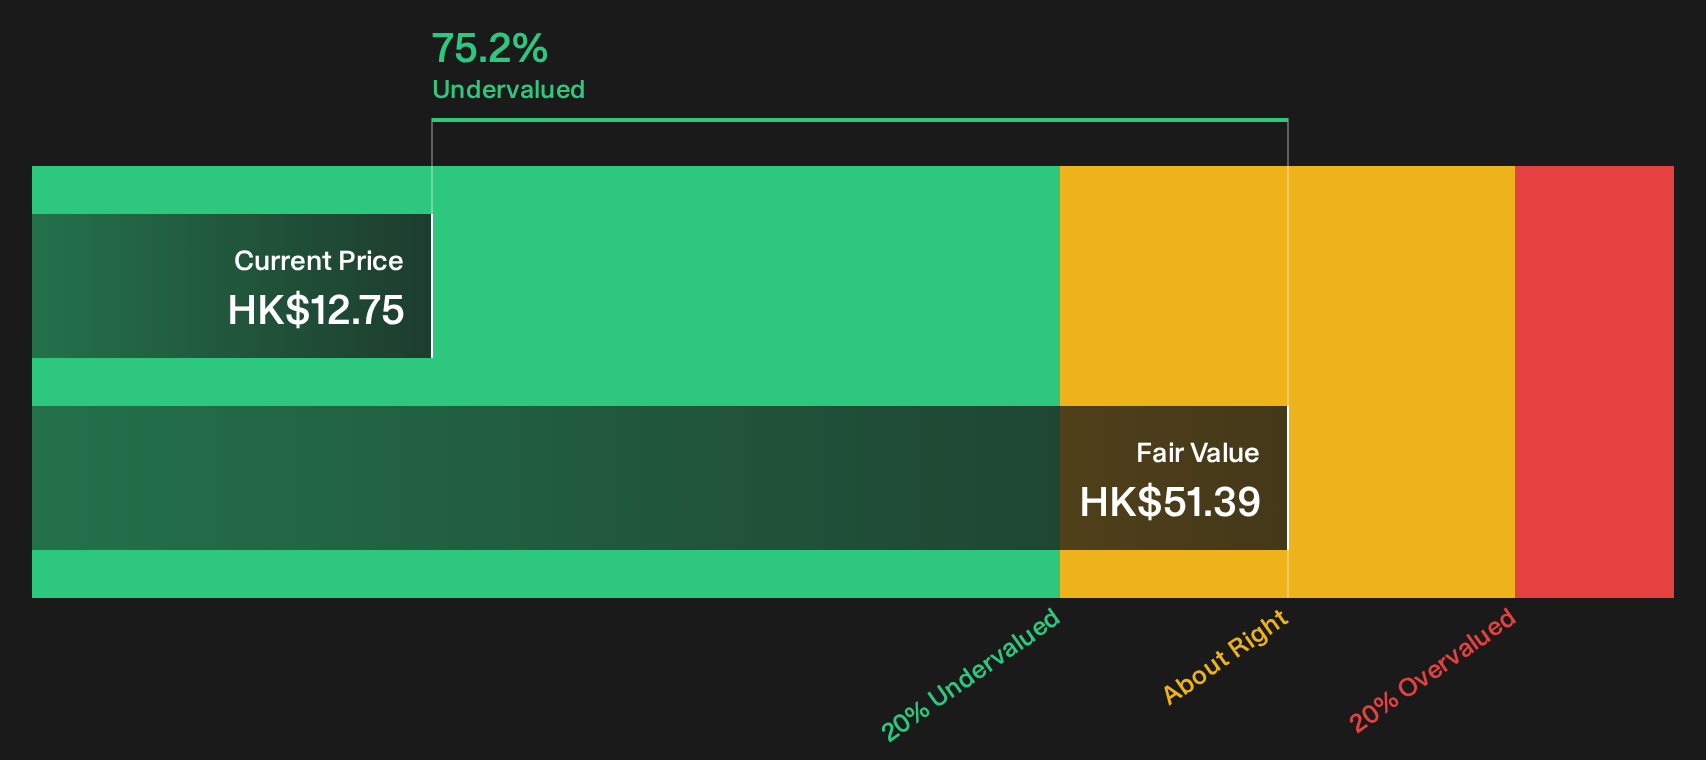
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Nonferrous Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of upgraded guidance and a richer P/E on China Nonferrous Mining leaves you torn, do not wait for a consensus to form. Instead, stress test the numbers and scenario assumptions yourself, then weigh those findings against the 3 key rewards
Looking for more investment ideas beyond China Nonferrous Mining?
If China Nonferrous Mining has your attention, widen your watchlist now so you do not miss other opportunities that may fit your style even better.
- Target resilient compounding potential by reviewing a 223 resilient stocks with low risk scores that emphasise stability and lower downside scores for investors who hate nasty surprises.
- Hunt for quality at a discount through a 610 high quality undiscovered gems that focuses on strong fundamentals before the crowd catches on.
- Prioritise financial strength by scanning a list of solid balance sheet and fundamentals (207 results) so you focus on businesses with sturdier foundations when markets turn choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com