


Temenos came into this Q3 2026 report with a solid year-to-date run, the stock up 12.9% over the past month and 11.4% over three months to close at CHF75.05 on 28 October. The software group is widely treated as a steady banking technology compounder, yet the fresh quarter shows a sharper profitability story. Non IFRS EBIT margin reached 37.3% and earnings per share on that basis climbed 32%, while free cash flow rose 24% to US$36m. The share price move now has to be weighed against that margin power and what it indicates about the underlying engine.
Like the mix of higher profitability and stronger free cash flow at Temenos but want a broader set of banking tech players with similar discipline on the cash line? Scan the list of solid balance sheet and fundamentals stocks (207 results) for peers that pair robust balance sheets with healthier fundamentals.
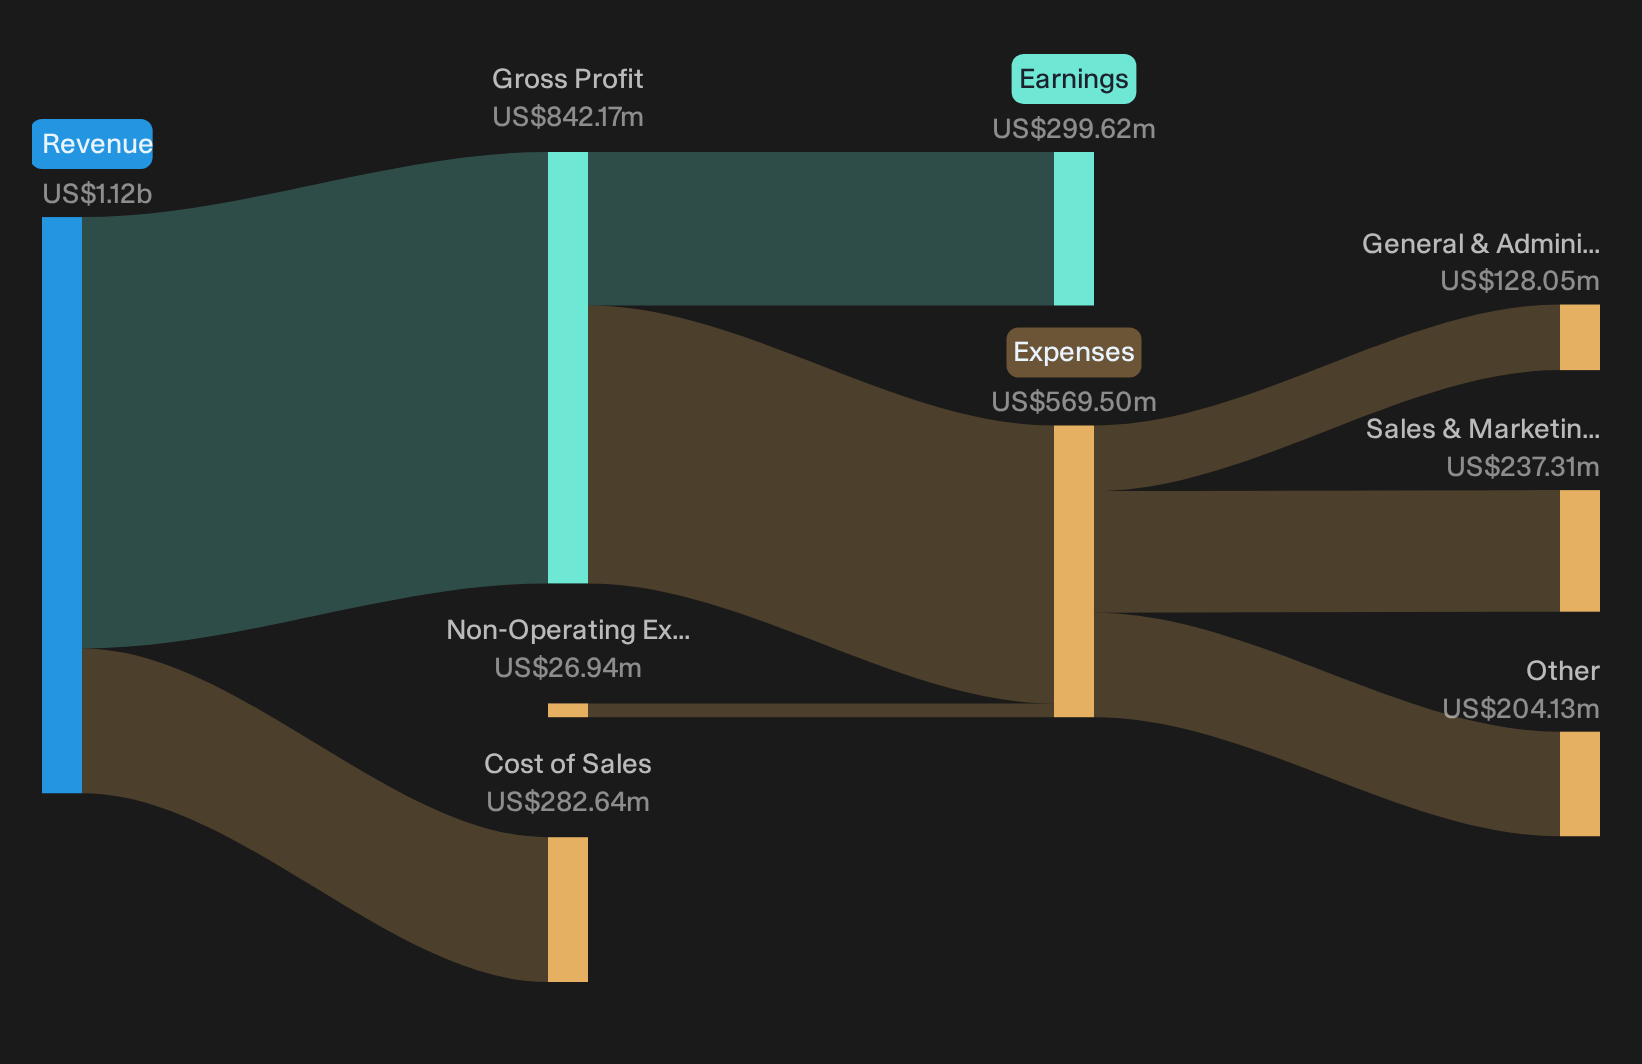
Q3 2026 Temenos Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$241.9m loss in Q3 2026 total revenue vs. US$258.5m in Q3 2025 (reported as a revenue decline into negative territory in Q3 2026)
- Net Income (Q3 2026 vs Q3 2025): Net loss of US$43.6m in Q3 2026 vs. net income of US$44.4m in Q3 2025 (swing into loss)
- Basic EPS (Q3 2026 vs Q3 2025): Loss per share of US$0.62 in Q3 2026 vs. earnings per share of US$0.65 in Q3 2025 (move from profit to loss)
- Non IFRS EBIT Margin (Q3 2026 vs Q3 2025): 37.3% in Q3 2026 vs. the prior-year quarter margin, which is implied to be about 4 percentage points lower (margin level now materially higher year on year)
Quarterly earnings can be affected by accounting items, while cash flows show the actual money Temenos is pulling in and what that might imply for long term value.
Looking at Temenos' cash generation rather than the headline loss, the stock could be a slight 13% undervalued.
Temenos Bull Case: Execution Versus Ambition
Optimists argue Temenos can turn AI and product investment into a wider moat and better economics.
"The company is investing heavily in AI powered products and expanding sales coverage, particularly in the U.S. Tier 2 and Tier 3 bank segment and other regions. Management sees a large long term market need for core banking modernization, which, if it converts into more deals from the growing pipeline, could support revenue, operating leverage and free cash flow."
Q3 shows this thesis partly on track. Subscription and SaaS revenue rose 22%, ARR reached US$904m, and free cash flow increased 24% to US$36m. Wins such as Vancity, Sound Credit Union and Kingdom Bank indicate that expanded coverage is translating into concrete cloud deals.
Temenos Bear Case: Cost And Timing Risks Tested
More cautious investors worry Temenos is loading up costs and deal risk faster than it is proving uptake.
"The rapid 50% planned increase in sales headcount worldwide, combined with heavier variable compensation weighted into the second half, risks embedding a structurally higher cost base that could compress EBIT margin and earnings if the enlarged pipeline does not convert into proportional deal volume."
Q3 margins moved the other way. Non IFRS EBIT margin reached 37.3% and non IFRS EBIT and EPS rose faster than revenue. A single Africa deal slipped into early Q4 but overall wins across Europe, North America and the Middle East suggest the larger commercial engine is currently supporting, not diluting, profitability.
One Narrative disagrees with today's price. → See where this Narrative says Temenos should trade.
Hunt For Mispriced Earnings Power
Temenos just showed how strong cash generation can sit beside a messy income statement. The real opportunity could be spotting stocks where that disconnect is still quietly building.
- Company 1 - 44% below our estimate - converts heavy spending on specialty injectables and new manufacturing lines into higher value contract work for complex drugs.
- Company 2 - 15% below our estimate - rides hyperscale data center builds as segment backlogs swell, even while receivables and project working capital demands climb rapidly.
- Company 3 - 18% below our estimate - leans into AI driven data center optics as expanded capacity fills with higher margin photonics and advanced packaging programs.
Three companies from the same screener. Open every one of the 195 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com