


Coupang has seen its share price come under heavy pressure over the past year, which puts fresh focus on whether the current market value is still supported by its sales base. With the stock now trading well below where it was 12 months ago, the core issue for you as an investor is how much revenue the business is generating relative to the price tag attached to each share.
- Over the past year the stock has fallen 56.4%, which puts recent sentiment and past expectations in direct conflict with what the sales line can realistically support.
- The new Nebraska beef direct sourcing program into South Korea may support higher transaction volumes and potentially richer mix over time, which matters for how much investors are willing to pay for each dollar of Coupang's sales.
- The analysts covering Coupang have run their own numbers. See what analysts think Coupang's shares could be worth.
The issue now is whether Coupang's current share price is justified by the level and quality of its sales.
If you want to benchmark Coupang's recent slide against other potential ideas with a valuation angle tied to business quality, it helps to compare it with companies from the 29 high quality undervalued stocks
Is Coupang a Bargain on Sales?
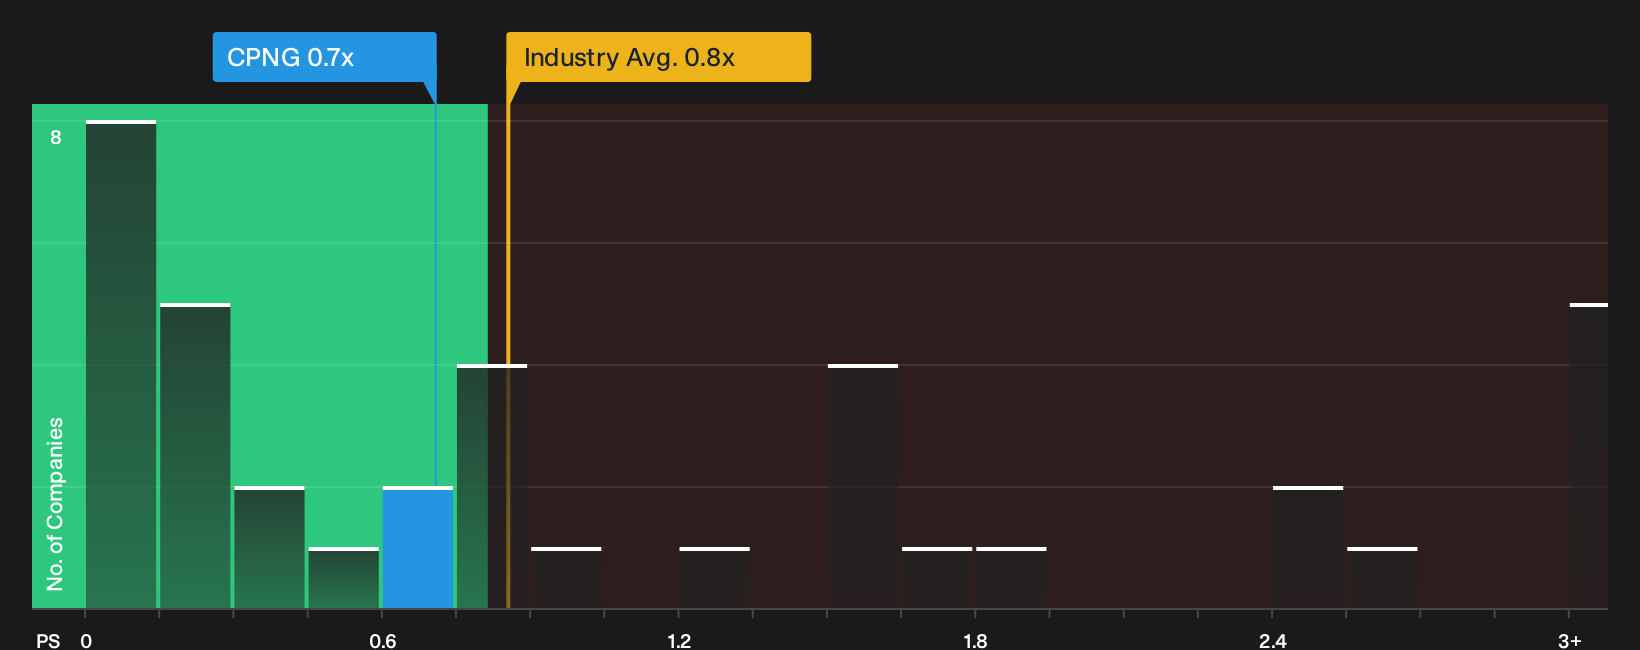
P/S fits Coupang because revenue is still the clearest anchor for how the market values the business. On this yardstick, Coupang trades on a P/S ratio of 0.7x, which is below the multiline retail industry average of 0.8x and well under the 1.9x peer group level. Compared with the tailored fair multiple implied by its own mix of growth prospects, margins, size and risk, the current P/S appears on the cheaper side, which indicates the stock screens as undervalued on this metric.
Because the new Nebraska beef direct sourcing program is aimed at adding volume and a richer product mix, the subdued P/S suggests the market is pricing Coupang at a discount even as it pushes into potentially higher value categories. That gap between price and sales expectations is what you need to weigh when judging whether the present multiple compensates for the execution and competitive risks that come with that expansion. Explore the numbers behind Coupang's P/S valuation.
The Coupang Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Coupang pick up where the P/S puzzle leaves off by spelling out which paths for Coupang's future growth, profitability and earnings would need to hold for the shares to be worth materially more or materially less than today. They sit on the platform's Community page and translate a single valuation output into the set of business outcomes behind it, so you can later judge whether those conditions actually play out.
One of the top community narratives on Coupang: 41% undervalued
"The main thing that has to go right is that Coupang converts its strong cohort spending patterns, WOW membership recovery, and international expansion into sustainable margin improvement while managing ongoing regulatory and operational risks in Korea…"
Discover why this Narrative puts Coupang at 41% undervalued.
One more Coupang check that sits beside the price tag
Before you lean too hard on the valuation work, it pays to look closely at who is steering Coupang and how their incentives line up with your interests. See who runs Coupang and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com