


Allstate has delivered a powerful share price run in recent years, which puts fresh attention on a basic question for you as a shareholder or prospective buyer. Is the current valuation of the insurer properly supported by the earnings power behind the ticker?
- Over the past 5 years, Allstate has returned 126.3%, which makes it important to test whether that performance still lines up with what its earnings can justify today.
- Arity’s planned acquisition of INRIX, announced as a long term move and expected to close by the end of 2026, can shape expectations for how data and analytics investments might affect Allstate’s profitability and required capital over time.
- The analysts covering Allstate have run their own numbers. See what analysts think Allstate's shares could be worth.
The issue now is whether Allstate’s current share price is appropriately backed by the earnings profile that investors are paying for.
If you want to test the same earnings question you are asking of Allstate across a wider field, line it up against 29 high quality undervalued stocks.
Is Allstate Still Cheap on Earnings?
For a mature insurer like Allstate, the P/E ratio gives a direct read on how much investors are paying for each dollar of earnings power today.
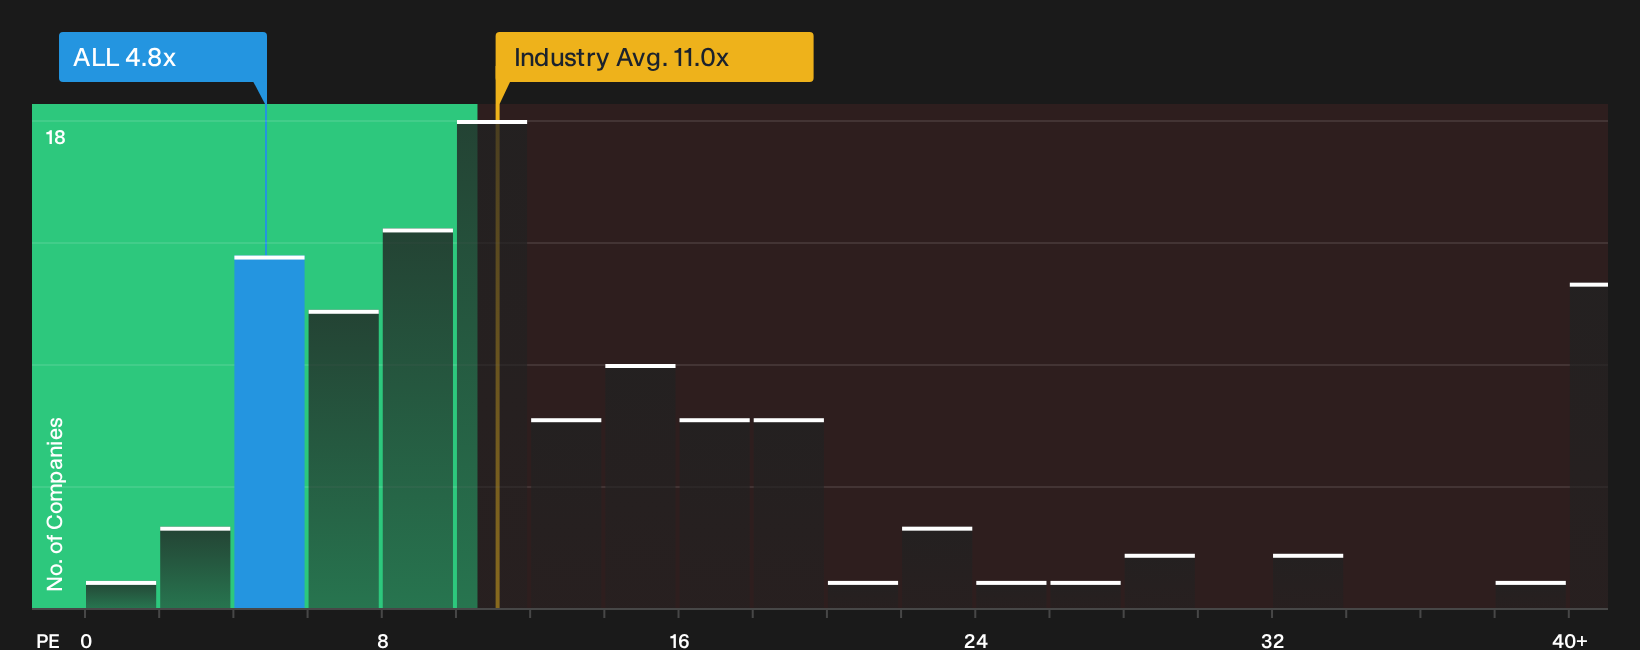
Allstate trades on a P/E of 4.8x, which is well below the Insurance sector average of 11.0x and also lower than peers at 11.3x. The fair multiple implied by its own earnings profile and risk mix sits higher than the current ratio. On this framework, the stock screens as undervalued on earnings. Because the planned Arity and INRIX tie up focuses attention on Allstate’s data and analytics potential, this low P/E will likely catch the eye of investors who are weighing how much of that story is already reflected in the price. Explore the numbers behind Allstate's P/E valuation.
The Allstate Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this Allstate valuation question leaves off by spelling out which assumptions on future growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price, and they sit on Allstate’s Community page. Each one replaces a single-point valuation with a clear set of underlying expectations, so you can compare those assumptions with Allstate’s actual results as they come through.
Allstate followers are split into two camps, with one group focused on discounted earnings power and another worried the price already reflects the good news.
Bull case: 8% undervalued
"Further development of Protection Services, where 177 million policies in force and US$3.4b of revenue are already in place, gives Allstate additional opportunities to sell protection plans, dealer services, roadside and identity protection..."
Discover why this Narrative puts Allstate at 8% undervalued.
Bear case: 29% overvalued
"The current valuation implies the share price already reflects a fairly valued Allstate, with the market pricing in both continued capital returns and the risk that catastrophe losses and legal outcomes could limit upside..."
Explore why this Narrative puts Allstate at 29% overvalued.
One more Allstate check investors often overlook
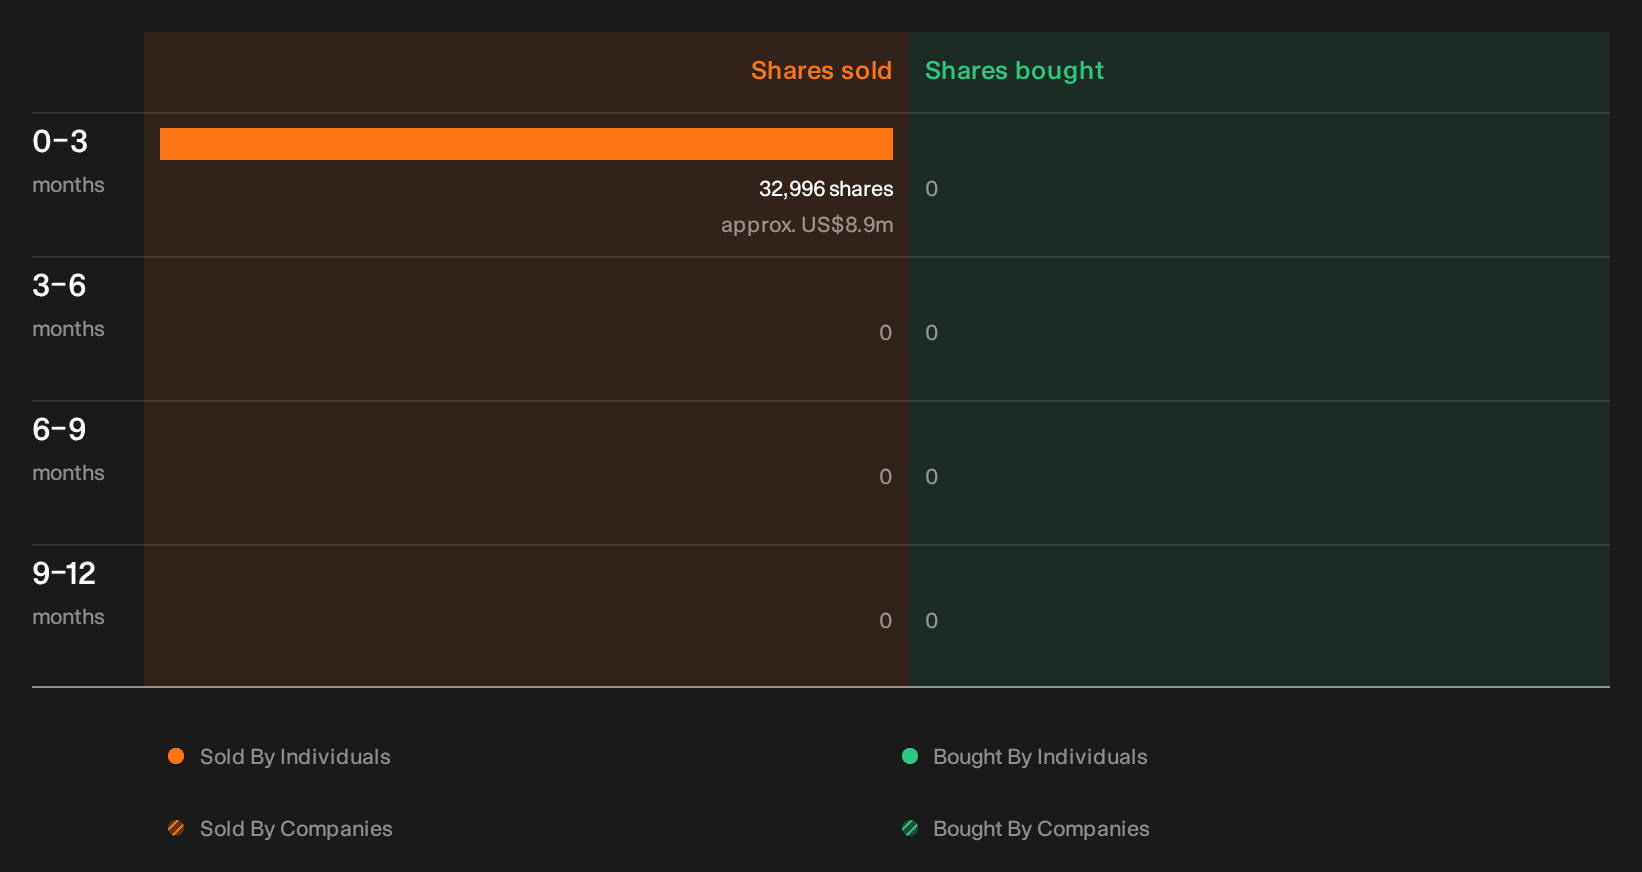
Allstate’s valuation story is only part of the picture, because recent trading activity by people inside the business has also tripped our checks. The specific sellers, sizes and possible read through are waiting for you to review. See the recent insider selling flagged for Allstate.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com