


Materion (MTRN) affirmed its income stream with a fourth quarter 2026 dividend of $0.145 per share, payable on December 4 to shareholders of record on November 19.
Materion’s latest dividend decision comes after a powerful run in the shares, with the stock up 24.45% on a 90-day share price return and 83.33% year to date. The 5-year total shareholder return of 179.27% points to momentum that has built steadily over time.
Scan beyond Materion and spot other advanced materials and industrial stocks showing strong share price action and income streams with the hand picked 21 high quality undiscovered gems.
The share price has sprinted ahead while analyst targets and intrinsic estimates still point higher. Where does fair value for Materion actually sit in that spread, and how much of the story is already priced in?
Most Popular Narrative: 22% Undervalued
Materion’s most followed narrative pegs fair value around $303.75 using a 9.0% discount rate, compared with a last close of $235.63. This frames the recent dividend move against a market that still prices in a discount to those long range cash flow assumptions.
Customer and contractor funded capacity and R&D projects, such as the US$65m beryllium capacity expansion structured to be funded by a prime contractor alongside other jointly funded initiatives, support capital efficient growth and help Materion pursue higher value programs that can feed through to revenue, EBITDA and earnings without a proportionate increase in balance sheet risk.
See why 11 investors see Materion as 22% undervalued.
Result: Fair Value of $303.75 (UNDERVALUED)
Still, if AI related semiconductor or defense orders slow, or if the market reassesses Materion’s P/E assumptions, this bullish narrative could quickly lose momentum.
Find out about the key risks to this Materion narrative.
Another View: Materion Through The P/E Lens
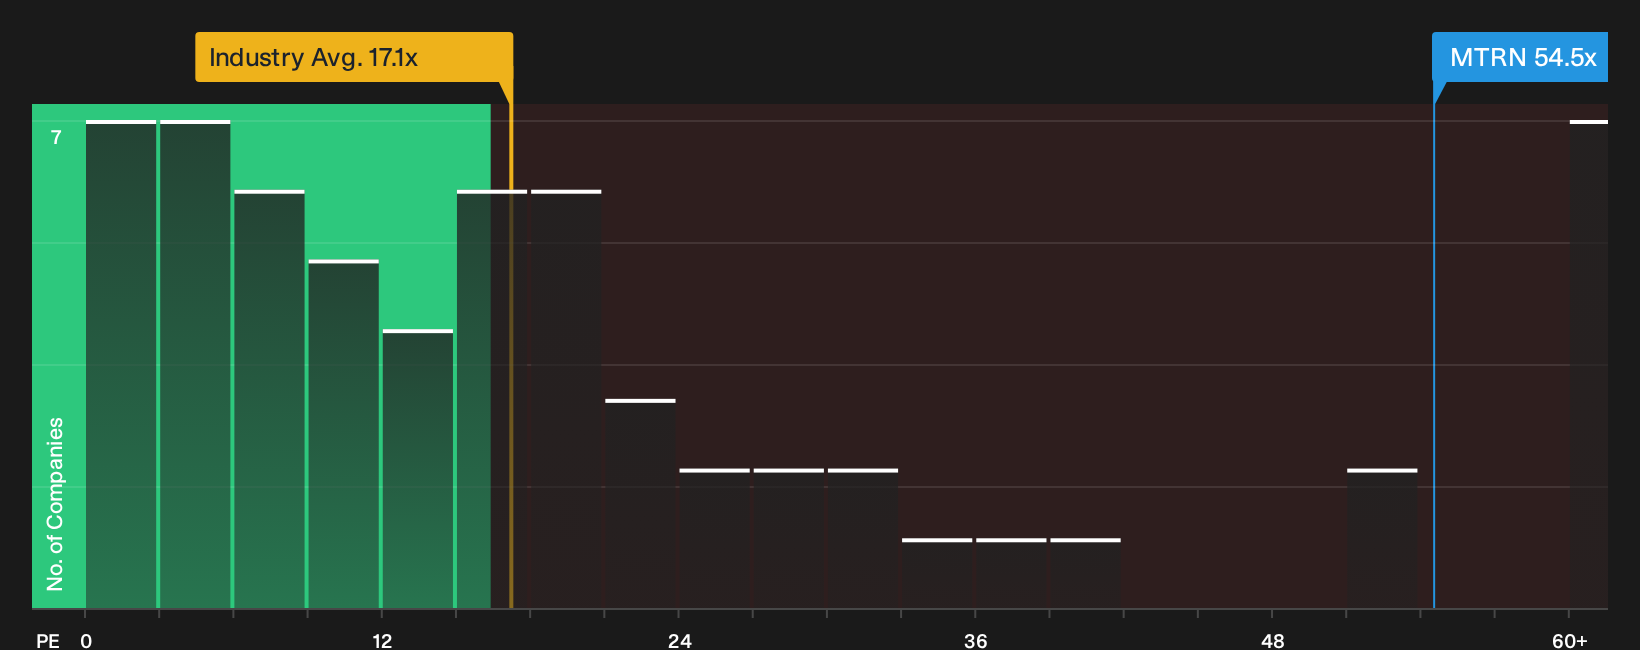
On the flip side of that cash flow based fair value, Materion screens as expensive on simple earnings multiples. The current P/E of 54.5x is more than double peers at 25.5x and sits well above a fair ratio of 31.6x, which points to meaningful valuation risk if sentiment cools.
This leaves a clear question for investors: Is this a quality premium that persists, or a rerating risk if growth and margins track closer to the broader Metals and Mining group? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Confident about Materion after all this, or leaning cautious on the rich P/E and valuation gap story? Act quickly, review the full picture, and weigh both sides through the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Materion?
If Materion has sharpened your focus on quality, do not stop here. Use curated screeners to surface fresh candidates that match your own risk and income goals.
- Target dependable cash generators by reviewing a list of solid balance sheet and fundamentals (24 results) that can shoulder uncertainty without stretching their finances.
- Hunt for mispriced opportunities through a 29 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Dial back risk while staying invested by scanning 30 resilient stocks with low risk scores chosen for resilience when conditions turn choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com