


Marriott International has delivered a powerful share price run in recent years, and that kind of climb naturally raises a simple question for you as an investor. Is today’s valuation still grounded in the hotel group’s earnings profile, or has sentiment moved ahead of the underlying profit stream?
- Over the past 5 years, Marriott International has returned 154.3%, which puts real pressure on buyers to judge whether current earnings can shoulder that kind of share price gain.
- The business leans heavily on how efficiently it converts its global room base and fee-heavy model into consistent profit. This can affect how much of today’s price is being driven by current earnings versus longer term growth expectations.
- The analysts covering Marriott International have run their own numbers. See what analysts think Marriott International's shares could be worth.
The issue now is whether Marriott International’s current share price of US$390.23 is justified by the earnings that support it.
If you want a reference point for Marriott International’s recent share price run, it can help to line it up against other companies screened for 29 high quality undervalued stocks
Is Marriott International Getting Expensive on Earnings?
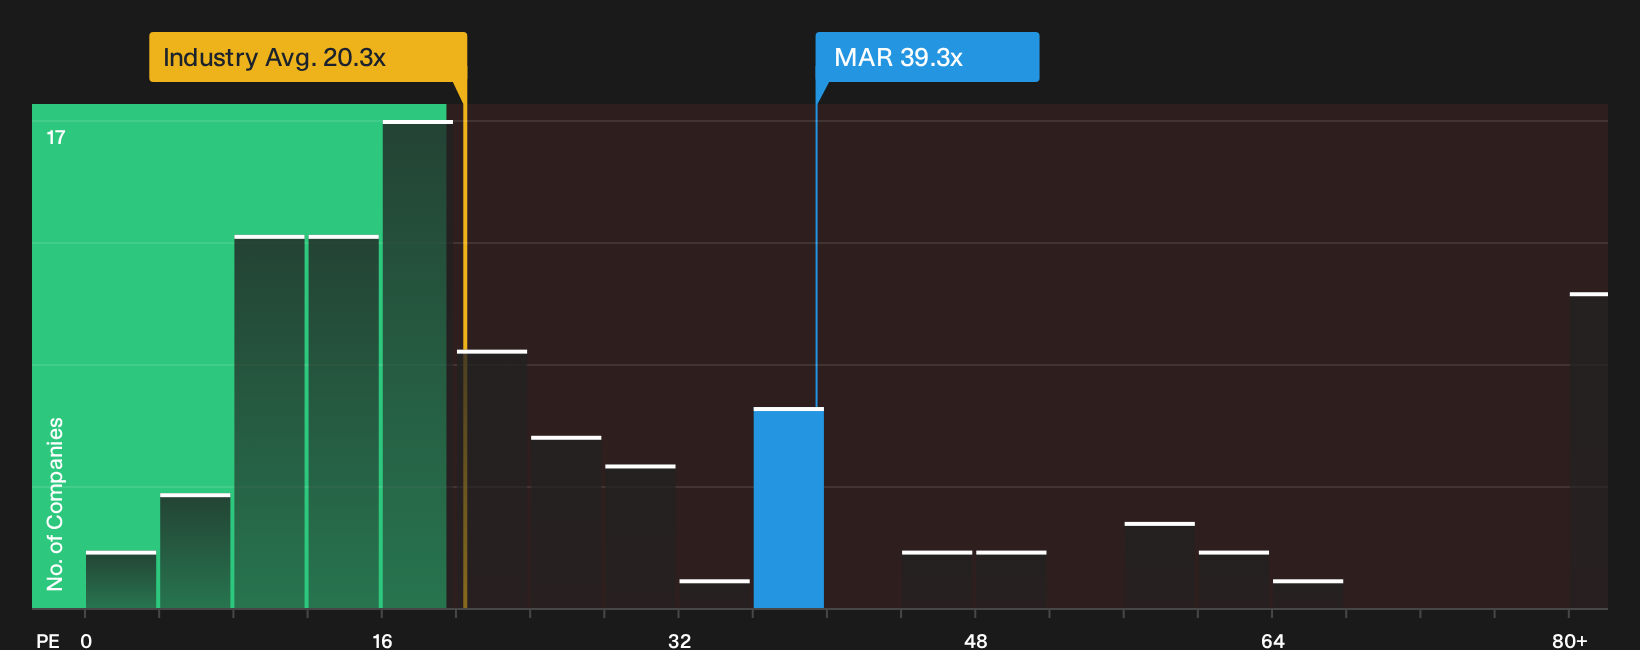
The P/E ratio is a useful measure for Marriott International because earnings remain the key anchor for a fee driven hotel platform. At the current share price, Marriott trades on a P/E of 39.3x, which is higher than the Hospitality industry average of 20.3x and also above the peer group average of 28.9x. This indicates that buyers today are paying a higher price for each dollar of recent earnings than they would across many other listed hotel operators.
The fair multiple implied by the valuation model, which blends factors such as Marriott International’s growth profile, profitability and risk, points to a lower P/E than the one the market is currently assigning. On this basis, the stock screens as overvalued on earnings, so anyone considering the shares needs to assess whether Marriott’s brand strength and fee heavy model justify paying that kind of premium for its profit stream. Explore the numbers behind Marriott International's P/E valuation.
The Marriott International Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this Marriott International valuation puzzle leaves off by explaining which potential paths for growth, profitability and earnings would need to occur for the stock to be worth meaningfully more or meaningfully less than today’s market price. Each Narrative presents its estimate of fair value as a thesis about Marriott International's business that you can follow over time rather than as a one off snapshot, all hosted on Simply Wall St's Community page.
Community views around Marriott International’s upside and downside are sharply split, with one camp seeing meaningful value and the other flagging valuation risk.
Bull case: 31% undervalued
"Marriott International (NASDAQ: MAR) has quietly become one of the most resilient names in global travel, benefiting from asset-light management contracts, global brand recognition, and a loyalty program that keeps travelers returning across continents..."
Discover why this Narrative puts Marriott International at 31% undervalued.
Bear case: 24% overvalued
"Using a forward-looking valuation model, I estimated the fair value of Marriott's stock for FY26 and FY27..."
Explore why this Narrative puts Marriott International at 24% overvalued.
For Marriott International, the share price is only one piece of the puzzle
Current earnings and today’s multiple tell only part of the story, because professional analysts have mapped out where they think Marriott International could be a few years from now and that view can sharpen how you frame risk and opportunity. Explore where analysts expect Marriott International to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com