


Patrick Industries (PATK) heads into its next earnings release with analysts projecting quarterly earnings per share of $0.99, a year-over-year decline that has aligned with cautious sentiment and a Zacks Rank of #5 (Strong Sell).
Recent trading has been choppy for Patrick Industries, with the share price up 2.08% on the day and 7.58% over the past week. However, it remains down 16.96% across 90 days and 34.87% year to date, while the 3 year total shareholder return of 51.81% points to much stronger longer term results. This pattern suggests that current weakness reflects shifting expectations around earnings and perceived risk rather than a simple straight line trend.
Scan beyond Patrick Industries and identify other cyclical manufacturers where sentiment and earnings expectations are already reflected in the price with our curated 29 high quality undervalued stocks.
Bears see a cyclical supplier with earnings under pressure and a cautious Zacks signal. Bulls point to Patrick Industries’ long record and sharp pullback. Which side does the current valuation actually support?
Most Popular Narrative: 29% Undervalued
Patrick Industries screens as materially below the most followed fair value estimate of $100.82 compared with the latest close at $71.93. This puts the current debate squarely on whether cyclical pressure or long term diversification wins out.
Expansion of Patrick Industries into Marine, Powersports and Housing, where recent growth has helped offset weaker RV revenue while RV and Marine wholesale shipments remain more than 20% below 2019 levels, supports the case for a larger and more resilient revenue base as these end markets continue to contribute a greater share of sales and earnings.
See why 2 investors see Patrick Industries as 29% undervalued.
Result: Fair Value of $100.82 (UNDERVALUED)
Still, if RV demand remains softer than Patrick Industries and analysts anticipate, or if working capital keeps absorbing cash, the bullish undervaluation story could easily lose momentum.
Find out about the key risks to this Patrick Industries narrative.
Another View: Patrick Industries On Earnings Multiples
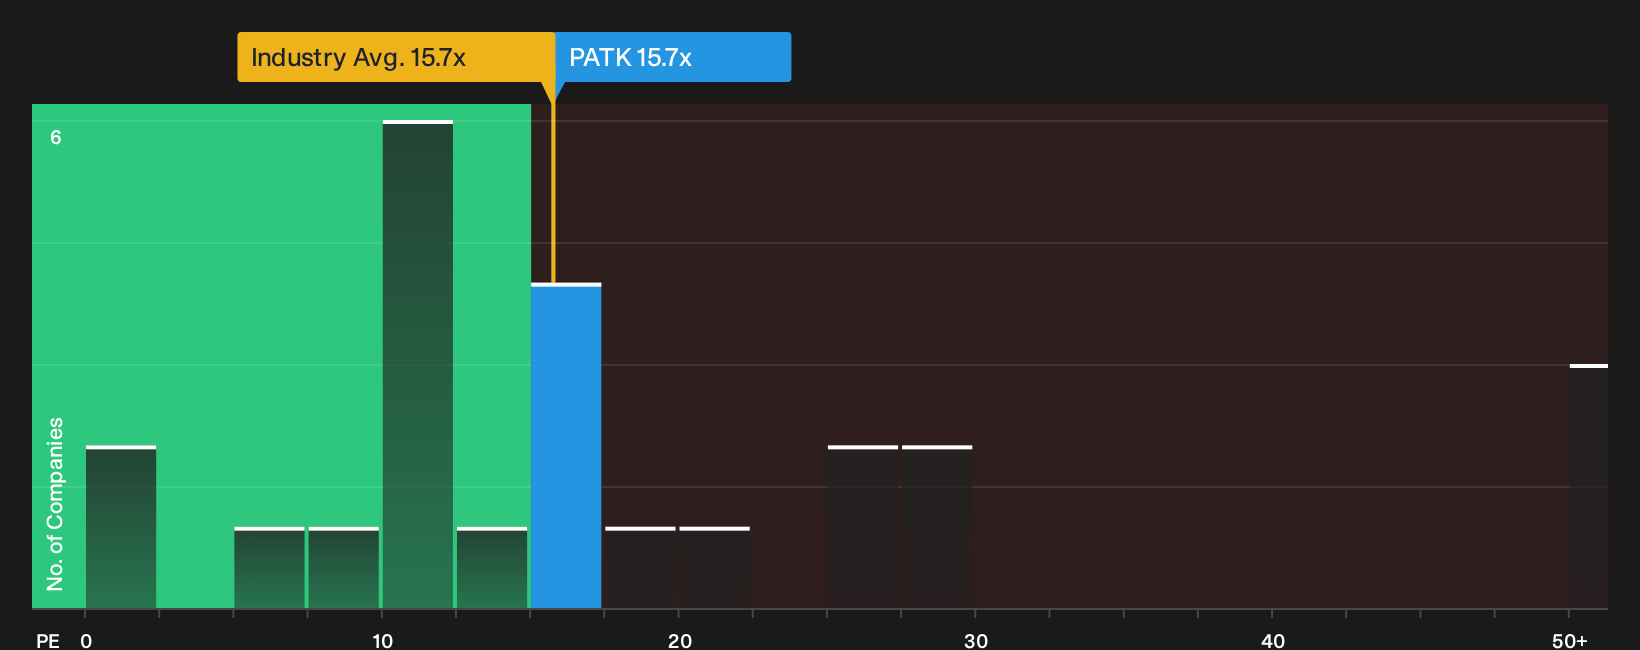
The story looks different once the P/E ratio enters the picture. Patrick Industries trades on 15.7x earnings, slightly above the US Auto Components industry at 15.4x and well above the peer average at 10.8x. The fair ratio sits lower again at 13.1x. The key question is whether this premium pricing reflects quality or increasing valuation risk.
To weigh that question properly, it helps to see how the current price stacks up against earnings across peers and against the fair ratio in more detail, then judge whether paying extra for Patrick Industries feels justified for you. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Patrick Industries is clearly split. This is exactly why it pays to move fast, check the underlying numbers yourself, and test both sides of the story against your own risk tolerance with 3 key rewards and 1 important warning sign.
Looking for more Patrick Industries investment ideas?
Do not stop with Patrick Industries. Use powerful filters to surface fresh opportunities that match your risk comfort, income needs, and quality checklist before the crowd moves on.
- Target payout strength and income resilience by checking companies grouped in the 5 dividend fortresses.
- Spot potential mispricing early by running through the 21 high quality undiscovered gems.
- Prioritise capital protection and steadier compounding with the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com