


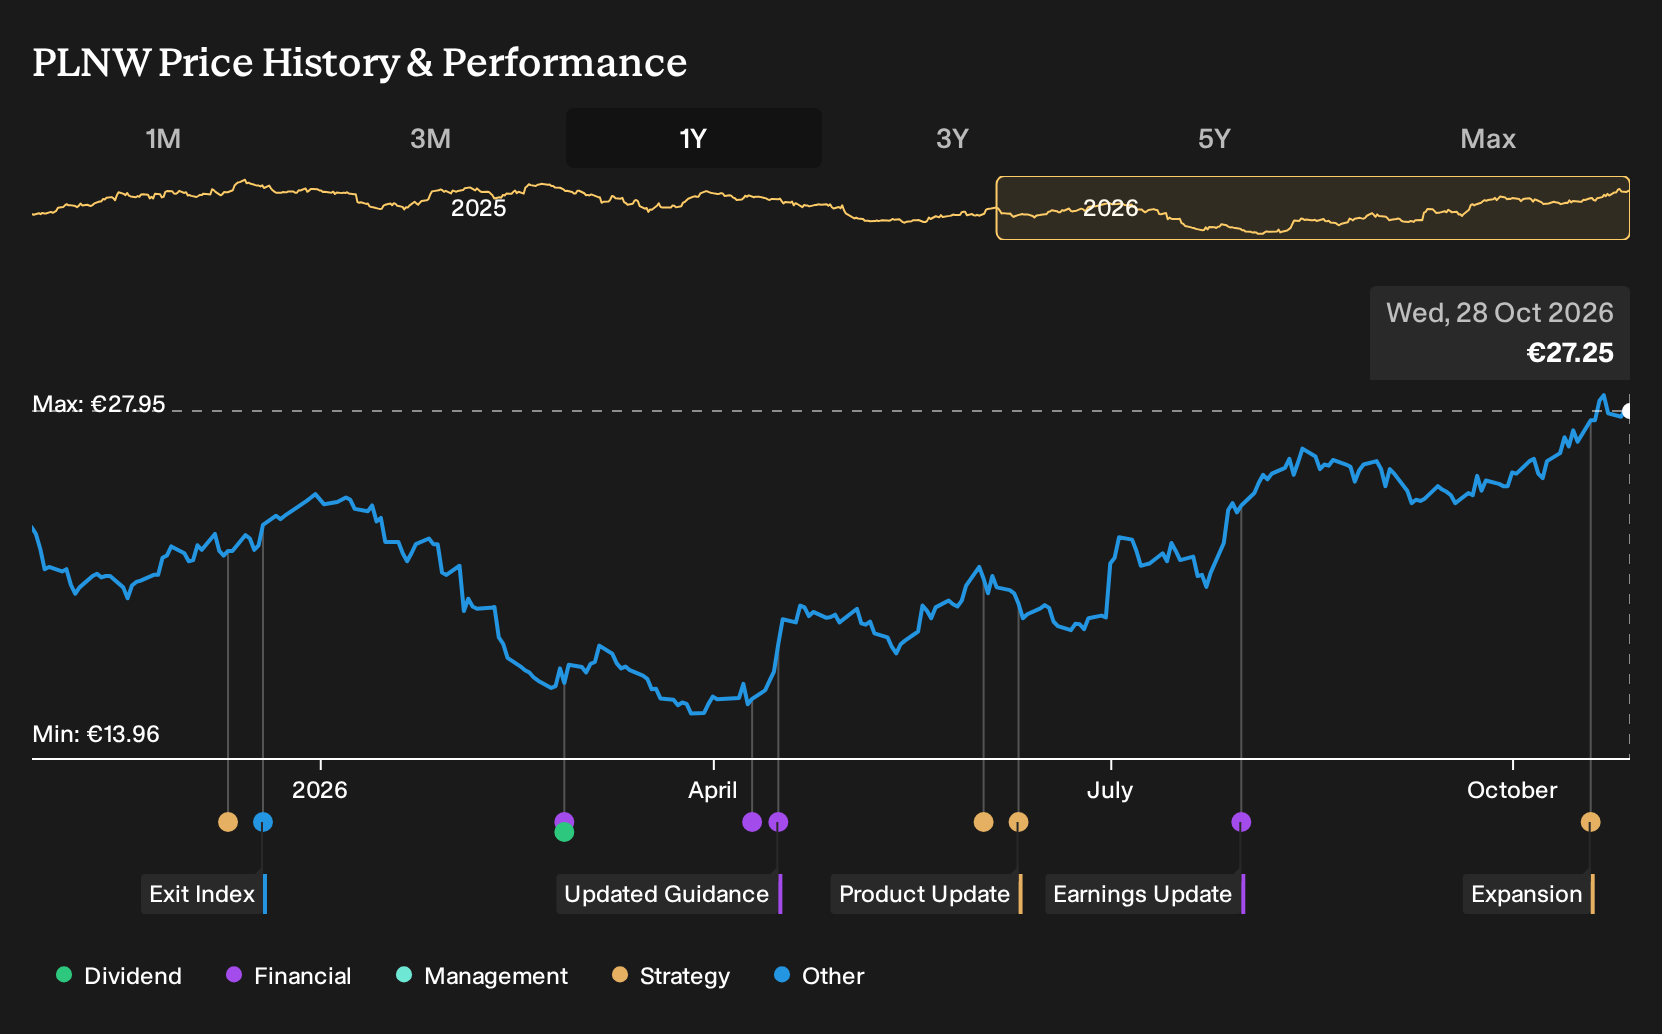
- Planisware SAS reported past third quarter 2026 revenue of €57.4 million compared with €49.6 million a year earlier, and nine month revenue of €163.5 million compared with €145.4 million, alongside an expanded global partner program aimed at building implementation capacity and sector specific expertise.
- The enlarged partner ecosystem, backed by training, accreditation and certification, indicates a push for more scalable delivery while keeping local, high touch support central to how Planisware SAS serves complex transformation projects.
- We will now look at how Planisware's revenue base and partner expansion could influence its longer term investment narrative.
Scan how Planisware SAS compares with other project-focused software players by reviewing a curated 610 high quality undiscovered gems that are also building out partner ecosystems and implementation capacity worldwide.
Planisware SAS Investment Narrative Recap
To be comfortable owning Planisware SAS, you need to believe it can keep turning its project focused software into steady recurring contracts across Europe, North America and APAC while keeping margins resilient as it scales. The latest third quarter and nine month revenue figures give you fresh data points on current commercial traction but do not remove execution risk.
Right now, the key near term swing factor remains how quickly new deals convert from the pipeline into signed contracts, given longer customer decision cycles flagged previously. The biggest threat is that delays in new logos and heavier sales and partner spending, combined with competition and regional soft spots, could squeeze profitability more than expected.
The expansion of Planisware SAS's global partner strategy is particularly relevant here because it speaks directly to how the business is trying to increase implementation capacity and sector depth without doing all delivery in house. More than 25 partners, backed by training, accreditation and certification, gives management another lever to address large and complex transformation programs.
For catalysts, this partner build out interacts closely with the revenue update. If partners can shorten deployment times and support regulated sectors effectively, then cross selling into existing accounts and converting new customers could improve, which matters given the reliance on upsell driven growth. The flip side is quality control. Any inconsistency in partner led projects could slow that thesis and raise churn or cost to serve.
Planisware SAS is framed on consensus numbers as moving toward €320.5 million in revenue and €78.2 million in earnings by 2029, based on analysts assuming 15.4% yearly revenue growth and an earnings increase of about €21.3 million from €56.9 million today.
Uncover why Planisware SAS' fair value indicates that Planisware SAS is consistent with its current price.
Exploring Other Perspectives
One alternate view zooms in on Planisware SAS’s AI heavy platform as the real swing factor rather than sales cycles. The most pessimistic analysts were already pencilling in about €292.8 million of revenue and €76.8 million of earnings by 2029 before this update, and saw a lower 19.5x P/E as more realistic. That is a very different story. Use this new partner and revenue news as a prompt to compare those cautious assumptions with other forecasts and determine which version of the future aligns more closely with your own expectations.
Explore another Planisware SAS fair value estimate, including one that suggests it could be worth just €27.42.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment results often stem from independent thinking, so trust your own analysis.
- A great starting point for your Planisware SAS research is our analysis highlighting 3 key rewards that could be relevant to your investment decision.
- See our latest analysis for Planisware SAS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Planisware SAS' overall financial profile at a glance.
Looking for more investment ideas beyond Planisware SAS?
Once you have a view on Planisware SAS, it can help to set it beside a wider watchlist so you can judge risk, quality and income potential against other options that fit different roles in a portfolio.
- For investors who care most about resilience, compare Planisware SAS with a 223 resilient stocks with low risk scores that screens for businesses with more defensive profiles.
- If your priority is finding stronger balance sheets, weigh Planisware SAS against a list of solid balance sheet and fundamentals (207 results) that surfaces companies with sturdier financial footing and healthier fundamentals.
- For those hunting for income ideas, line up Planisware SAS alongside a 224 dividend fortresses that focuses on higher yielding payers that still clear basic quality checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com