


Freshworks (FRSH) just reached FedRAMP "In-Process" status for its Freshservice platform, putting a spotlight on public sector opportunity, while revenue growth, robust gross margins, and free cash flow shape how investors assess the stock.
FedRAMP momentum is landing at a time when Freshworks shares have logged a 30-day share price return of 18.8% and a 90-day gain of 28.3%, while the 1-year total shareholder return of 31.9% contrasts with a weaker 3-year and 5-year record.
Compare Freshworks' FedRAMP-driven momentum with other software stocks showing similar traction by scanning our hand picked 29 high quality undervalued stocks.
Freshworks now sits at the crossroads of stronger fundamentals and a sharp sentiment swing. Are you paying for hype around FedRAMP and recent gains, or for the underlying cash generation and revenue base?
Most Popular Narrative: 4% Overvalued
Freshworks last closed at $14.90, while the most followed narrative anchors fair value closer to $14.38. The gap is narrow, but the burden of proof now leans on future execution rather than a cheap entry point.
The rapid adoption of AI-powered features (such as Copilot and Agentic AI) across both new and existing Freshworks customers is outpacing internal expectations, with over 5,000 paying customers and high attach rates in large deals. As AI monetization expands and early-access Agentic products move to paid solutions, management expects this to materially boost revenue growth and average selling prices in 2026 and beyond.
See why 33 investors see Freshworks as 4% overvalued.
Result: Fair Value of $14.38 (OVERVALUED)
Still, the bullish AI and Employee Experience story around Freshworks can be derailed if larger rivals squeeze pricing power or if AI monetization remains narrower than analysts expect.
Find out about the key risks to this Freshworks narrative.
Another Look At Freshworks Using Earnings Multiples
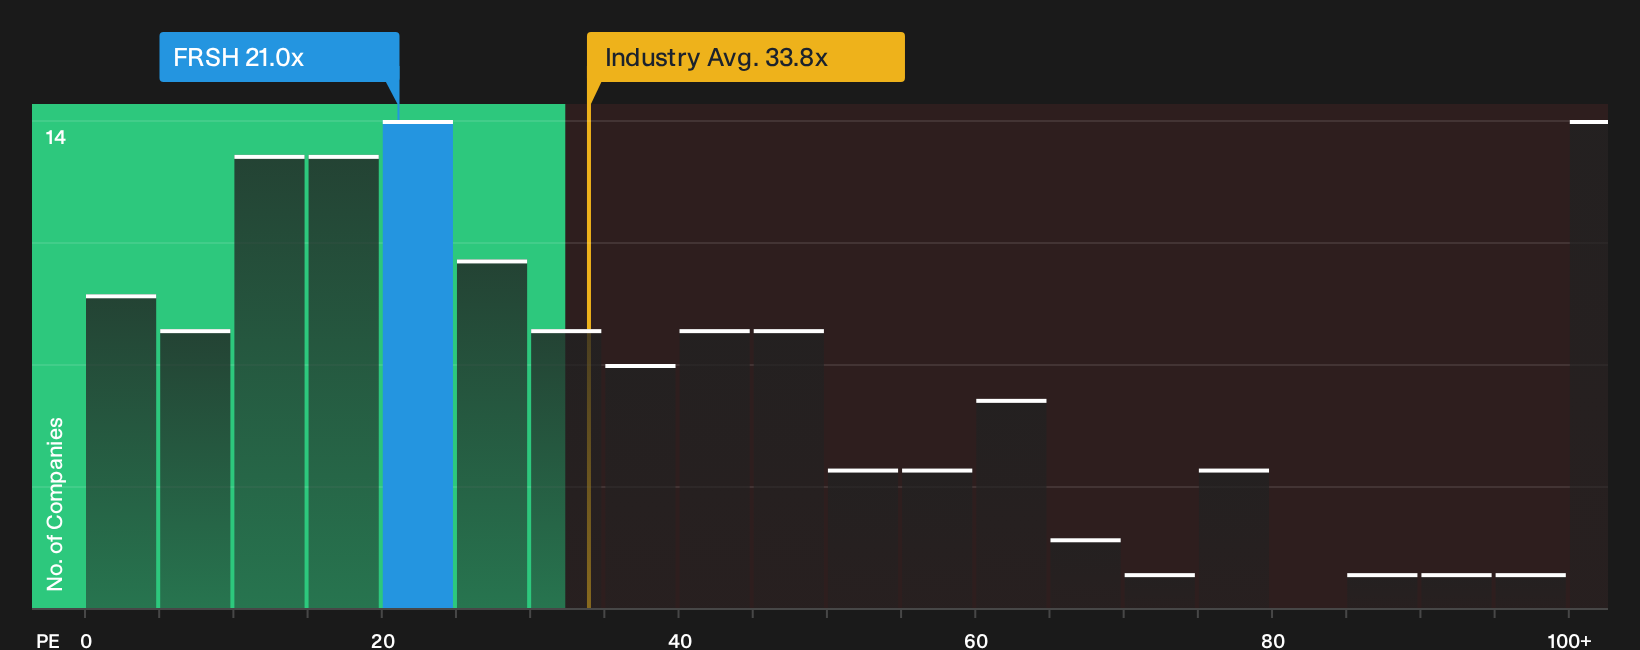
The initial narrative framed Freshworks as roughly 4% over fair value at $14.90 based on analyst targets. A different lens tells a softer story. On a P/E of 21x, the stock trades below the US Software industry at 32.7x and peers at 64.3x, while the fair ratio sits at 18.5x.
This combination of a discount to the sector, a premium to the fair ratio, and earnings forecast to decline over the next 3 years raises a practical question. Is the market cautiously pricing in those shrinking profits, or underappreciating a newly profitable software platform with a 20.7% return on equity?
To pressure test how much room this valuation gap really leaves, look at what the numbers imply about future re rating and compression in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Freshworks is mixed, with valuation questions sitting beside real operational progress, so move quickly, review the full dataset, and weigh both the upside and downside using 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Freshworks?
If you only stop at Freshworks, you risk missing other opportunities that match your goals, risk comfort, and time horizon across very different business profiles.
- Target potential mispricing by scanning companies that combine quality fundamentals with valuation support using the 29 high quality undervalued stocks.
- Prioritize resilience and balance sheet strength by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you stress test ideas against tougher conditions.
- Spot lesser known opportunities by tracking a 21 high quality undiscovered gems before wider attention potentially closes the valuation gap.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com