


Fresh debate around Elkem (OB:ELK) has been triggered by renewed focus on whether its share price captures the company’s earnings power, given its multi-year total returns and a P/E ratio above sector peers.
At a latest share price of NOK31.28, Elkem has seen a 2.49% 1-day share price return but is down 5.10% over 30 days, while a 16.01% 1-year total shareholder return and 82.47% over three years point to longer term momentum that has kept valuation debates alive.
Compare Elkem’s valuation debate with other potential underpriced opportunities by scanning our hand picked list of 195 high quality undervalued stocks.
After a three year total return above 80% and a P/E ratio that already tops sector peers, the real question now is whether Elkem still offers meaningful upside or if most of the rerating is already behind it.
Most Popular Narrative: 20% Undervalued
On the most followed valuation narrative, Elkem’s fair value of NOK39 sits comfortably above the last close of NOK31.28. This puts the current P/E debate into a broader earnings and cash flow story rather than just a momentum discussion.
Initiatives to supply the green transition, such as R&D in carbon capture, storage, and using biogenic materials, could enhance long-term revenue and net margins by meeting rising demand for sustainable products.
Increased demand from sectors like automotive (driven by EV growth) and defense infrastructure projects (notably in Europe) may lead to higher sales volumes for Elkem's materials, positively impacting revenue.
See why 20 investors see Elkem as 20% undervalued.
Result: Fair Value of NOK39 (UNDERVALUED)
Still, weak demand in China and the EU, along with ongoing trade disputes, could pressure Elkem’s pricing power and keep the Silicon Products division under earnings strain.
Find out about the key risks to this Elkem narrative.
Another View on Elkem’s Valuation
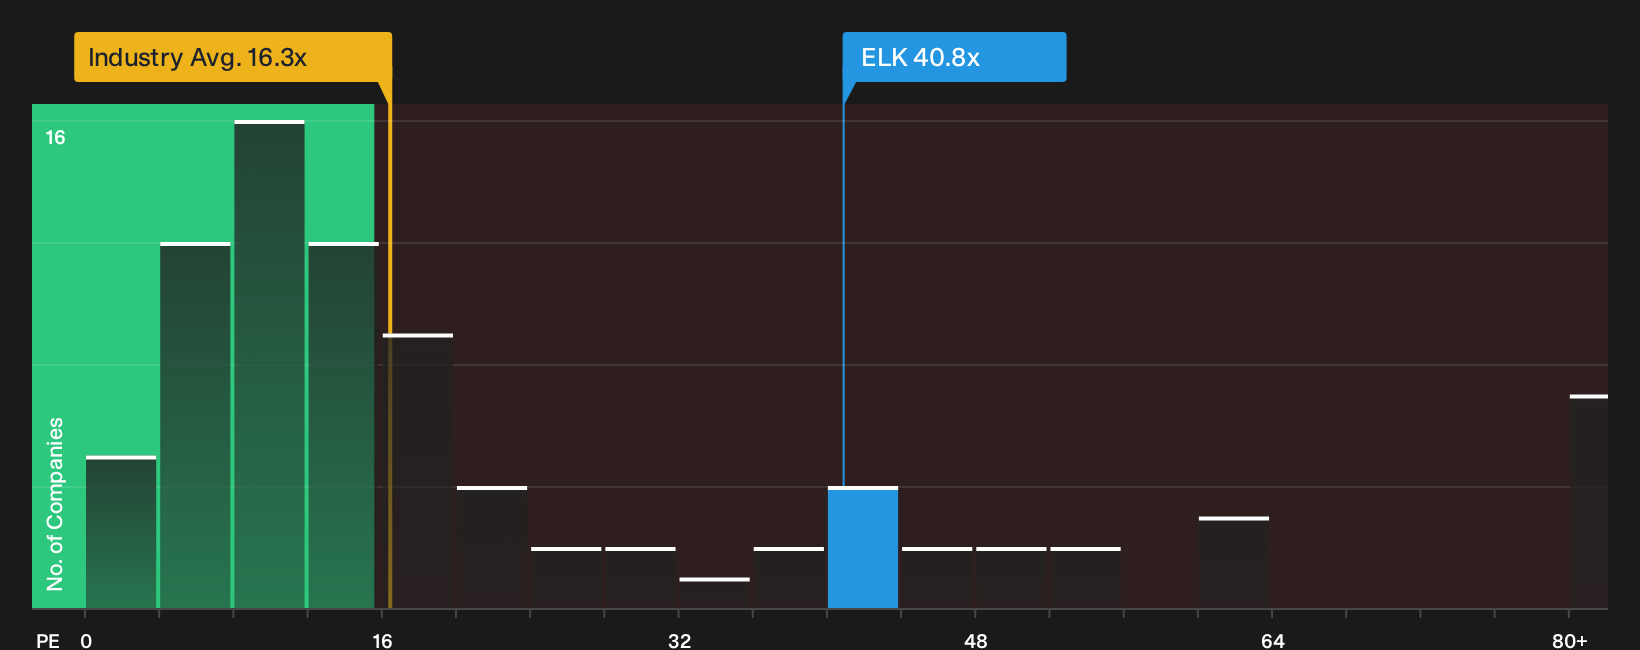
Multiples tell a tougher story. Elkem trades on a P/E of 40.8x, while the European Chemicals group sits at 16.3x and its own fair ratio is estimated at 64.7x. The share looks pricey versus peers yet below that fair ratio. Is this a rerating risk or a catch up opportunity?
To see how this price tag stacks up against earnings power, have a look at our valuation breakdown, including the fair ratio and peer comparison, in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted about whether Elkem’s current price reflects more risk or more opportunity? Act while sentiment is still split and weigh both sides through 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Elkem?
If Elkem has you thinking harder about valuation and risk, do not stop here. Fresh opportunities often emerge where fewer investors are paying attention.
- Target steadier compounding by scanning companies with resilient balance sheets and dependable fundamentals through our list of solid balance sheet and fundamentals (207 results).
- Hunt for mispriced potential by reviewing our 610 high quality undiscovered gems and see which businesses the crowd has not yet focused on.
- Strengthen your downside protection by filtering for 223 resilient stocks with low risk scores before market narratives move ahead without you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com