


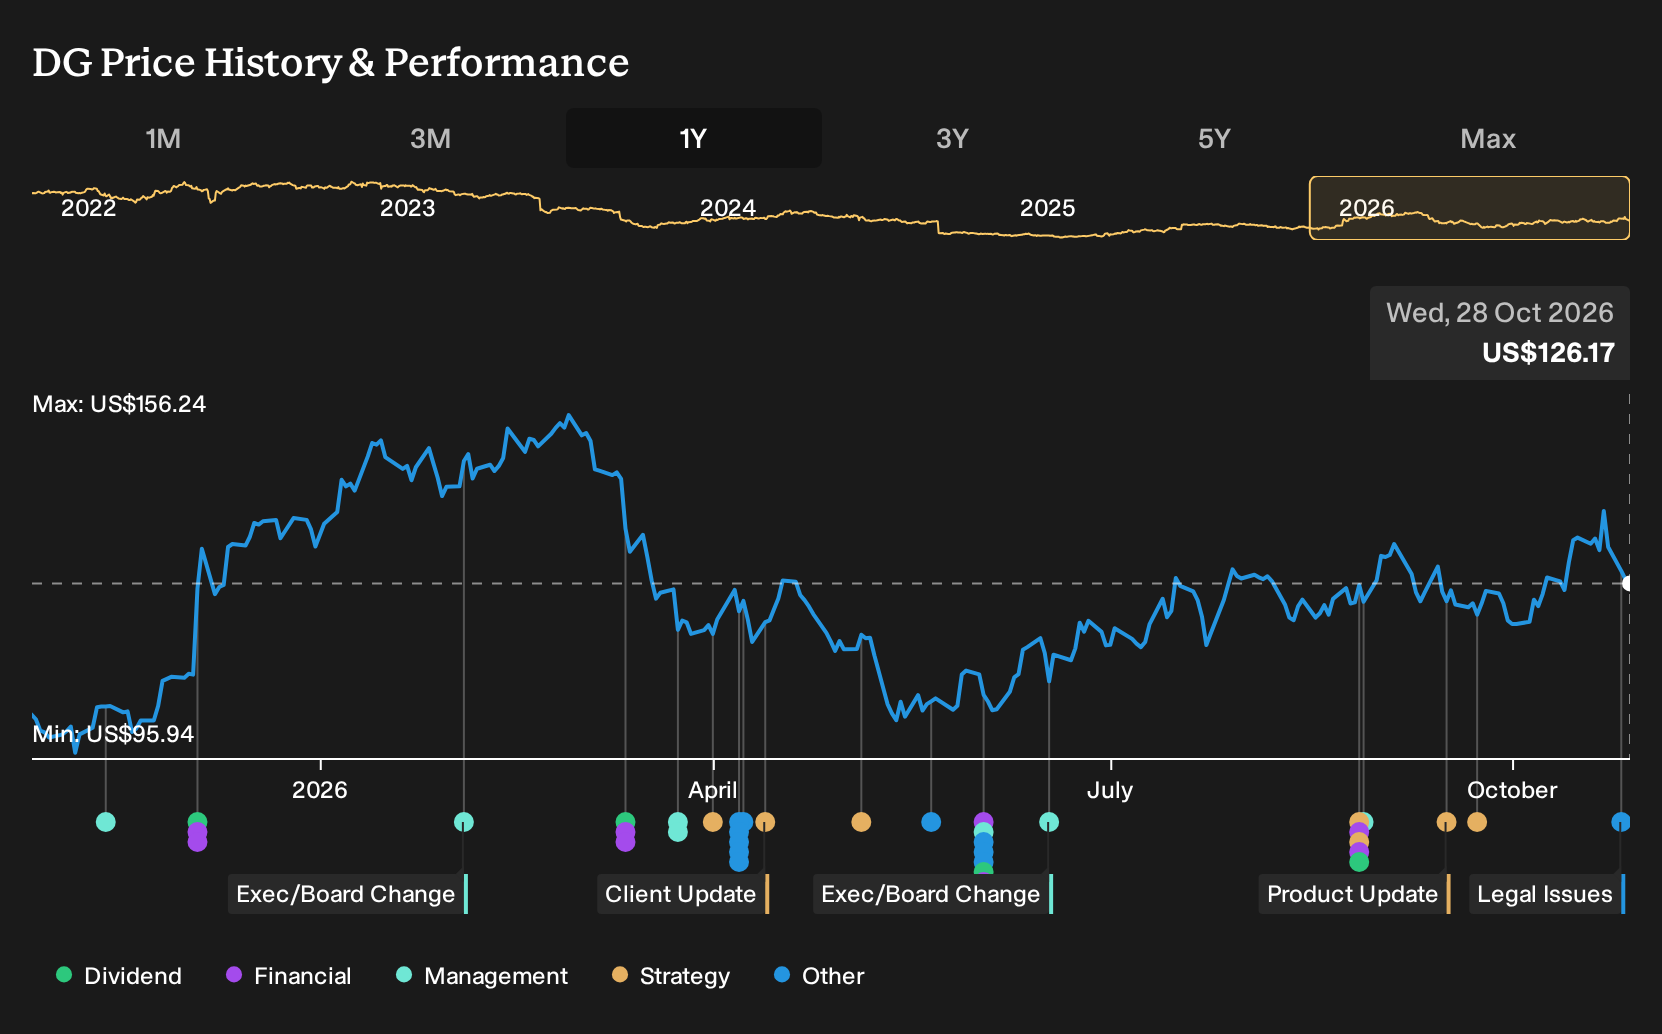
If you only skimmed the headlines about slowing consumers, tariff worries, and even pricing lawsuits, Dollar General might not have looked like a comfortable place to park cash. For Dollar General shareholders, the return over the past year was 26.9%, including dividends. If you had been weighing those bullish expansion plans against warnings about over-saturation and pressured shoppers back on 2025-10-27, what exactly in the record could have justified taking that risk?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Dollar General. Zero in on 29 high quality undervalued stocks for companies trading below our estimates.
The Two Dollar General Stories Investors Had To Price In
The shares cost US$103 at the start of the period, so any argument about Dollar General needed to explain why that upfront outlay made sense.
The bullish narrative pinned fair value at US$120 and relied on revenue growing 4.1% a year with profit margins reaching 3.6%, supported by store expansion, digital delivery, and supply chain investments.
The bearish view set fair value at US$80 and focused on pressures such as 96 planned store closures and customer traffic that had declined 1.1% in a recent quarter.
What The Results Changed For The Dollar General Story
Dollar General’s reported numbers did the real work on the thesis. Revenue moved from US$10,727.737m in Q2 2026 to US$11,290.38m in Q2 2027, while net income rose from US$411.426m to US$550.315m and net margin shifted from 3.8% to 4.9%. That combination fit the more optimistic case that assumed higher profitability.
The useful takeaway travels well. When you see a bullish story built on better margins, check whether net income and the reported net margin both move in the direction and rough scale that thesis implied, rather than watching the share price first.
What Dollar General's Price Already Assumes
Dollar General now trades at US$127 after a 26.9% gain over the past year. The selected Narrative’s Fair Value sits below that level, so it treats today’s quote as baking in a demanding set of operating assumptions.
The focus is less on traffic or sales headlines and more on how much margin improvement can realistically be sustained. Anyone paying US$127 is effectively assuming remodels, digital initiatives, and efficiency work can protect or lift profitability. The key question is how the risks around competition and cost inflation weigh on that bet.
"The numbers imply that Dollar General’s share price already prices in sustained same store sales growth, continued margin expansion, and successful execution of remodel, digital, and media initiatives that may leave limited room for disappointment."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Where Dollar General’s Playbook Echoes
Dollar General leans hard on low prices and convenience. You can look one step away.
Another retailer is wrestling with a similar challenge. How do you keep value-focused shoppers loyal as food, health, and online habits shift?
This business is investing in digital ordering, loyalty tools, and fresher store brands. The goal is stickier customers and margins that hold up as tastes move.
It is also tightening warehouse operations and refreshing formats to get more from mature markets.
If that balance holds, the strategy could quietly matter well beyond traditional grocery aisles.
That argument has a Narrative and a number behind it. → See the company one Narrative values 16% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com