


China State Construction International Holdings (SEHK:3311) just renewed a three year master engagement agreement with China Overseas Grand Oceans Group, keeping its subsidiaries in the running for capped Mainland construction tenders.
For context, China State Construction International Holdings trades at HK$8.525, with the share price down 7.84% year to date and the 1-year total shareholder return almost flat at a decline of 0.72%, although longer term total shareholder returns of 25.81% over three years and 55.10% over five years point to momentum that has been built over time rather than in the past few months.
Scan 195 high quality undervalued stocks, which is hand picked for construction and infrastructure exposure, if you want more ideas alongside China State Construction International Holdings after this renewed Mainland tender pipeline.
Bulls see the renewed Mainland tender access and steady revenue and net income growth as support for China State Construction International Holdings. Bears point to the muted recent share price. Which story does the valuation back up next?
Preferred P/E of 5x for China State Construction International Holdings: Is it justified?
On a simple earnings lens, China State Construction International Holdings trades on a P/E of 5x while peers sit nearer 7x and the wider Hong Kong Construction group around 12.2x. This points to a clear valuation gap at the current HK$8.525 share price.
The P/E ratio compares what you pay per share to the profit that each share is entitled to, so a lower P/E can suggest the market is assigning a cheaper price tag to those earnings. For a builder of long term projects across Hong Kong, Mainland China and Macau, this kind of yardstick is often used because earnings tend to be a core focus for investors looking at contractors and concession operators.
China State Construction International Holdings also screens as good value against an estimated fair P/E of 7.9x, implying the current 5x multiple is well below a level the market could potentially move toward if sentiment and assumptions align. When the stock trades at a discount to its own fair ratio and to both direct peers and the sector average, the figures suggest the market is pricing in a more cautious outlook than these metrics on their own indicate.
Explore the SWS fair ratio for China State Construction International Holdings.
Result: Price-to-Earnings of 5x (UNDERVALUED)
Still, the share price drift this year and reliance on construction demand in Hong Kong and Mainland China could both affect how quickly the China State Construction International Holdings valuation gap closes.
Find out about the key risks to this China State Construction International Holdings narrative.
Another view on China State Construction International Holdings: cash flows vs earnings
Price-to-earnings paints China State Construction International Holdings as inexpensive, and the SWS DCF model also points to value. At HK$8.53 against an estimated future cash flow value of HK$11.36, the stock screens as trading at a discount. Does that cash flow lens give you more conviction or more questions?
Look into how the SWS DCF model arrives at its fair value.
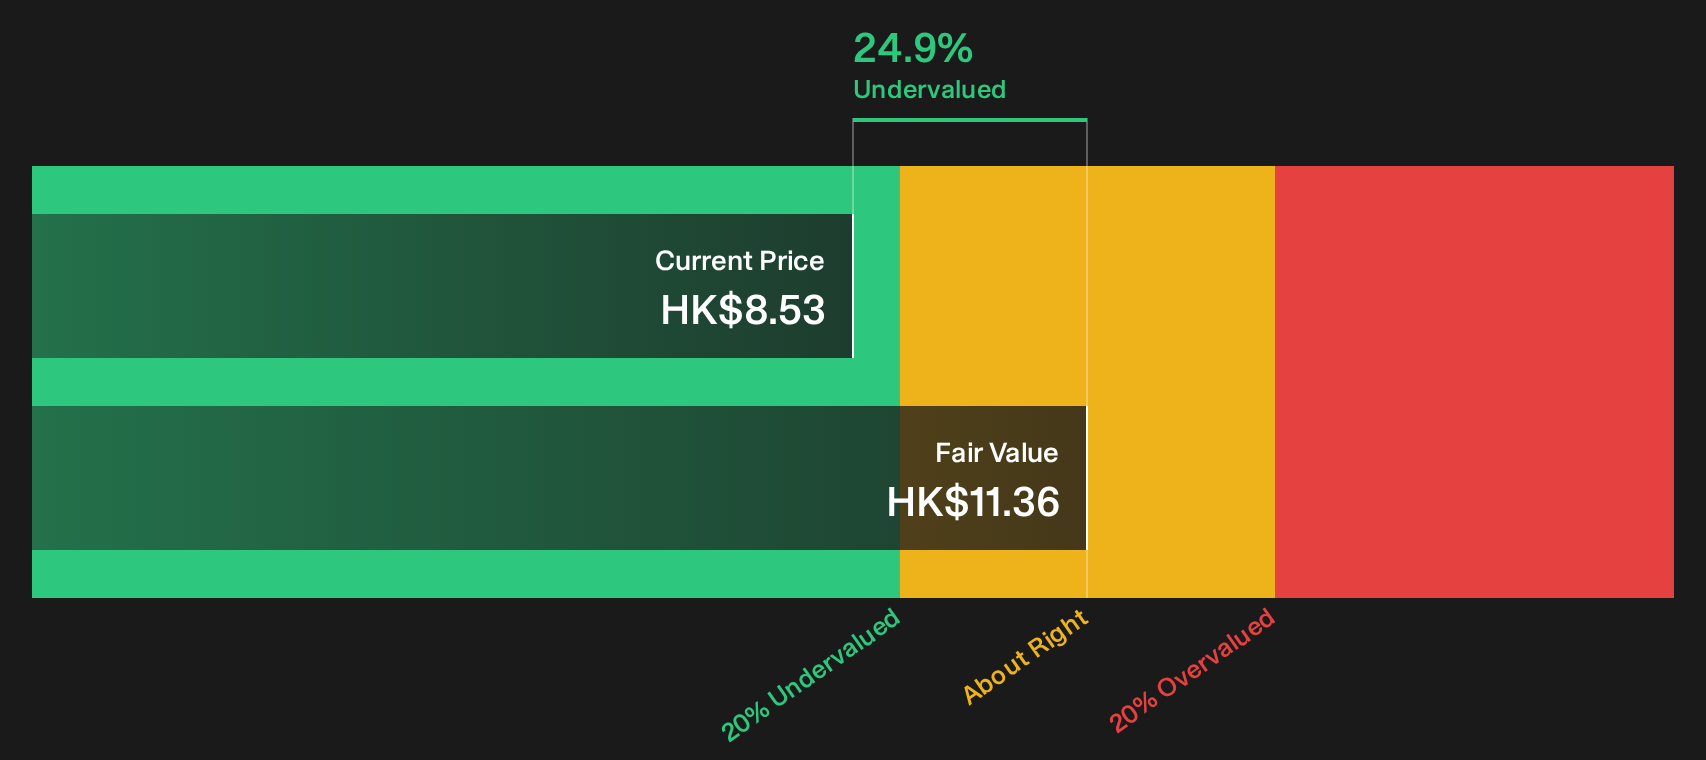
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China State Construction International Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around China State Construction International Holdings can be confusing, so use the data to move quickly and decide where you stand by weighing its 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond China State Construction International Holdings?
Do not stop with one contractor when the wider market offers very different risk and return profiles. Use targeted screeners to quickly build a shortlist that fits your goals.
- Target stronger downside protection by focusing on companies that pass a resilience check using the 223 resilient stocks with low risk scores.
- Search for quality at a discount by filtering for companies that combine fundamentals with appealing entry prices through the 610 high quality undiscovered gems.
- Strengthen your core holdings by focusing on financially sound businesses using the list of solid balance sheet and fundamentals (207 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com