


Otis Worldwide just reported Q3 2026 earnings, and the stock closed down 1.8% at US$72.87. The headline story is not an earnings miss or a revenue scare. It is a margin squeeze in the capital heavy elevator and escalator business that is testing investor nerves.
Q3 net income of US$414 million on US$3.9b in revenue left adjusted profit essentially flat even as organic sales improved, with New Equipment margins particularly thin. Traders reacted quickly to the softer profitability. The fuller picture of service strength, modernization momentum and balance sheet strain will matter far more than a single day’s price move.
Love the recurring service strength at Otis Worldwide but worried about margin pressure in capital heavy projects? Compare it with companies that pair resilient cash generation and sturdier profitability in our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$3,914 million vs. US$3,690 million (up 6.1%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$414 million vs. US$374 million (up 10.7%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.09 vs. US$0.96 (up 13.6%)
- Trailing 12-Month Net Profit Margin (Q3 2026 vs. Q3 2025): 10.3% vs. 9.4% (margin improvement of 0.9 percentage points)
Earnings tell you what Otis Worldwide reported this quarter, but cash flows tell you what the business is really throwing off after the accounting noise. Investors who care about what they are paying for often start there.
On Otis Worldwide's recent cash generation alone, the valuation story could look very different, and on that basis the stock could be a solid 24% undervalued.
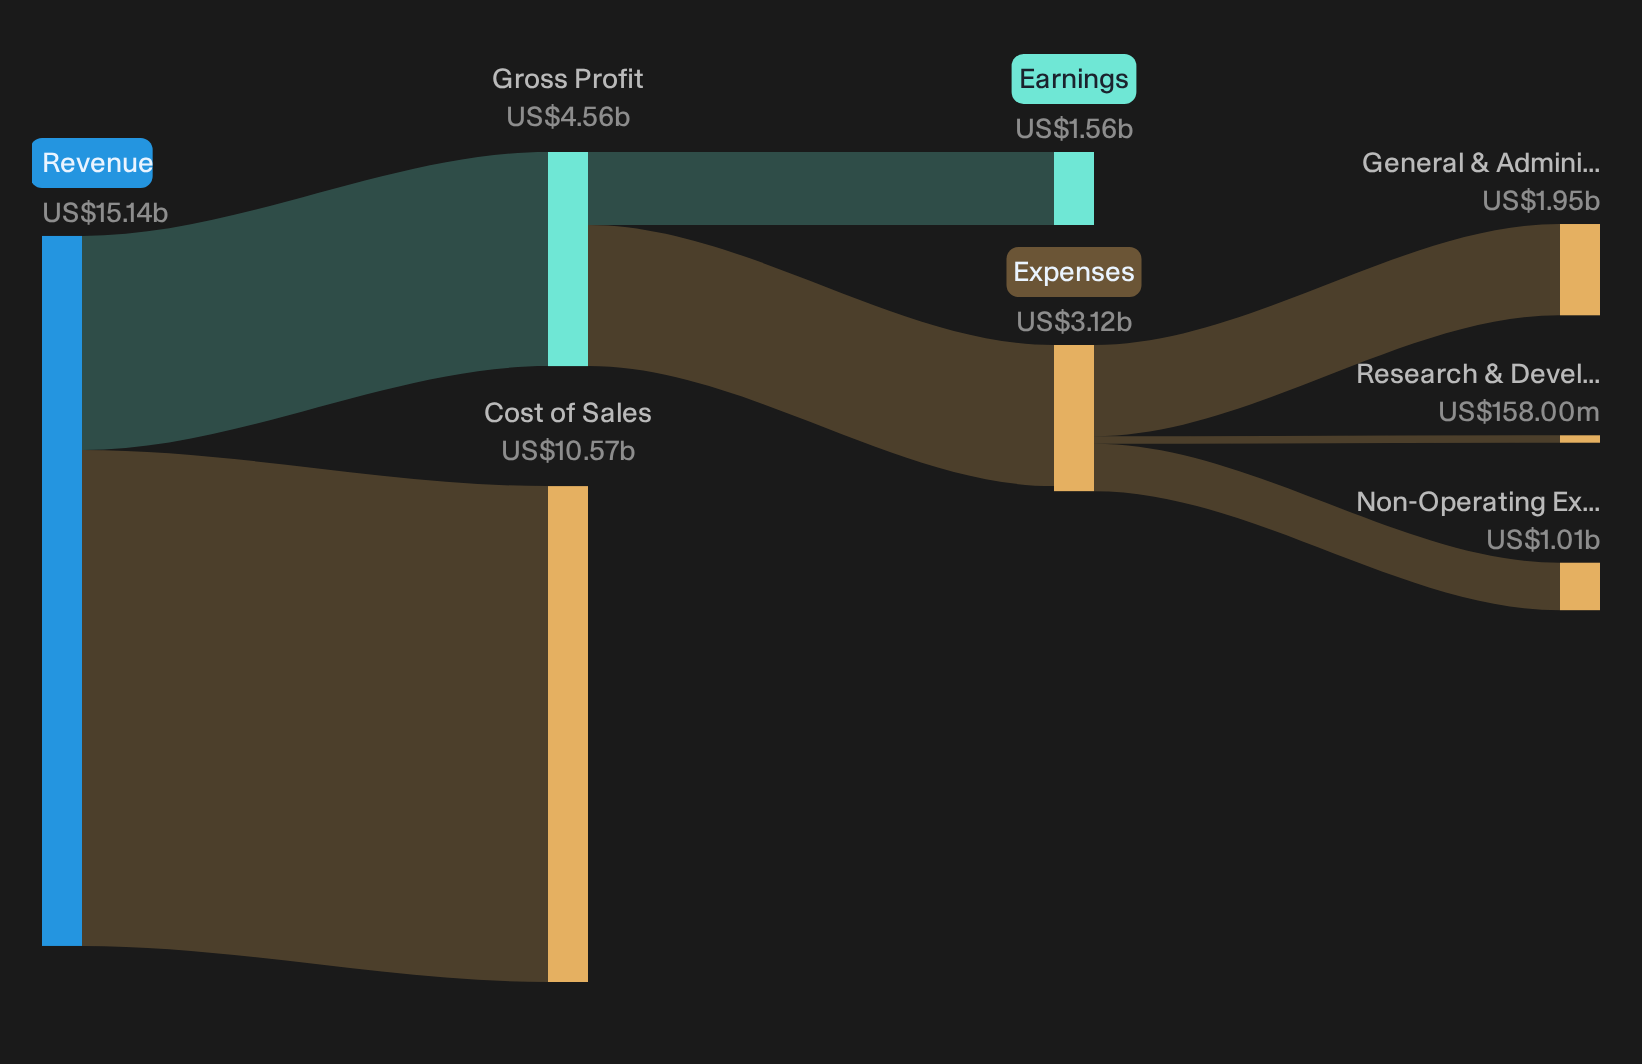
Otis bullish modernisation story faces real tests
The optimistic view hangs on turning a bigger, smarter service machine into fatter profits, not just higher sales.
"The main thing that has to go right is that Otis Worldwide converts its larger, increasingly connected service portfolio and new AI enabled operating model into higher service margins while stabilizing retention."
Q3 gives partial credit. Service sales grew faster than the group, Modernization sales rose 20%, and Service operating margin improved 100 bps sequentially to 24.2%. At the same time, margin is still lower than a year ago and maintenance churn is described as a drag, so the service flywheel is working but not yet cleanly.
Margin squeeze keeps Otis bearish worries alive
The concern is that cost friction and execution issues soak up the benefit from Otis Worldwide’s backlog and digital tools.
"Service operating margin declined 170 basis points year over year to 23.2% in Q2 2026 and total adjusted operating margin fell 180 basis points to 15.2%. At the same time, Otis Worldwide is absorbing roughly US$50 million of unexpected productivity and cost headwinds, which together could offset pricing and volume benefits and hold back net margins and earnings."
Q3 shows some relief but not a clean break. Adjusted operating profit and EPS were flat despite 6% sales growth, and New Equipment margin at 3.2% stayed thin. Guidance for adjusted operating profit still ranges from down modestly to flat in 2026, so efficiency programs are only slowly catching up to earlier headwinds.
One Narrative disagrees with today's price. → See where this Narrative says Otis Worldwide should trade.
Hunt Quiet Disconnects In Plain Sight
Otis Worldwide just showed how a modest margin story can shape sentiment more than headlines. The real opportunity is finding stocks that could be undervalued before the market closes that gap.
- Company 1 - 43% below our estimate - convert a record backlog of data center and modular projects into higher utilization on complex mechanical and electrical work.
- Company 2 - 15% below our estimate - ride rising data center demand across communications and infrastructure contracts while managing higher working capital needs and a dominant controlling shareholder.
- Company 3 - 25% below our estimate - build out manufacturing and access for obesity and cardiometabolic therapies as newer oncology and neuroscience treatments develop into additional revenue sources.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com