


- Magellan Aerospace announced a Memorandum of Understanding with Saab to explore local production of advanced aerostructures and related assemblies in Canada, contingent on the Gripen being selected for the Royal Canadian Air Force’s future fighter program.
- The agreement highlights potential Canadian work on complex structural units, composite wing skins and external fuel tank activities. These initiatives could reshape Magellan Aerospace’s long term defence manufacturing mix if the procurement outcome supports these packages.
- We will examine how Magellan Aerospace’s investment narrative could change if local Gripen aerostructure work results in a meaningful expansion of its defence manufacturing base.
See how this Magellan Aerospace update fits into a broader defence build out by reviewing a hand picked group of 42 power grid technology and infrastructure stocks that feed into long term military and aerospace demand.
Magellan Aerospace Investment Narrative Recap
To own Magellan Aerospace, you need to be comfortable with a manufacturing story that is still tightening its operations while leaning into long dated aerospace and defence programs. The short term hinge is execution on existing contracts and capital projects so that earnings and margins keep tracking toward expectations without stretching the balance sheet.
The biggest near term risk is that higher working capital, safety stock and the Chapter 11 process at Magellan Aerospace, Middletown, Inc. absorb more cash and attention than planned. The Saab Memorandum of Understanding adds optional upside but, until a Gripen decision is made, it does not change those core near term drivers.
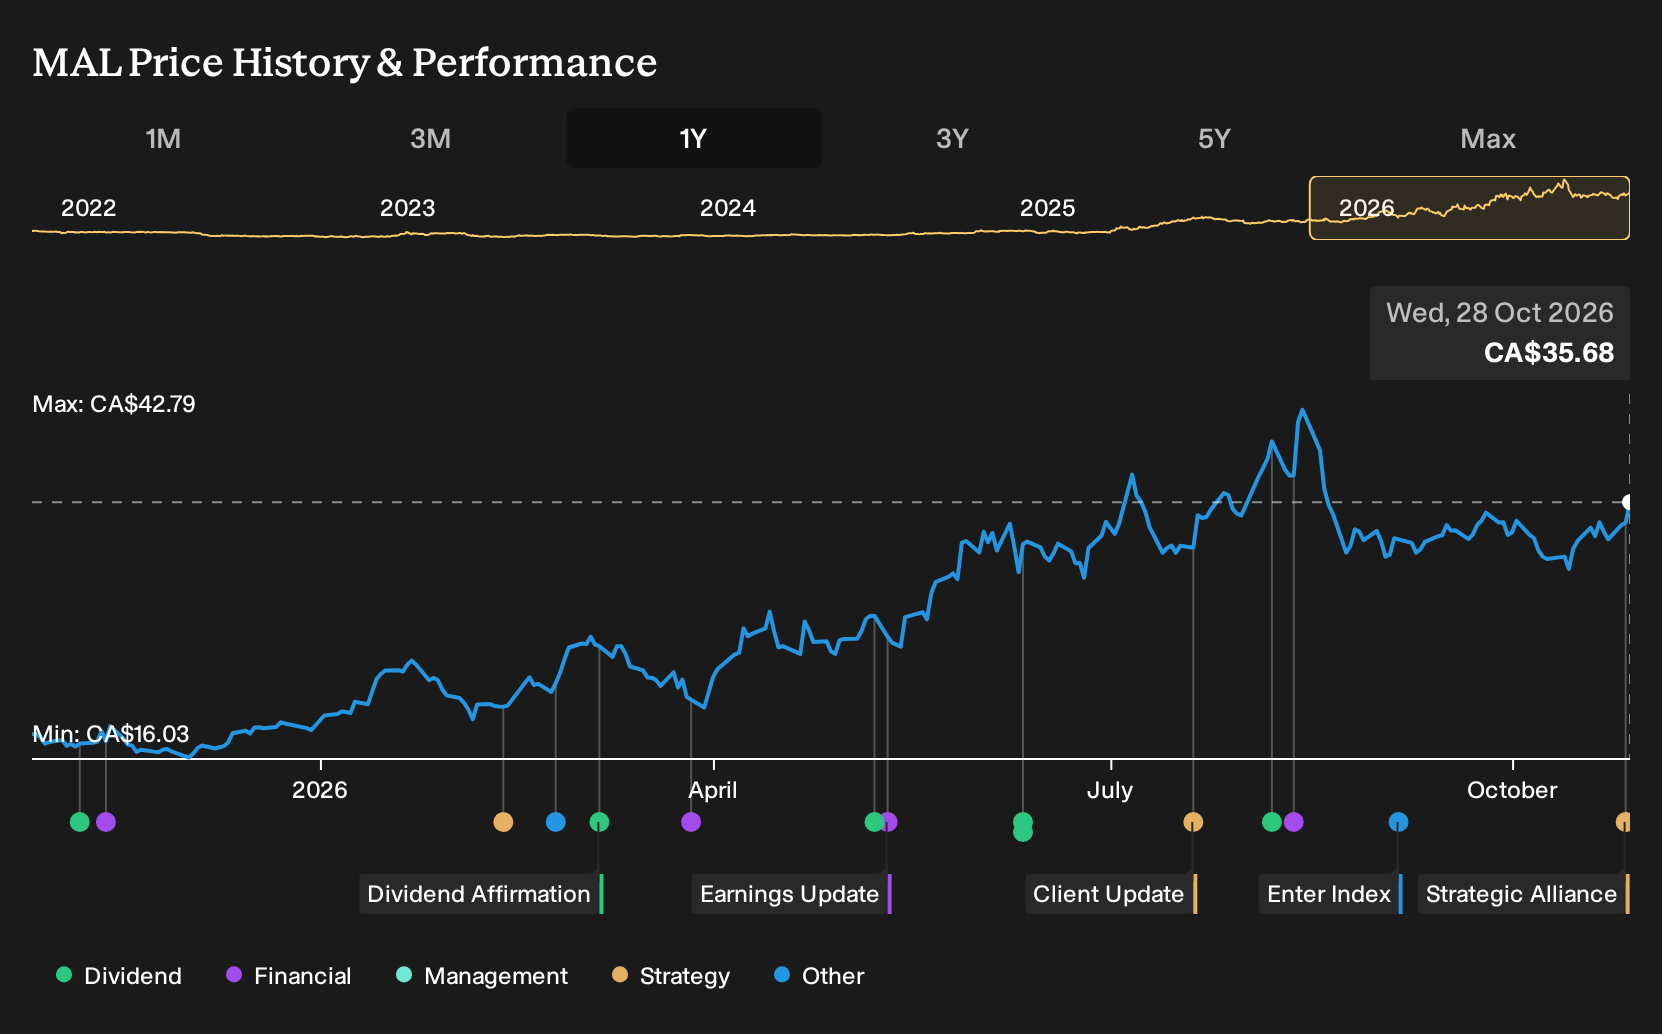
With no other fresh announcements around the October 2026 news, the Saab Memorandum of Understanding is the operational update that matters most right now. It directly links Magellan Aerospace to potential high complexity aerostructure work in Canada, which fits with its existing aeroengine and aerostructure capabilities across Canada, Europe and the United States.
If Gripen is selected and work packages materialize, that could reinforce defence exposure alongside existing multi year contracts, planned single aisle build rate increases and the CAD 51m 2025 investment program. If the bid falls short, investors are still left focusing on execution risk around inventory, capital spending, Middletown restructuring costs and maintaining current earnings quality.
Magellan Aerospace’s current analyst framework points to CA$1.4b in revenue and CA$126.8 million in earnings by 2029, based on a projected 7.3% yearly revenue growth rate and an earnings increase of about CA$67.2 million from CA$59.6 million today.
Uncover why Magellan Aerospace's fair value indicates a 28% potential upside to its current price before the discount gap starts to close.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between CA$38.16 and CA$45.67 per share, which already shows a fairly tight but meaningful spread in expectations. Those views do not yet reflect the Saab Memorandum of Understanding, so you should weigh them against inventory risks, Middletown restructuring costs and potential defence contract momentum. Investor opinions can differ widely. It can be helpful to compare several of these perspectives before deciding how Magellan Aerospace fits into your portfolio.
Explore 2 other Magellan Aerospace fair value estimates, including one that suggests as much as 28% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Magellan Aerospace research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Magellan Aerospace. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Magellan Aerospace's overall financial health at a glance.
Looking for more Magellan Aerospace style investment ideas?
If the Magellan Aerospace story has you thinking about how different businesses fit into a broader portfolio, it can help to scan a wider field of stocks that match specific traits you care about most.
- If balance sheet strength is high on your list, start with a list of solid balance sheet and fundamentals (7 results) that can handle tougher conditions without leaning heavily on new funding.
- For those aiming to limit downside and focus on steadier profiles, filter for 8 resilient stocks with low risk scores that score well on resilience and financial stability.
- When you want ideas that are not already crowded, widen your search to a 9 high quality undiscovered gems that combine strong fundamentals with less attention from the broader market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com