


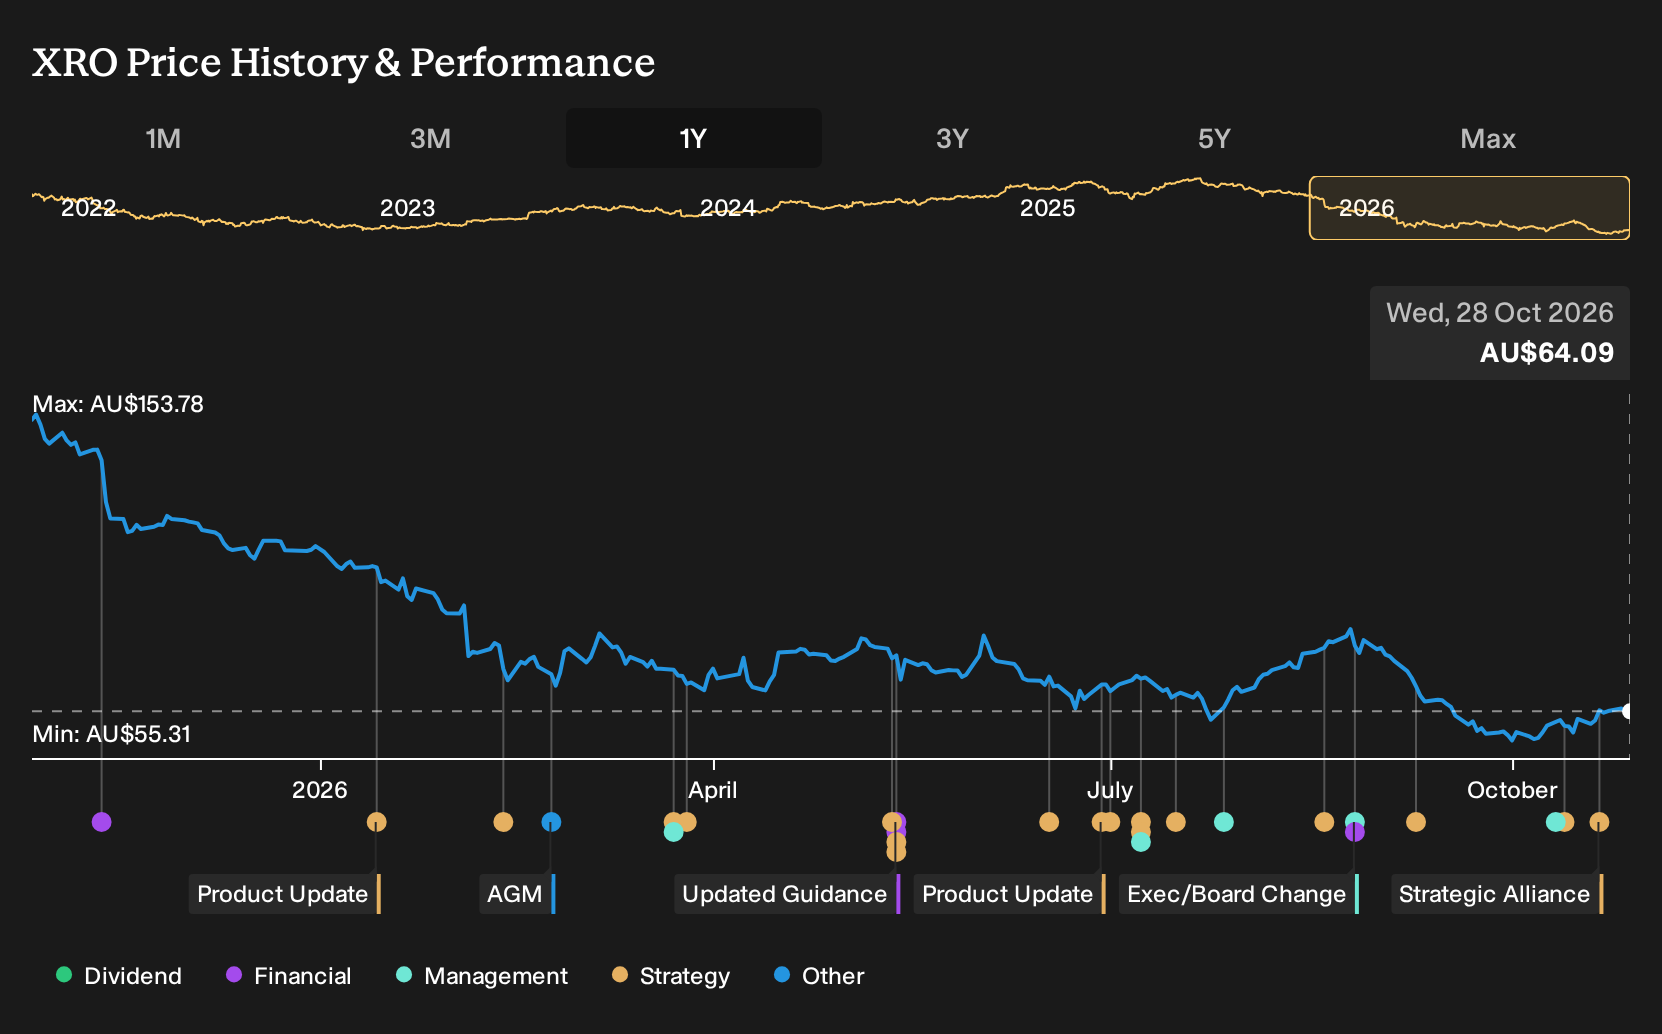
If you had skipped Xero in late October 2025 because the bullish and bearish analyst camps were so far apart on value, the past year would look very different. Investors who held Xero over the past year are down 57.5%, including dividends. That result sits alongside strong FY26 revenue, weaker profit and heavy Melio and AI spending, so what assumptions on margins, P/E or execution risk were already on record that could have made you pause back then?
The easy part of this move is behind Xero. Zero in on 2 high quality undervalued stocks for companies trading below our estimates.
The Two Xero Stories Investors Had To Weigh
The shares cost A$154 at the start of the period, and anyone looking at Xero then had to choose which future looked more reasonable.
On the optimistic side, the bullish narrative saw a Fair Value of A$195, a rough guide to what those expectations pointed to, built on assumptions of 18.1% annual revenue growth and profit margins reaching 18.1% with a future P/E of 61.4x.
The bearish view anchored on a Fair Value of A$100 and treated rising regulatory and cybersecurity costs as real threats, with slower 12.3% revenue growth, profit margins at 17.8% and a future P/E of 59.9x still required to make the numbers work.
What The FY26 Results Did To The Xero Debate
Xero’s FY26 picture gave both camps something to hold on to. Operating revenue reached about NZ$2.75b to NZ$2.8b, broadly in line with the bullish focus on top line. Net profit after tax fell 27%, and H2 2026 net margin dropped to 2.1% from 12.0%. That mix of higher sales and thinner profitability cut both ways.
The real hinge here was the margin assumption. When you see a thesis built on profit percentages and rich P/E multiples, check later filings for where net margin and absolute earnings actually land before trusting the story.
What You Are Paying For In Xero Today
Today Xero trades at A$64.09, with the selected Narrative’s Fair Value sitting above that level. That view leans heavily on the idea that AI and cloud tools deepen, rather than weaken, Xero’s role inside small business workflows.
A buyer now would be relying on Xero converting subscriber and ARPU gains into meaningfully higher net margins without needing proportionate operating cost growth.
"Increasing subscriber numbers alongside increasing ARPU yields 20% annual revenue growth as more and more businesses turn to cloud based accounting solutions with strong integrations and eventual AI features to run their businesses. Xero has high scalability of its products, with current gross margin of ~88%."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond Xero’s Workflow
Xero lives inside daily business tasks. Your next question is who shapes the digital office around it.
Cloud accounting tends to sit beside email, documents and collaboration tools that workers keep open all day.
Another giant platform is trying to weave AI into those routine apps, so typing, meetings and analysis all feel more assisted.
Instead of just selling software, that provider aims to turn its suite into the default work hub.
If that pull into everyday workflow deepens, your map of Xero’s neighbours might need an update.
One Narrative has already put a figure on it. → Uncover the company trading 21% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com