


ONEOK came into this Q3 2026 report riding a solid run, with the stock up over the past month, only to see the price slip about 1.5% today. That small pullback sits awkwardly against a quarter that delivered about US$2.14 in earnings per share and US$1.35b in net income, powered by its midstream energy network.
Expectation and reality are colliding here. Investors had priced ONEOK as a dependable, cash-generating pipeline giant. These results spotlight something sharper, a business leaning hard into profit scale even as the share price takes a breather.
Like the earnings power from ONEOK but wary that a 1.5% pullback might be a sign to be more selective in midstream exposure? Compare this quarter’s profile against a curated group of resilient pipelines and infrastructure plays in the list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
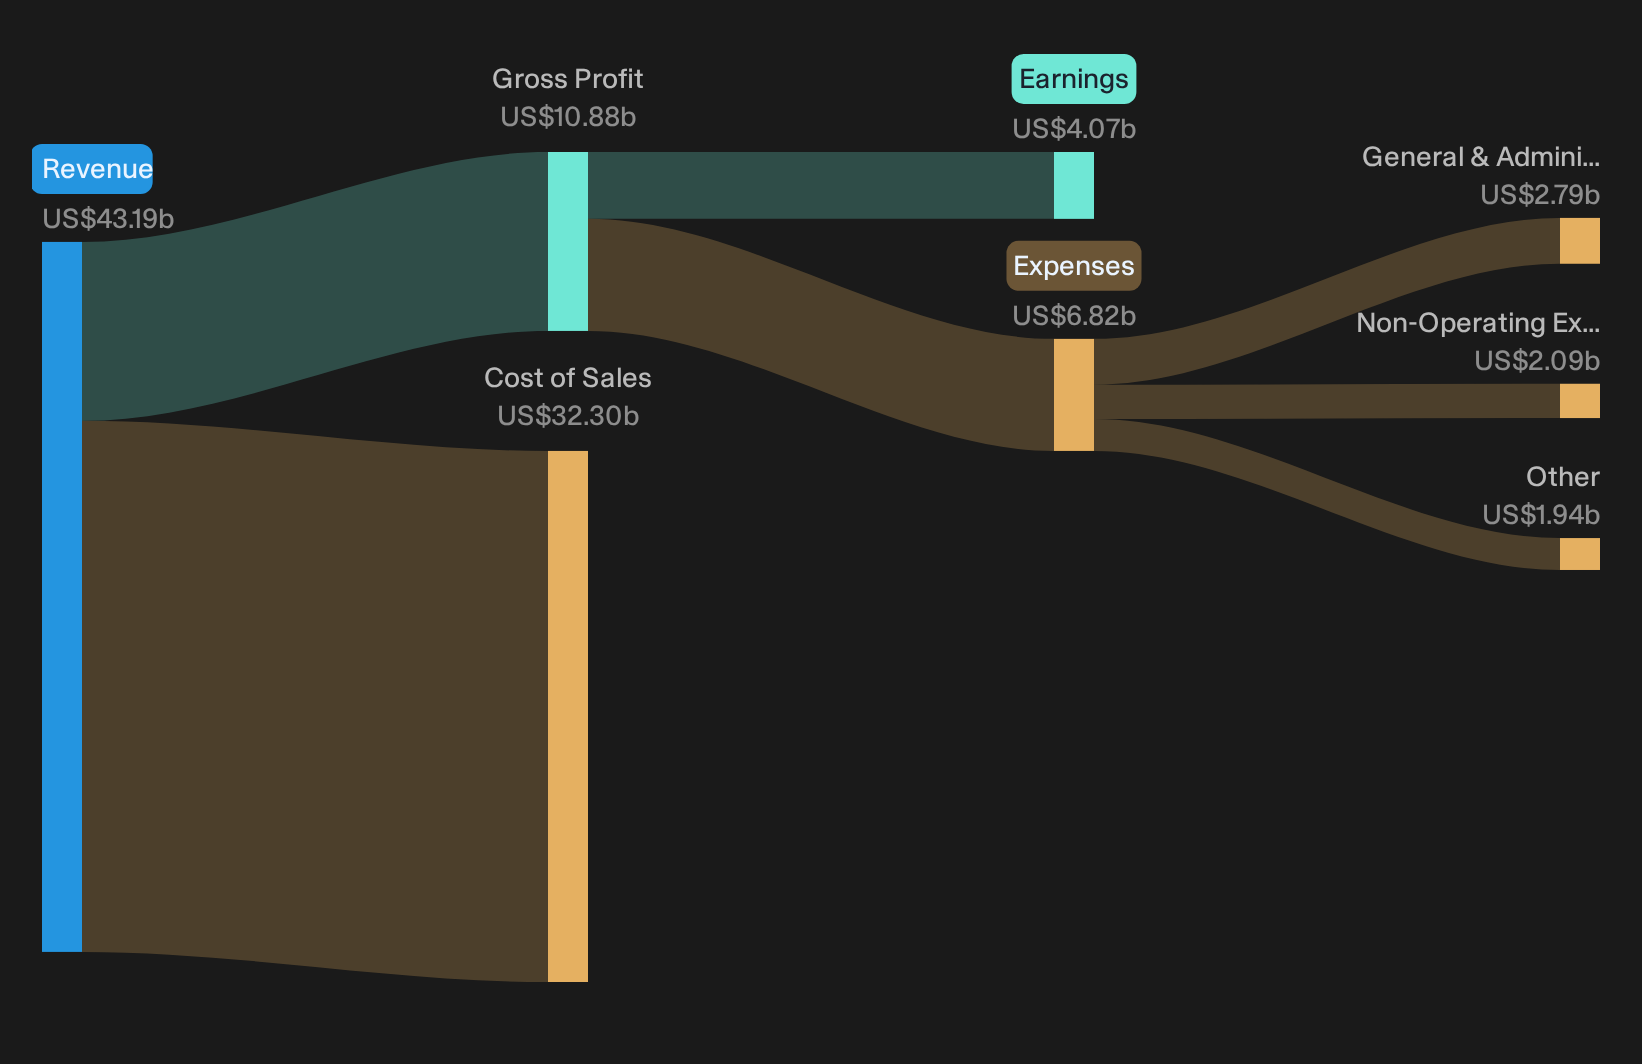
- Revenue (Q3 2026 vs. Q3 2025): US$12,455m vs. US$8,634m (up about 44%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$1,350m vs. US$939m (up about 44%)
- Basic EPS (Earnings Per Share, Q3 2026 vs. Q3 2025): US$2.14 vs. US$1.49 (up about 44%)
- Trailing Net Income (Excl. Extra Items, TTM Q3 2026 vs. TTM Q3 2025): US$4,067m vs. US$3,339m (up about 22%)
Prefer clean charts instead of another wall of earnings tables and raw figures? See ONEOK’s full financial picture with a focus on its valuation, all laid out in a visual, easy-to-scan company report for ONEOK.
ONEOK’s Bull Story Hinges On Execution Milestones Met
For the bullish view on ONEOK, the real test is whether project execution and balance sheet repair are actually tracking to plan.
"The main requirement is that ONEOK successfully executes on large projects, such as the Brazos Midland integration, Permian processing buildout, and Texas City LPG export ramp, while keeping leverage around the newly targeted 3.25x level."
Q3 points to that requirement being met so far. Brazos volumes are already above initial assumptions, existing plants are reported full, and early capital synergies are coming through. Leverage is reset lower after about US$5.5b of debt was repaid with Apollo’s US$9b equity, and ratings are up to BBB+, aligning with the 3.25x framework.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
ONEOK Bear Fears Shift From Volume To Cash
The cautious view argues that ONEOK’s bigger footprint might not translate into equally strong cash generation once growth spending stays high for years.
"The combination of a 15% cash flow allocation to the Class B interest and a still heavy growth CapEx program until at least 2027 creates a window where free cash flow available to common equity could fall short of expectations for faster deleveraging, higher dividends or buybacks."
Q3 results and another 2026 guide increase lean against worries about weak earnings power, yet the evidence on that free cash flow squeeze is still thin. CapEx is now guided to about US$3.5b for 2026, higher than before, and management has kept the dividend flat. The balance sheet has improved with roughly US$5.5b of debt repaid and a BBB+ rating, but the Class B distributions and elevated growth spending remain firmly in place. The bear case around delayed capital returns is not disproved by this quarter, only postponed until ONEOK shows what falls to common equity once the current project wave peaks.
Hunt For Quiet Mispricing
ONEOK’s Q3 shows how a strong operational story can coexist with a flat near term cash backdrop. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 34% below our estimate - uses a record power systems upswing to fund new high horsepower capacity and next generation engine programs.
- Company 2 - 23% below our estimate - turns existing cloud, productivity and developer tools into an AI workflow layer enterprises can standardize on.
- Company 3 - 38% below our estimate - scales device trade in programs that tie government recycling subsidies directly to higher refurbishing volumes and transaction margins.
Those are three of them. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com