


Ahead of today’s report, American Electric Power Company shares had quietly climbed over the past month, then slipped 1.6% to close at US$128.20 as traders reacted to fresh Q3 2026 numbers. The first read looked cautious. The actual story was anything but.
AEP just posted Q3 basic earnings per share of US$2.18 on US$6.8b in revenue and backed that up with a US$100b capital investment plan through 2031 that reshapes the long haul. In the short term, the stock eased. Over multiple years, the debate now shifts to whether this balance sheet can comfortably carry that growth agenda.
Love American Electric Power Company’s long term capital plan but concerned about balance sheet capacity for that investment load? Check out the list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$6,832m vs. US$6,010.4m (up about 13.7%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$1,187m vs. US$972m (up about 22.1%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$2.18 vs. US$1.82 (up about 19.9%)
- Trailing 12-Month Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$3,356m vs. US$3,662m (down about 8.4%)
Earnings are one thing, but if you care about what you are paying for American Electric Power Company, cash flows matter just as much. Based on American Electric Power Company's cash flows alone, the stock could be a modest 10% overvalued.
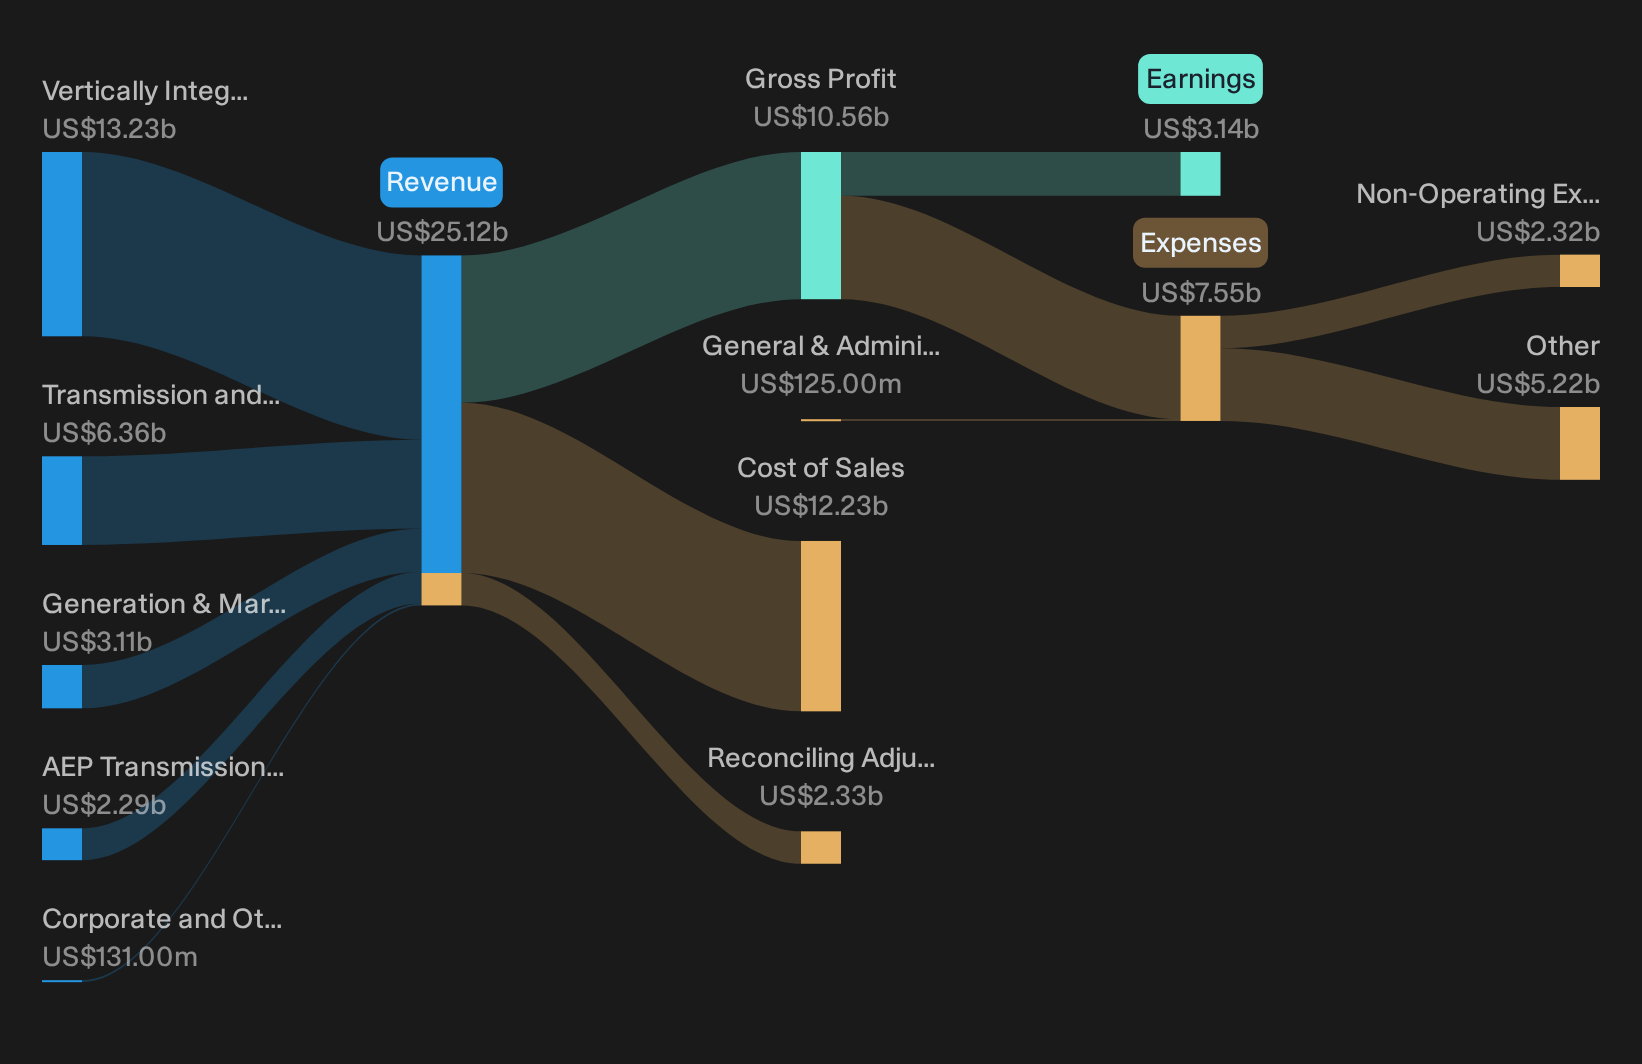
American Electric Power Bull Case Meets Execution Test
Fans of the American Electric Power Company story argue that the capital surge plus data center demand can reshape earnings power if executed cleanly.
"The expanded US$78b capital plan for 2026 to 2030, with a large share directed to transmission and new gas generation, can lift the regulated rate base and support higher earnings over time as projects enter service."
Q3 operating EPS of US$2.23 and guidance now at or above the top of the US$6.25 to US$6.55 range show that early stages of this build are already feeding into results. The US$100b plan through 2031, plus 84 GW of contracted load and a 13%+ rate base CAGR target, confirms management is scaling in line with this thesis.
American Electric Power Bear Case On Concentration Risk
On the risk side, critics worry that leaning so hard into big commercial demand could blunt profitability and stress the plan if that demand cools.
"The reliance on commercial and industrial load to drive growth, as opposed to residential, comes with lower margins, potentially limiting net margin growth despite increased revenues."
Q3 2026 revenue of US$6.8b and operating EPS of US$2.23 arrived alongside a growing skew to data center and hyperscaler load, now 84 GW of contracted additions. Trailing 12 month net income excluding extra items of US$3,356m versus US$3,662m a year earlier shows that higher large load activity has not yet translated into stronger trailing profitability, which keeps this margin concern active.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt Quiet Disconnects In Earnings
American Electric Power Company shows that headline earnings and valuation can diverge. The real opportunity is hunting for stocks that could be undervalued before the market adjusts its view.
- Company 1 - 43% below our estimate - expands payment rails so large online platforms can ramp transactions across more emerging markets without adding local integrations.
- Company 2 - 40% below our estimate - broadens solar hardware and software beyond trackers so storage and inverter projects deepen relationships with utility scale developers.
- Company 3 - 22% below our estimate - grows a branded teahouse network while supplying franchise partners with product, logistics and data systems that raise recurring order volume.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com