


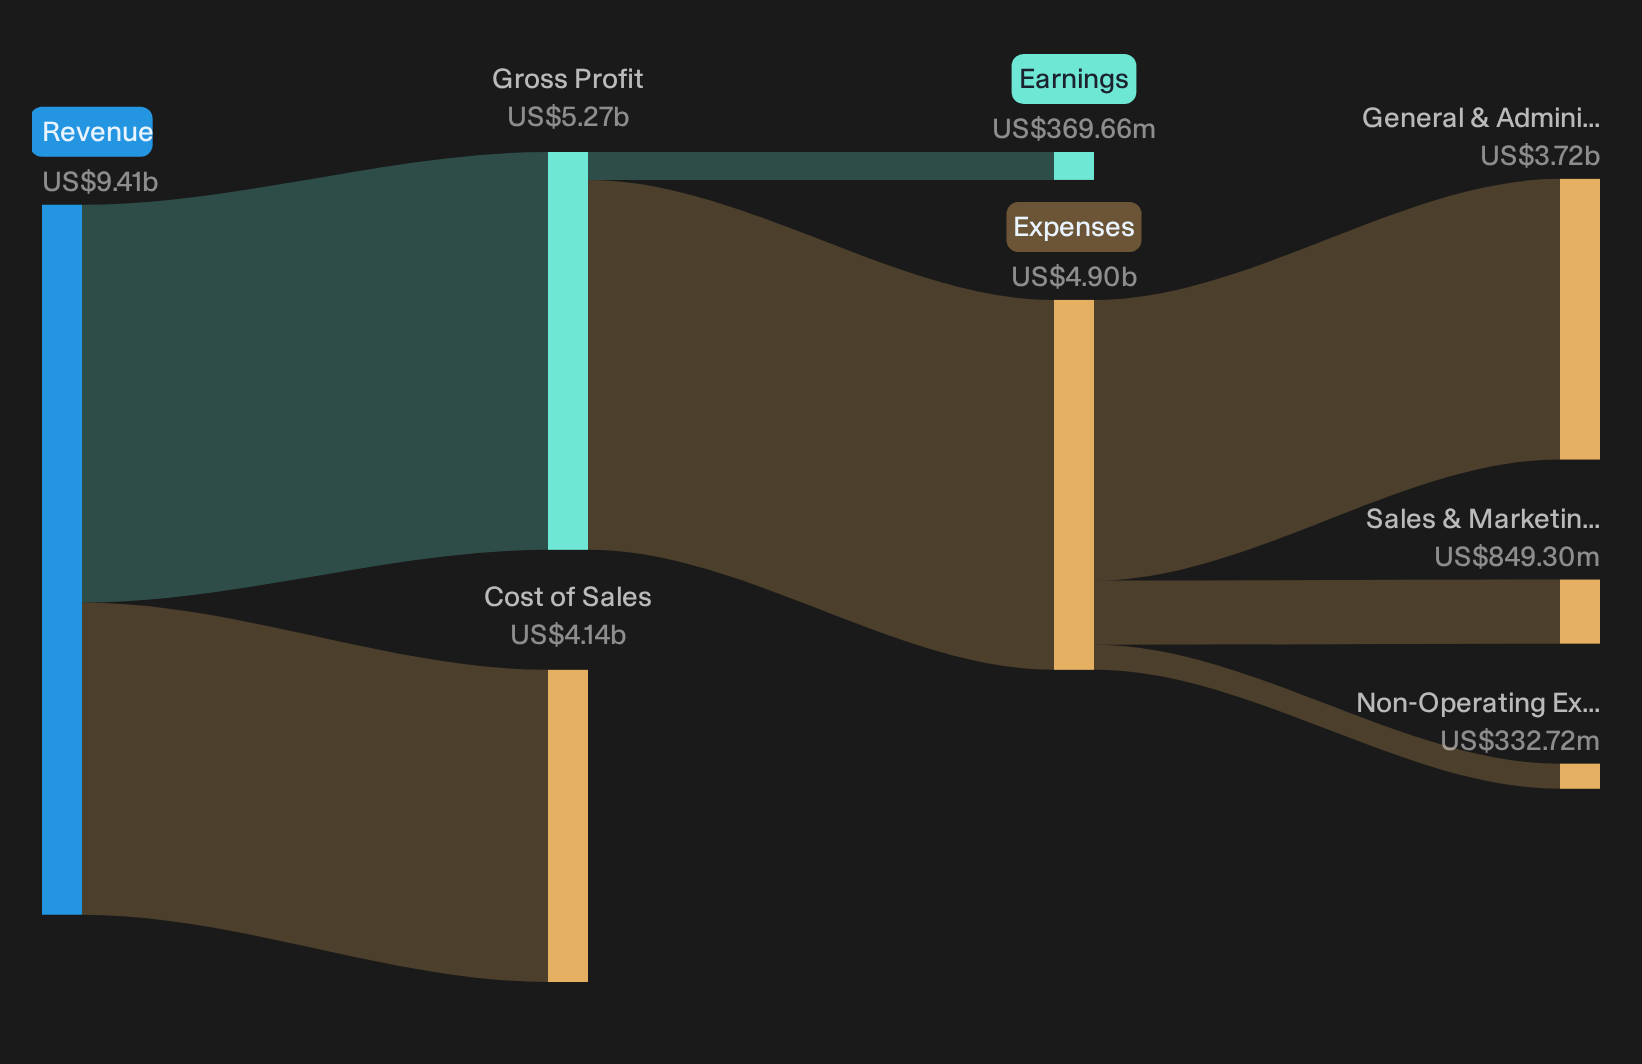
V.F. just closed out Q2 FY2027 with a cleaner story than its modest 1.2% share price move suggests. The stock came into the release already up over the past month, yet the immediate reaction stayed restrained even as earnings per share landed near US$0.70 on about US$2.7b in revenue.
What really drove the quarter was margin repair. Gross margin reached the mid 50s in percentage terms, supported by a combination of product mix, cost work and some foreign exchange help. This matters more for this apparel group than any single revenue headline. The market’s emotion is still cautious. The income statement looks more confident.
Like the margin repair story at V.F but uneasy about whether this kind of earnings rebuild will stick across your portfolio? Check out our screener focused on resilient operators with healthy balance sheets and cleaner fundamentals through the list of solid balance sheet and fundamentals stocks (24 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): US$2,695.1m vs. US$2,802.7m (down 3.8%)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): US$285.3m vs. US$189.8m (up 50.3%)
- Basic EPS (Q2 2027 vs. Q2 2026): US$0.73 vs. US$0.49 (up 49.3%)
- Gross Margin (Q2 2027 vs. Q2 2026): 55.4% vs. roughly 52.5% (up about 290 bps, with around 180 bps structural improvement and 110 bps foreign exchange tailwind)
V.F. says its falling tax rate is a key earnings driver. Ask Charlie what makes V.F.'s tax leverage so powerful.
V.F Margin Thesis Meets Early Execution Milestones
Supporters of V.F Corporation argue that the story hinges on mix, cost work and balance sheet repair rather than a quick Vans fix.
"Bullish analysts expect V.F to keep shifting toward higher-margin DTC and digital sales as cost savings and portfolio reshaping continue to flow through to operating margin and cash generation."
Q2 gives that claim some real footing. Gross margin is in the mid 50s, with most of the lift coming from structural work rather than currency. Operating income of US$364m landed well above guidance, while Vans DTC finally grew again. Management also stuck to its leverage and free cash flow targets, so the margin and deleveraging roadmap remains intact for now.
The price and this Narrative do not agree. → Uncover what this Narrative says V.F is actually worth.
V.F Bear Case: Brand Repair Still Looks Pricey
The bearish view argues earnings quality at V.F Corporation stays fragile because brand repair eats cash and fails to reset profitability.
"V.F’s sustainability and sourcing program is intended to cushion the impact of oil prices and geopolitical shocks, yet the continued exposure to tariffs and the need to keep shifting sourcing show that the supply chain remains vulnerable."
Q2 margins benefitted from structural work and foreign exchange, yet normalized free cash flow in the first half only roughly matched last year and inventory climbed 7%. Tariff refunds inflate full year cash, so underlying conversion still has something to prove. That keeps this concern unresolved rather than disproved.
Hunt Quiet Dislocations Before They Close
V.F just showed how cleaner margins do not always move a stock much in the moment. The real opportunity sits in finding companies that could be undervalued before sentiment catches up.
- Company 1 - 23% below our estimate - expand adoption of robotic surgical platforms as hospitals upgrade joint procedures and capital equipment workflows.
- Company 2 - 25% below our estimate - build out next generation cardiometabolic drugs while scaling manufacturing and payer access for new obesity treatments.
- Company 3 - 43% below our estimate - grow higher margin payment products as large digital merchants increase transaction volumes across more local channels.
That is three of the list. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com