


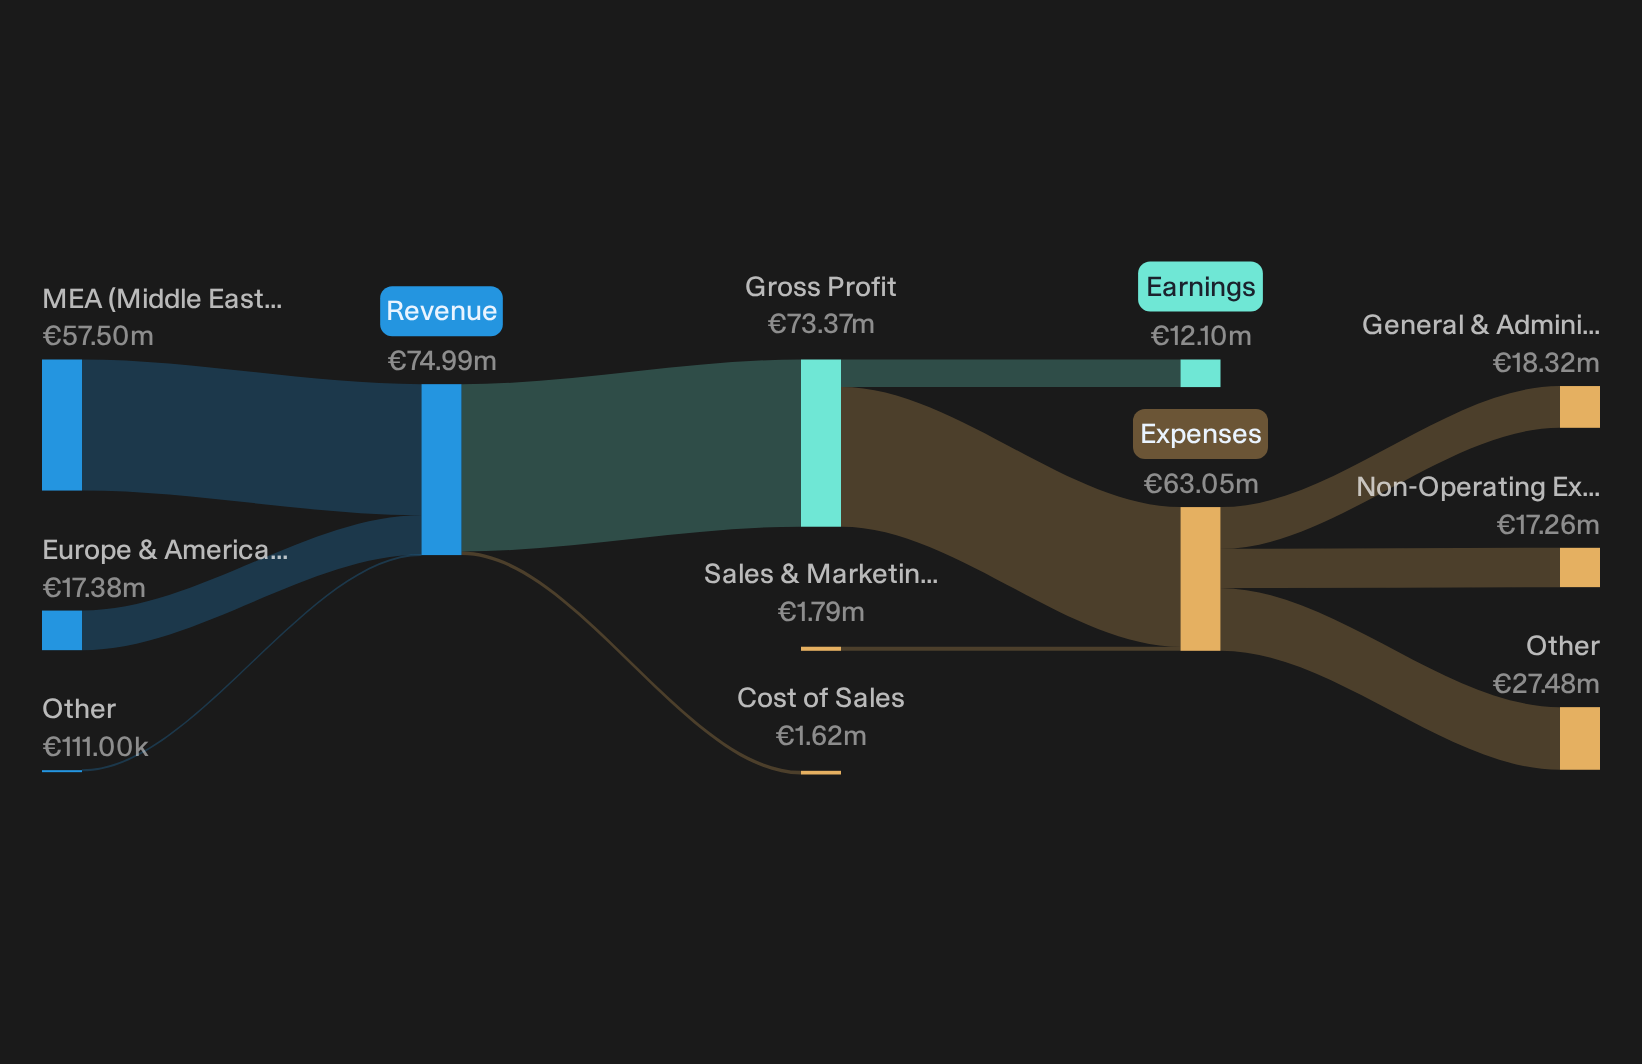
Tecnotree Oyj entered this Q2 2026 report carrying the label of a low P/E software play with punchy recent earnings growth and a history of dilution that kept some investors on the fence. The fresh numbers land with a different kind of force. Revenue for the quarter came in at €19.9m and net income reached €2.4m, feeding into a trailing P/E of 11.4x that still sits below both the Finnish market and European software averages.
The share price closed at €6.06 on 28 October, leaving the stock trading well above a cash flow based value estimate of €2.51 even after the market had time to react. That gap between earnings strength and valuation strain is now the central question for Tecnotree holders.
Love Tecnotree Oyj’s earnings power but uneasy about paying up when the share price already runs ahead of cash flow value estimates? Filter for a tighter price and fundamentals mix using our 195 high quality undervalued stocks.
Q2 2026 Earnings Summary
- Revenue (Q2 2026 vs Q2 2025): €19.9m vs €17.3m (up 14.9%)
- Net Income (Excl. Extra Items, Q2 2026 vs Q2 2025): €2.4m vs €1.0m (up 140%)
- Basic EPS (Q2 2026 vs Q2 2025): €0.11258 vs €0.06 (up 87.6%)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 16.1% vs 10.2% (improved profitability)
Tecnotree’s Q2 margin spiked even as guidance stayed cautious. Ask Charlie what’s really behind Tecnotree’s 43% Q2 margin.
Testing Tecnotree’s Cloud And AI Upside
The bullish story hinges on Tecnotree Oyj turning cloud deals and AI tools into sturdier, higher margin software revenue rather than one off projects.
"Broad adoption of AI in telecom operations and customer experience, combined with Tecnotree’s upgraded positioning from Niche Player to Visionary and over 4,500 product features, can drive mix shift toward higher value software, lifting EBIT margins."
H1 2026 EBIT margin of 36%, with Q2 near 43.3%, lines up with that ambition. ARR rising about 8% and ten straight quarters of positive free cash flow point to more software and services weight. However, free cash flow at €2.1m still trails accounting profits.
Stress Testing Tecnotree’s Backlog And Cash Fears
Bears worry that long projects and slow paying regions could turn that healthy backlog into a cash drag rather than a growth engine.
"If the record order backlog and growing ARR base fail to convert into materially stronger reported growth because of delivery bottlenecks or client side delays, the market may re rate the stock downwards as expectations for accelerating revenue and earnings are not met over time."
Backlog remains high at €106.3m and revenue in constant currency is up 7.8% for the first nine months of 2026, with EBIT higher. Yet DSO at 143 days and receivables more than 1 year old rising to 36% show that collection risk is live, not theoretical.
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for.
Hunt For Mispriced Earnings Power
Tecnotree Oyj’s latest quarter shows how a strong income statement and a stretched valuation can collide. The real opportunity is tracking companies that could be undervalued before the market fully recalculates them.
- Company 1 - 16% below our estimate - uses AI enabled managed services to take over complex healthcare claims and care workflows for payer and provider clients.
- Company 2 - 34% below our estimate - expands a residential launch pipeline that only starts generating cash once projects clear approvals in key urban markets.
- Company 3 - 46% below our estimate - targets higher spending shoppers by opening stores in premium malls while building an online channel that captures repeat fashion purchases.
Three companies from the same screener. Open all 195 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com