


Redeia Corporación entered this Q2 2026 earnings season with a reputation as a high-yield, regulated grid operator trading on a modest 17.1x P/E and offering a 5.24% dividend yield. The latest quarterly release delivered basic earnings per share of €0.23 on revenue of €439.4m, while net income from ongoing activities reached €123.7m. That is not the kind of shock that usually justifies a big reset in the story. If the share price reaction around €15.28 hints at anxiety, the numbers mostly point to a more measured margin squeeze rather than a broken investment case.
Love Redeia Corporación’s regulated yield and 5.24% income but concerned that a 17.1x P/E and recent margin pressure leave limited room for error? Screen for grid and infrastructure players that pair resilient cash generation with stronger balance sheets in our list of solid balance sheet and fundamentals stocks (207 results).
Q2 2026 Earnings Summary
- Revenue (Q2 2026 vs. Q2 2025): €439.4m vs. €407.4m (up about 7.9%)
- Net Income from Ongoing Activities (Q2 2026 vs. Q2 2025): €123.7m vs. €131.7m (declined about 6.1%)
- Basic EPS (Q2 2026 vs. Q2 2025): €0.23 vs. €0.24 (fell about 6.2%)
- Trailing Net Profit Margin (Last 12 Months vs. Prior Year): 28.1% vs. 30.5% (compressed by about 2.4 percentage points)
Net margin slipped again even as revenue kept growing. Ask Charlie what Redeia’s falling margins mean for future earnings.
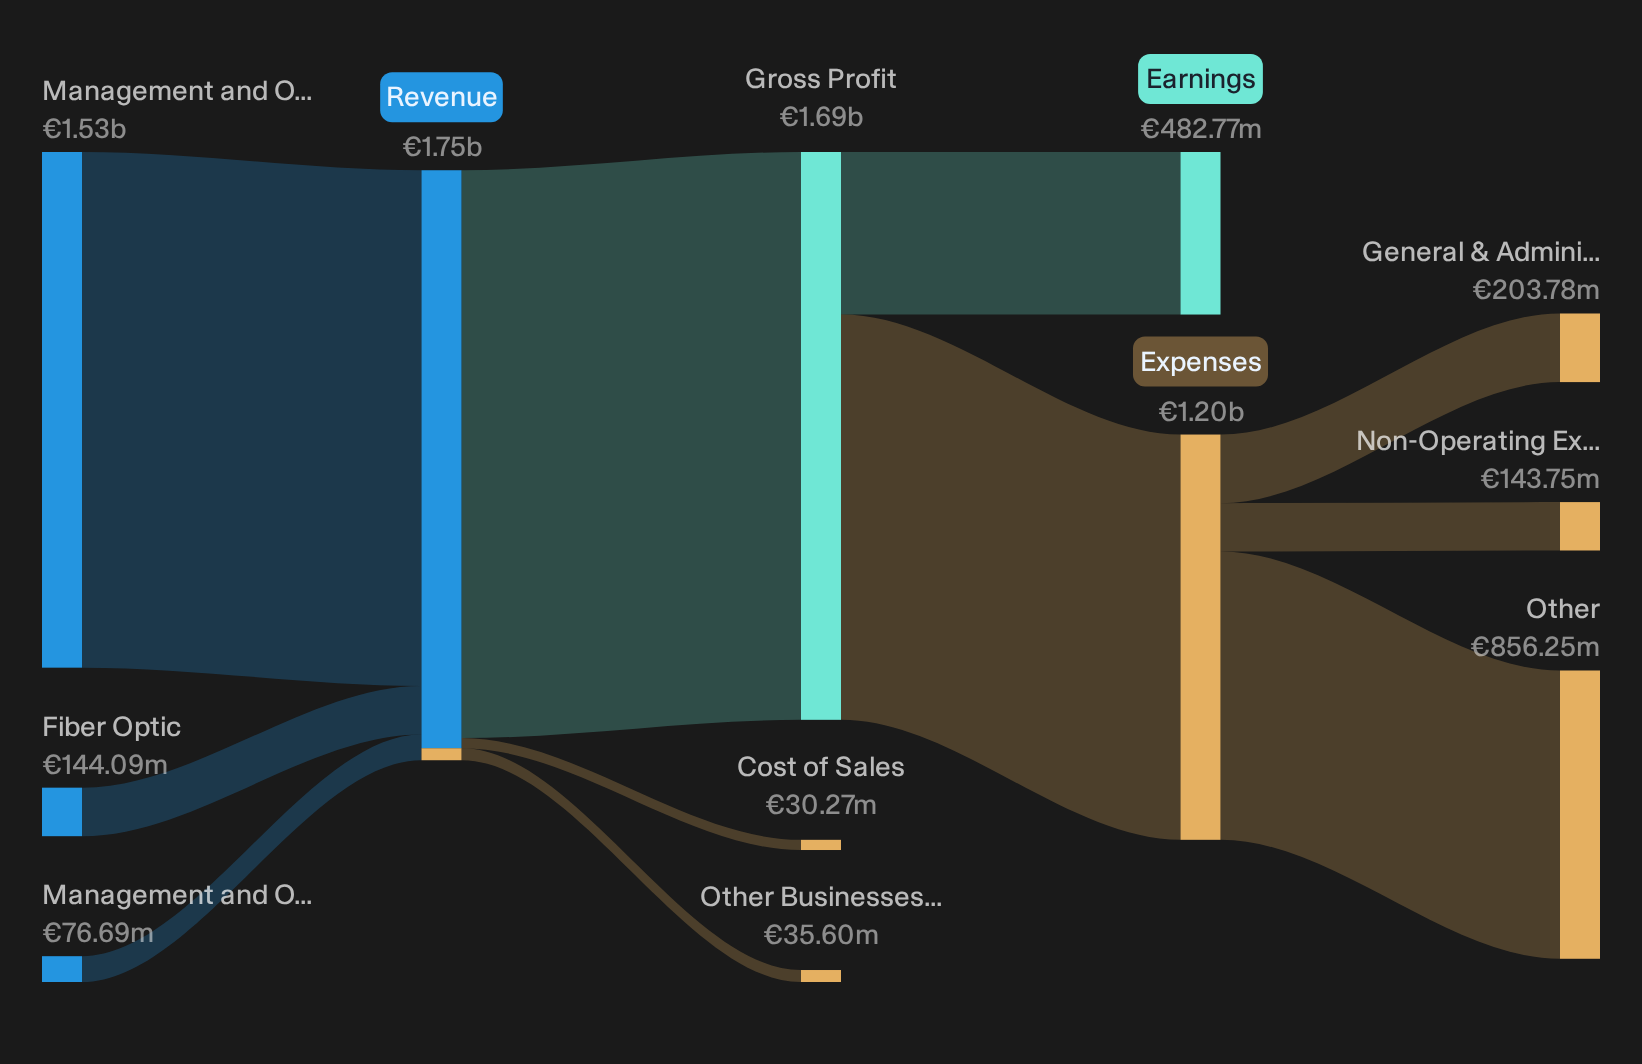
Redeia capex story vs regulated earnings reality
For the upbeat view on Redeia Corporación, the key claim is that heavy Spanish grid investment will compound into a larger, cash generative regulated base.
"Acceleration of Redeia Corporación’s electricity transmission capex, with more than €1.5b invested in 2025 and management expecting 2026 TSO investment to reach and probably exceed that level, supports continued growth in the regulated asset base and therefore in future regulated revenue."
Q2 shows revenue of €439.4m and basic EPS of €0.23 alongside a trailing net margin that has eased to 28.1%. The Nexans preferred supplier award on the Mallorca Menorca 3 link confirms real project flow; however, softer profitability shows that heavy investment is not currently translating into higher earnings efficiency.
Redeia funding strain and non regulated pressure check
The cautious view argues that a heavy funding load plus weaker side businesses could eat into the Spanish grid upside.
"Non Spanish activities already show some pressure, with international transmission revenue affected by fewer projects and higher financial expenses and Reintel’s dark fiber business facing contract renegotiations in a consolidating telecom market."
Group net income from ongoing activities of €123.7m and a trailing 28.1% margin, both below the prior year, suggest that any drag from international and non regulated units is not being fully offset by the core TSO. With a multi year capex and funding plan ahead, that earnings slippage keeps the leverage and subsidy risk firmly in play.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt For Quiet Earnings Disconnects
Redeia Corporación just showed how a modest earnings slip can still leave a complex read on value. The real opportunity is finding stocks that could be undervalued before the gap closes.
- Company 1 - 28% below our estimate - sells maritime sensor and underwater protection systems plugging into longer duration defence programmes.
- Company 2 - 22% below our estimate - supplies unmanned naval platforms and inertial navigation gear within expanding mine countermeasures and integration work.
- Company 3 - 20% below our estimate - distributes low voltage equipment and related services tied to electrification, data centers and industrial automation projects.
Those are three of them. See all 195 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com