


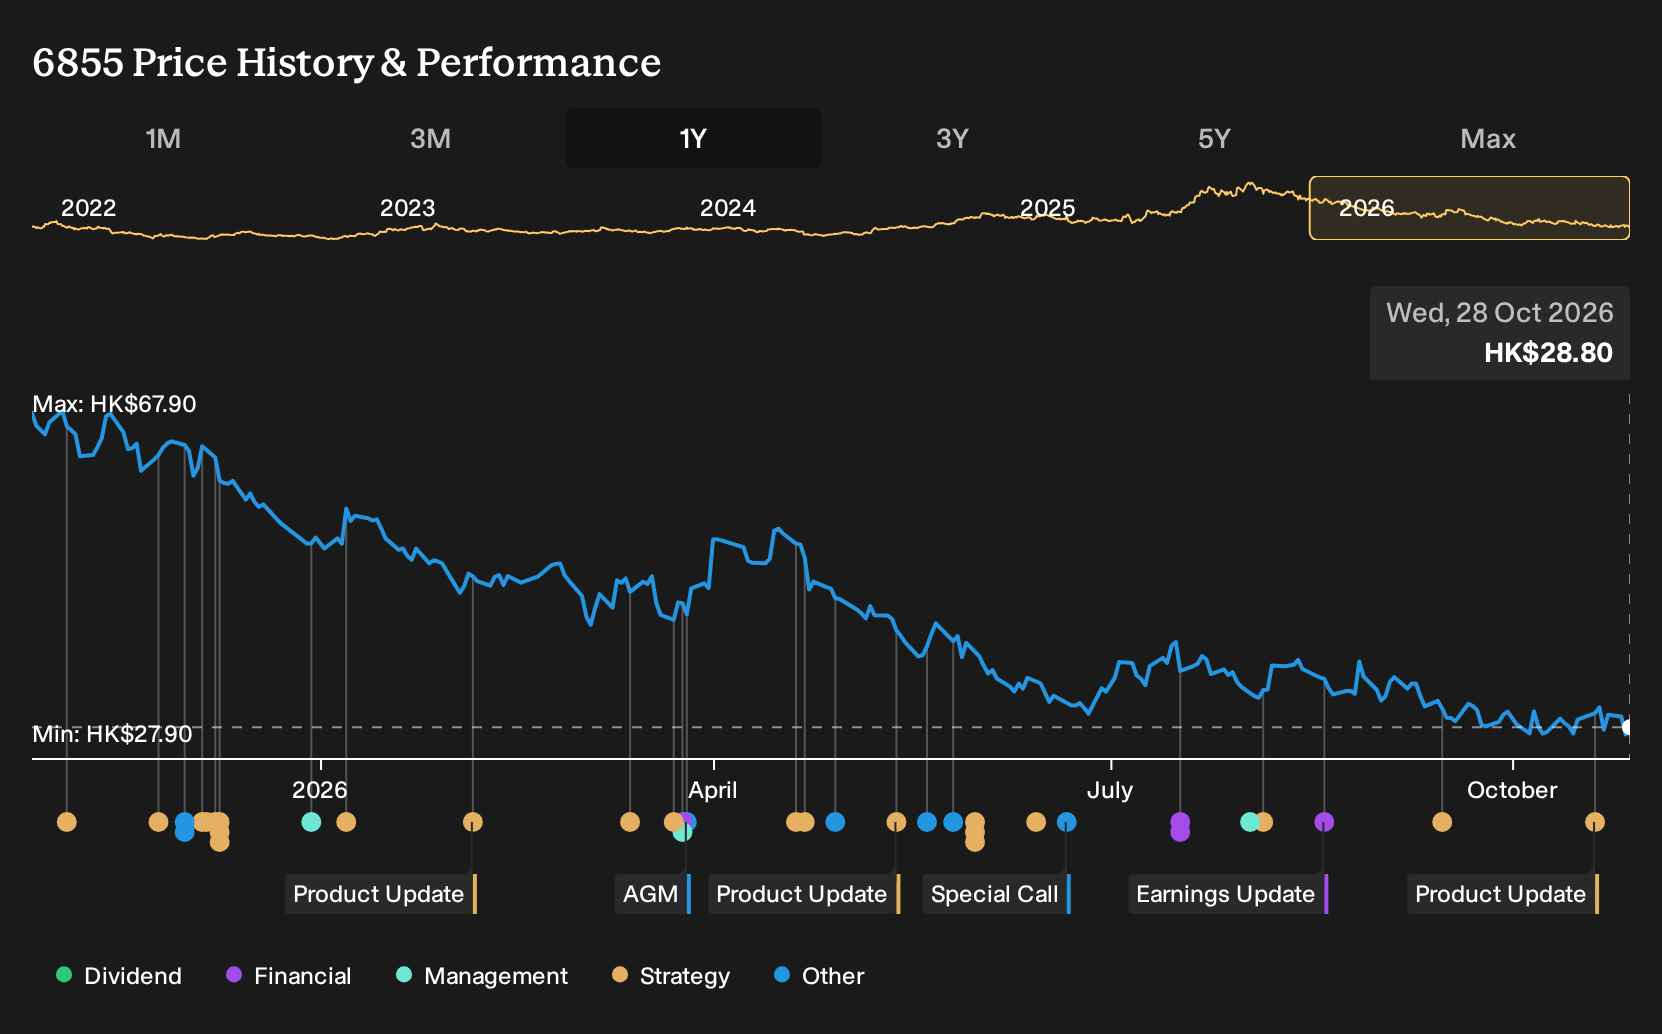
Clinical headlines around Ascentage Pharma Group International have been filled with positive trial readouts and a growing list of late stage studies, while its latest half year update showed higher revenue but a deeper loss and weaker net margin. For Ascentage Pharma Group International shareholders, the loss over the past year was 56.4%, including dividends. If you had been weighing those bullish and bearish analyst narratives back in October 2025, what signals really stood out?
The easy part of this move is behind Ascentage Pharma Group International. Zero in on 195 high quality undervalued stocks for companies trading below our estimates.
The Two Futures Investors Were Arguing About
The shares cost HK$66.1 at the start, and Ascentage Pharma Group International sat between two very different stories about what might come next.
The bullish view pointed to a Fair Value of HK$92.81, a price implied by optimistic assumptions around its future, built on the Takeda collaboration and Olverembatinib. Supporters focused on revenue growth assumptions of 74.7% and an expected profit margin of 38.3% in three years, helped by NRDL inclusion and funding from a recent NASDAQ IPO.
The bearish camp anchored on a Fair Value of HK$51.97 and worried that Takeda milestone payments were one off. That narrative assumed revenue would decline 3.7% a year, even if margins eventually improved to 18.6%, as NRDL pricing pressure, competition and funding risks weighed on the outlook.
What The Results Changed For Ascentage Pharma Group International
The clearest new fact was Ascentage Pharma Group International’s 2026 interim report. Revenue reached CNY302.214 million in H1 2026 compared with CNY233.699 million in H1 2025, which supported the focus on product sales and late stage trials. Net income excluding extra items moved further into loss at CNY816.694 million and net margin declined to -270.2%, so the profitability part of the positive case remained unproven. Overall, the evidence cut both ways.
The key assumption investors can take to other biotech stocks is how fast high grossing assets translate into better net margins. Track whether rising sales move losses toward breakeven and whether margin direction aligns with any profitability timeline you are being asked to consider.
What Ascentage Pharma Group International’s Drop Leaves You Weighing Today
Ascentage Pharma Group International now trades at HK$28.8, with the past year’s move leaving the Narrative’s Fair Value sitting above the current price. That view leans heavily on late stage lisaftoclax and olverembatinib programs, as well as an expanded commercial reach.
Any buyer today would need to test the assumption that late stage trials convert into approvals that support broader usage and materially higher product revenue.
"The key requirement for this outlook is the successful execution of the late-stage lisaftoclax and olverembatinib trials, including GLORA-4, POLARIS-1 and POLARIS-2, while also managing rising R&D and selling expenses."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 43% below our estimate - converts a record project backlog into technology heavy data center and modular builds.
- Company 2 - 26% below our estimate - shifts toward higher growth adult and oral health probiotics sold through direct channels.
- Company 3 - 31% below our estimate - grows fee income by raising real asset and tax efficient retail fundraising inflows.
That is three of the list. See the full list of 207 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com