


Group 1 Automotive entered its Q3 2026 earnings with a bruised share chart after a roughly 16% slide over the past three months, and the stock then slipped another 1.8% to about US$249.54 on the day of the release. That quick markdown suggests investors focused on near term pressure rather than the underlying story. The real headline is the valuation strain. The company trades on a P/E of 7.8x while carrying rent adjusted leverage of about 3.3x, heading toward roughly 4.0x after the Hennessy acquisition and planned disposals.
Like the earnings story for Group 1 Automotive but uneasy about leverage creeping toward roughly 4.0x after Hennessy and the disposals plan? Consider a screener focused on similar operators with stronger balance sheets through our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$5,396.7m vs. US$5,782.7m (declined 6.7%)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$102.9m vs. US$13.1m (up very significantly)
- Basic EPS (Q3 2026 vs. Q3 2025): US$8.65 vs. US$1.03 (up very significantly)
- Trailing 12 Month Net Profit Margin (TTM to Q3 2026 vs. prior year): 1.7% vs. 1.7% (margin level reported as higher year on year)
Prefer visual charts instead of another dense block of earnings tables and ratios? See Group 1 Automotive's full financial picture with an at-a-glance view of its valuation through our company report for Group 1 Automotive.
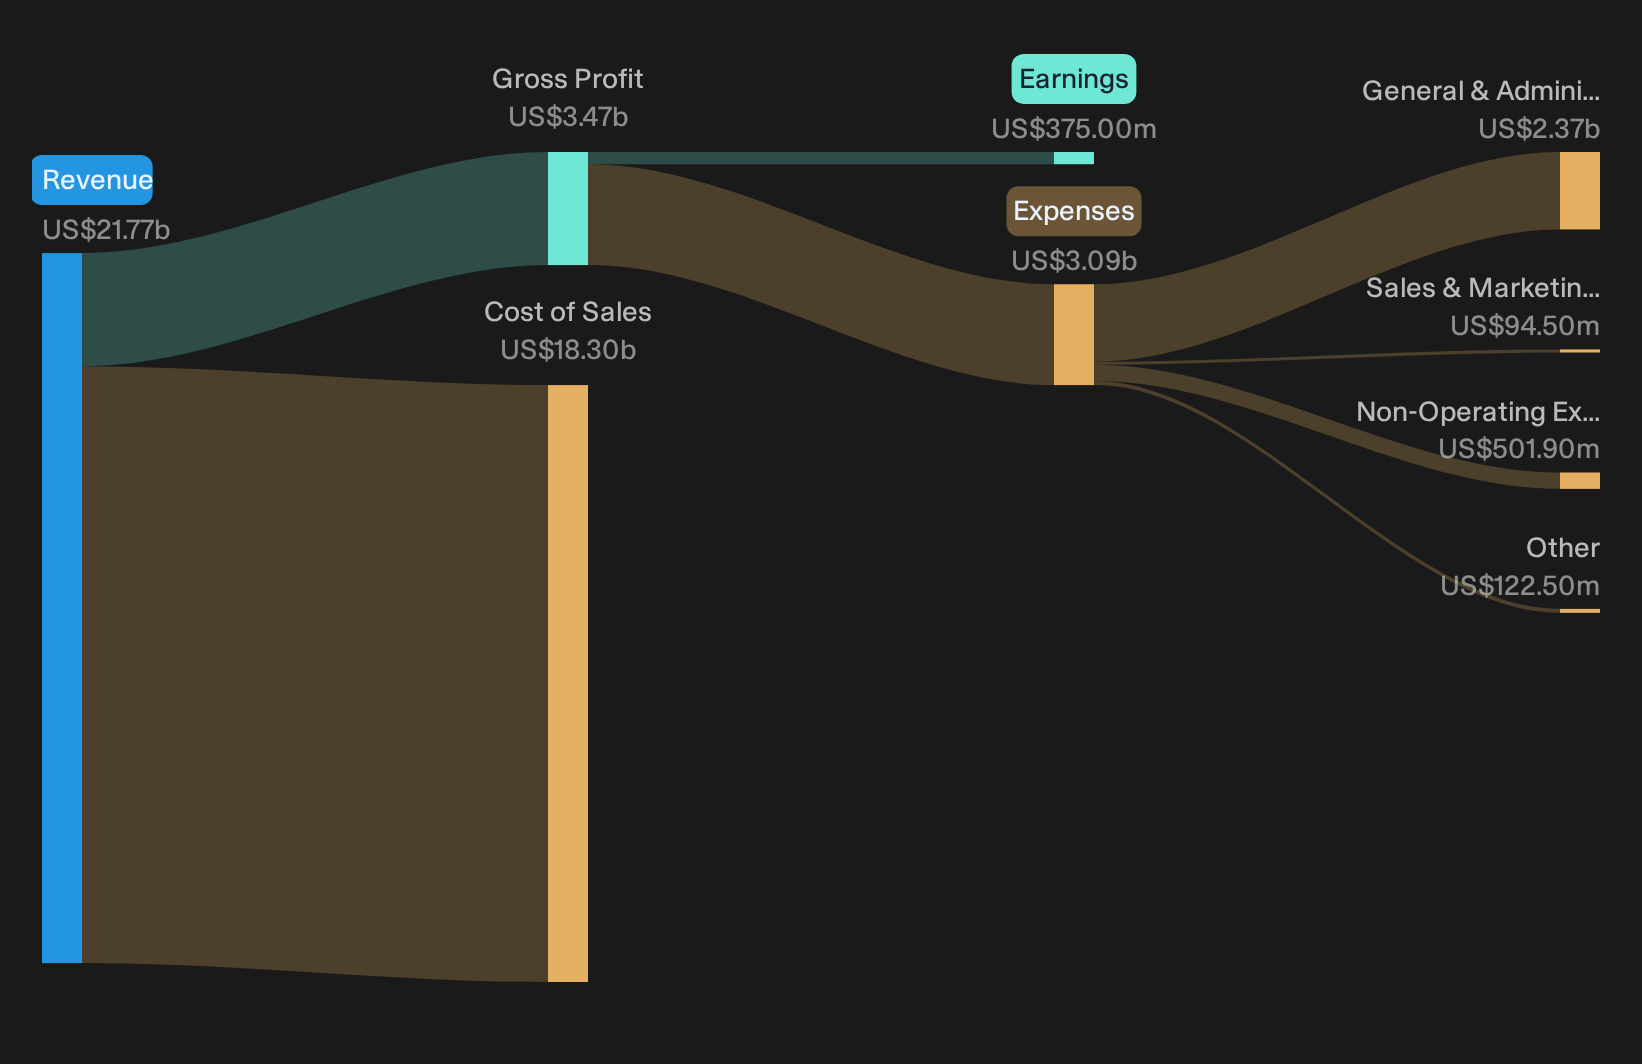
Group 1 Automotive: Mix Upgrade Is Showing Up
Bulls argue that Group 1 Automotive’s mix shift and cash focus can carry value even while units stay soft.
"The main thing that has to go right is that Group 1 Automotive continues to translate portfolio pruning, Hennessy scale up, cost reductions and rebranding into sustained cash generation while keeping leverage within its stated targets."
Q3 points in that direction. Aftersales produced record customer pay revenue and higher gross profit while U.S. new and used units declined. Hennessy adds roughly US$1.7b of largely luxury revenue with higher EBITDA margin, and management targets about a 30 bps EBITDA lift and 100 bps SG&A ratio improvement as pruning and integration mature.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Group 1 bear case: execution risks still unresolved
The harsher view on Group 1 Automotive hinges on execution slipping just as leverage steps up.
"Even though virtual F&I is lifting throughput and reducing compensation costs where it is deployed, broadening this technology and other digital tools across the network requires upfront investment and carries execution risk."
Q3 shows some progress, yet the concerns are not fully cleared. Virtual F&I still touches a minority of U.S. stores, and the completed U.S. rebrand coincided with softer same store new vehicle volumes. Aftersales and the Hennessy acquisition help earnings quality, but digital and branding milestones remain only partially hit.
Hunt For Mispriced Cash Generators
Group 1 Automotive just reminded investors that share prices do not always track quarter-to-quarter noise. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 28% below our estimate - targets complex manufacturing wins in aerospace, defense and healthcare and applies tight cash-cycle discipline.
- Company 2 - 31% below our estimate - refines plant footprints and portfolio mix so aftermarket service and nuclear-linked orders replace lower margin kit sales.
- Company 3 - 23% below our estimate - rolls out surgical robots and smart-care products that support higher value procedures for hospitals using the platform.
That is three of the list. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com