


BASF (XTRA:BAS) is back in focus after reporting third quarter 2026 results, raising its EBITDA outlook, and pushing ahead with capital discipline and an Agricultural Solutions IPO plan.
The recent Q3 upgrade to BASF’s EBITDA outlook and its push on capital discipline have landed against a backdrop of firm price momentum, with a year to date share price return of 18.0% at a share price of €52.84 and a 1 year total shareholder return of 26.04% that points to improving sentiment around both earnings power and risk profile.
Scan how BASF's earnings upgrade compares with peers by checking stocks on the move in the 195 high quality undervalued stocks that pair cash generation with balance sheet strength.
Bulls point to BASF’s higher EBITDA outlook, capital discipline and Agricultural Solutions IPO plans. Bears focus on acquisition noise and a limited discount to analyst targets. The key question is which side the current valuation actually supports next.
Most Popular Narrative: 1% Overvalued
BASF’s most followed narrative pegs fair value at €52.47, almost level with the last close of €52.84, which leaves little implied margin either way and puts the focus firmly on execution of its current plan.
The main thing that has to go right is that BASF delivers the targeted cost savings and CoreShift efficiencies while keeping large assets like Zhanjiang and Ludwigshafen running reliably and supplying customers through energy and logistics disruptions.
The current valuation and capital return plans imply that the market already prices BASF as fairly valued with a bullish tilt, assuming the company sustains its current balance of earnings, cash generation and shareholder distributions.
See why 109 investors see BASF as 1% overvalued.
Result: Fair Value of €52.47 (OVERVALUED)
Still, if European restructuring drags or portfolio moves like the Agricultural Solutions IPO slip, the current BASF fair value story could quickly look exposed.
Find out about the key risks to this BASF narrative.
Another View on BASF’s Valuation
There is a very different message coming from the SWS DCF model for BASF. While analyst fair value sits around €52.47 and is tagged as slightly overvalued, the DCF output places future cash flow value closer to €115.65, which frames today’s price near €52.84 as a large upside gap. The key question is whether you place more weight on the multiple based on near term earnings or on the cash flow model built on longer term assumptions.
Look into how the SWS DCF model arrives at its fair value.
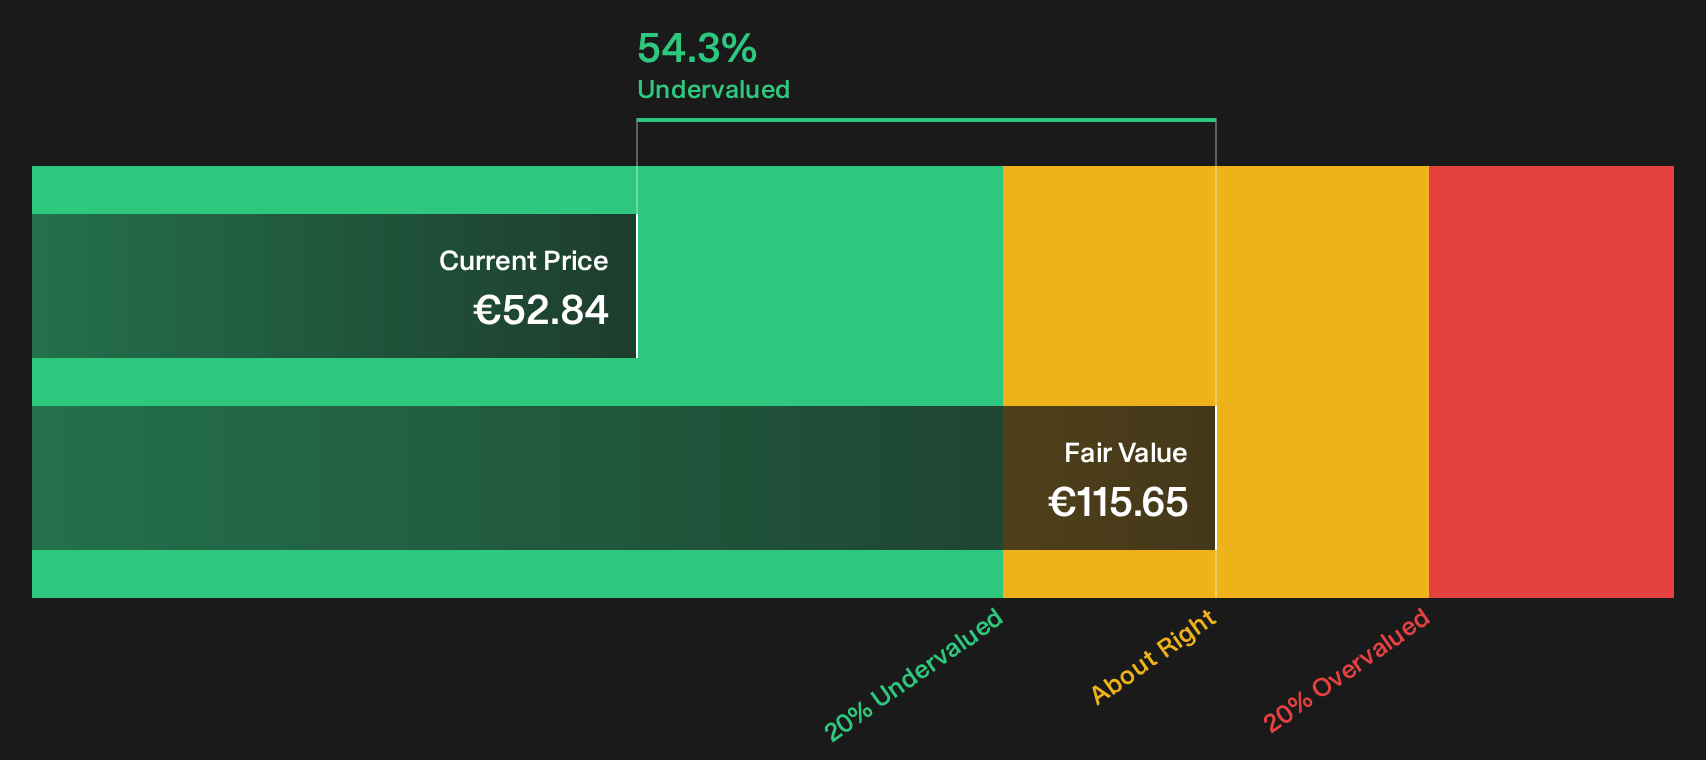
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out BASF for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around BASF’s outlook do not have to leave you on the fence. Act quickly, review the data on both sides and weigh the 2 key rewards and 3 important warning signs.
Looking for more BASF sized investment ideas?
You have seen how one stock can split opinions. Now widen your watchlist with clear, data driven ideas that you can compare against BASF in minutes.
- Target potential mispricings by scanning a focused set of quality candidates through the 195 high quality undervalued stocks that blend strong fundamentals with appealing valuations.
- Strengthen your income stream by reviewing the 224 dividend fortresses built around companies offering higher yields backed by resilient cash flows.
- Prioritise resilience by using the 223 resilient stocks with low risk scores to spot businesses with lower risk scores that can help balance out bolder positions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com