


- FactSet Research Systems recently reported earnings that exceeded expectations, with management highlighting strong subscription demand, high client retention, and growing adoption of AI enabled tools across its platform.
- The earnings update pointed to successful commercialization of AI capabilities and disciplined cost control, which management described as an important support for future profitability.
- Now the focus is on how FactSet Research Systems' stronger AI usage and subscription momentum may reshape the investment narrative around margins and growth.
Scan how FactSet Research Systems’ push into AI and private markets compares with other data and analytics players by reviewing the hand picked 21 high quality undiscovered gems now shaping institutional workflows.
FactSet Research Systems Investment Narrative Recap
To own FactSet Research Systems, you need to believe this is a sticky, subscription-driven data platform that can keep layering on higher value content and AI tools without letting costs get away again. The recent earnings beat and commentary that profitability has likely bottomed tie directly into that. The near-term swing factor is whether AI-enabled products and enterprise contracts translate into steadier margin rebuild.
On the risk side, the same client base that powers that model can become a drag if asset managers and banks stay tight on tech budgets or resist price rises. Competitive pressure in AI analytics and data delivery, plus FactSet Research Systems' higher debt load, leaves less room for missteps if ASV growth softens or cost savings slow.
The Nasdaq Private Market partnership is the clearest operational link to this story right now. Integrating verified Cap Table data into FactSet Research Systems’ platform deepens its private markets coverage and gives clients a more complete view of ownership and funding activity. That aligns neatly with the push to make AI tools and MCP data feeds more useful for deal teams and allocators.
For catalysts, this matters because it gives the firm another way to support ASV from higher value workflows such as due diligence, valuation and deal sourcing rather than just adding seats. The flip side is execution risk. If integration is clunky or rival platforms offer broader private coverage, the commercial payoff from this content addition could be slower than investors expecting a clean uplift in margins might want.
What The Current FactSet Research Systems Forecasts Assume
FactSet Research Systems’ current analyst framework leans heavily on two levers: modest top line expansion and fatter profit margins as AI tools and private market content spread across the platform. The headline inputs are clear. Consensus has revenue growing 5.7% a year over the next three years and net margins rising from 21.5% today to 24.1% on a roughly three year view.
On earnings, analysts are penciling in US$533.5 million today and US$704.3 million by about 2029, with broad agreement around that endpoint. That implies an earnings increase of roughly US$170.8 million over the period. The same set of forecasts also assumes the share count shrinks by 5.48% per year for the next three years, which means part of the earnings per share story relies on buybacks doing some work alongside any operational improvement.
Valuation assumptions are just as specific. To line up with the consensus view, the stock would be earning US$704.3 million on US$2.9b of revenue in 2029 and trading on a P/E of 15x, compared with 20.1x today. That multiple would sit below the current 38.1x P/E quoted for the wider US Capital Markets peer group, so the case is less about a premium rating and more about steady cash generation matching that lower earnings multiple.
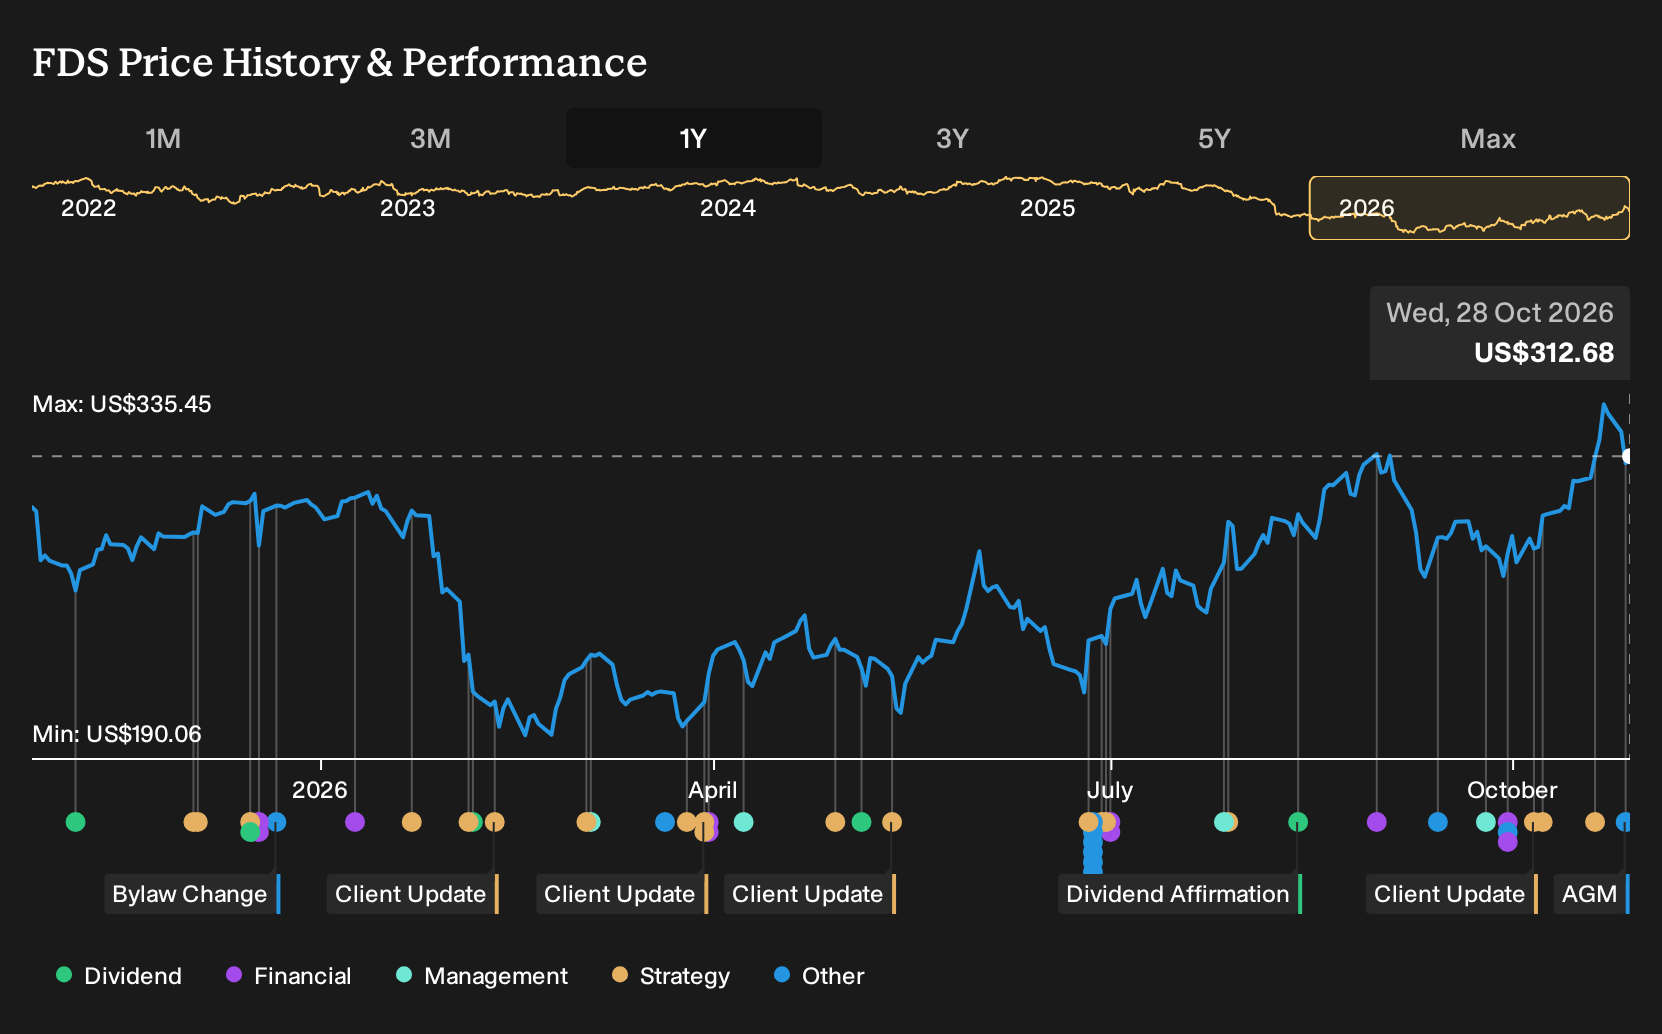
Anchoring all of this is the current price context. With FactSet Research Systems at US$301.83 and the average analyst target at US$280, the implied 7.8% gap suggests many covering the stock see it as roughly in line with their base case. The bullish and bearish targets span US$340 and US$212 respectively, which shows how much the end result still hinges on execution around AI monetization, private data integration and the timing of any margin rebuilding after the heavier FY 2026 investment phase.
FactSet Research Systems' narrative projects US$2.9b revenue and US$704.3 million earnings by 2029. This rests on 5.7% yearly revenue growth and an earnings increase of about US$170.8 million from US$533.5 million today.
Uncover how FactSet Research Systems' fair value indicates a 10% potential downside to its current price, creating a valuation gap that leaves little room for error.
Exploring Other Perspectives
One alternate view fixates on margin risk at FactSet Research Systems. The most bearish analysts were only assuming about US$2.9b of revenue and US$653.1 million of earnings by 2029, with a 12.4x P/E, before this Nasdaq Private Market partnership. That is far more cautious. Use this spread in expectations to explore multiple angles.
Explore 5 other FactSet Research Systems fair value estimates, including one that suggests as much as 32% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your FactSet Research Systems research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FactSet Research Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FactSet Research Systems' overall financial health at a glance.
Looking for more investment ideas beyond FactSet Research Systems?
If the FactSet Research Systems story has sharpened your thinking about quality, risk and price, use that same filter across the wider market with the Simply Wall St Screener and build a watchlist that fits your own playbook.
- If you want income potential paired with resilience, check out companies in our 5 dividend fortresses that could appeal if you prefer cash returns alongside fundamentals.
- For investors who care most about balance sheet strength and staying power, start with the list of solid balance sheet and fundamentals (24 results) to see which businesses might hold up when conditions get tougher.
- If you are hunting for overlooked stories with solid underlying metrics, scan the 21 high quality undiscovered gems and see which lesser known stocks fit your criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com