


Del Monte walked into this Q3 2026 release with a stock that had drifted over the past month, then ticked up about 1.3% today to roughly US$29 as headlines hit. That small bounce suggests investors saw something reassuring. The headline story is simple: net sales reached about US$1.1b and adjusted earnings per share landed near US$0.50, indicating a quarter in which the prepared foods business carried more weight while fresh produce faced higher costs.
Like the steady top line but uneasy about a prepared foods tilt while fresh produce wrestles with higher costs? Check out our screener of list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
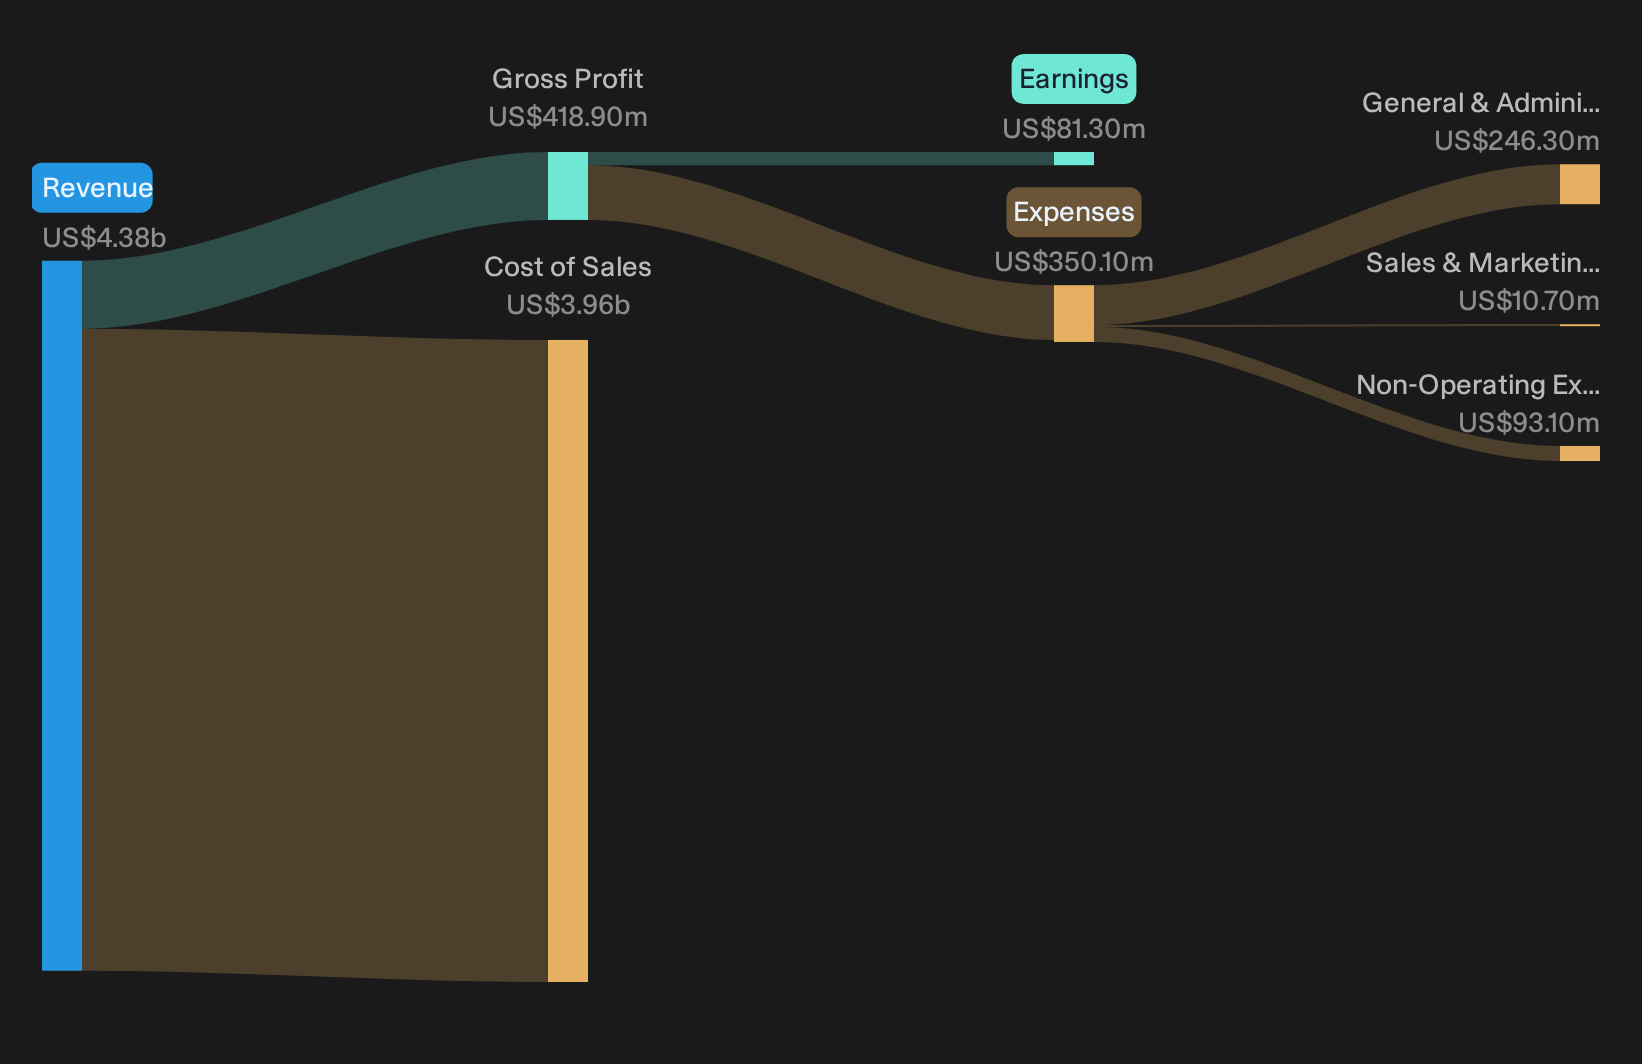
- Revenue (Q3 2026 vs. Q3 2025): US$1,095.3m vs. US$1,021.9m (up 7.2%).
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$18.3m vs. a loss of US$29.1m (returned to profit).
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.39 vs. a loss of US$0.61 per share (moved back into positive territory).
- Gross Margin (Q3 2026 vs. Q3 2025): 9.4% vs. 7.9% (improved by 150 basis points).
Earnings are one thing, but investors who care about valuation usually want to see how those accounting profits translate into actual cash generation that can support reinvestment, debt reduction, and shareholder returns over time.
When you line up Del Monte's cash flows against the current share price, the numbers on their own suggest the stock could be a notable 19% overvalued.
Del Monte bullish mix shift meets early proof points
The upbeat story says Del Monte Corporation can lean on premium fruit and prepared products to power a different earnings mix.
"Analysts expect Del Monte to keep shifting its mix toward premium fresh fruit and higher-margin prepared products while integrating the reunited Del Monte brand into a single, broader platform."
Q3 gives some evidence. Prepared foods delivered the highest segment gross margin at 17.5% and helped lift group gross margin to 9.4%. Integration is about 60% complete and Foods guidance just moved up to about US$650m sales and US$45m adjusted EBITDA for 2026, ahead of the original plan.
Cost and banana risks still biting Del Monte
The bear story argues that cost inflation and banana pressure could swamp those brand gains.
"Persistent cost pressures from ocean freight surcharges, inland transportation, fertilizer and packaging linked to energy markets could keep Del Monte's input costs elevated. This would limit any improvement in gross margins and constrain earnings even if revenue from premium fruit and prepared products meets expectations."
Q3 results show that concern is still live. Management now expects US$55 to US$65m of inflation headwind for 2026, with more than half in bananas. Banana gross margin is now guided to 2 to 3%, down from 3 to 4%, and fresh volumes are under strain despite pricing support.
The price and this Narrative do not agree. → Uncover what this Narrative says Del Monte is actually worth.
Hunt For Quiet Mispricings
Del Monte just showed how a mixed quarter can still leave investors debating what the price already reflects. The real opportunity could be in companies where fundamentals and valuation have visibly fallen out of sync.
- Company 1 - 31% below our estimate - lean into an expanding advisory platform as record mandates support larger, higher fee transactions.
- Company 2 - 43% below our estimate - build on demand for large LED systems while a margin plan and manufacturing reset reshape earnings quality.
- Company 3 - 40% below our estimate - scale newer storage and inverter offerings so a higher margin mix can offset project delays and bottlenecks.
Those are three of them. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com