


Standard Chartered stock closed at £20.68 on the day of its Q3 2026 release, capping a choppy month that left the 30 day return down about 11%. Traders focused on recent share price pressure. Longer horizon investors focused on something else.
The bank just delivered what management called a record third quarter, with income of about $5.7b and profit after tax above $2.0b. That combination of soft recent share performance and solid reported earnings sets up a clear question for you: Are you trading the next week, or weighing the next few years?
Impressed by Standard Chartered turning in about $5.7b of income and more than $2.0b of profit after tax, yet uneasy about the recent 11% 30 day share price drop? Benchmark those results against other banks with solid earnings and less recent price pressure by checking our list of solid balance sheet and fundamentals stocks (10 results)
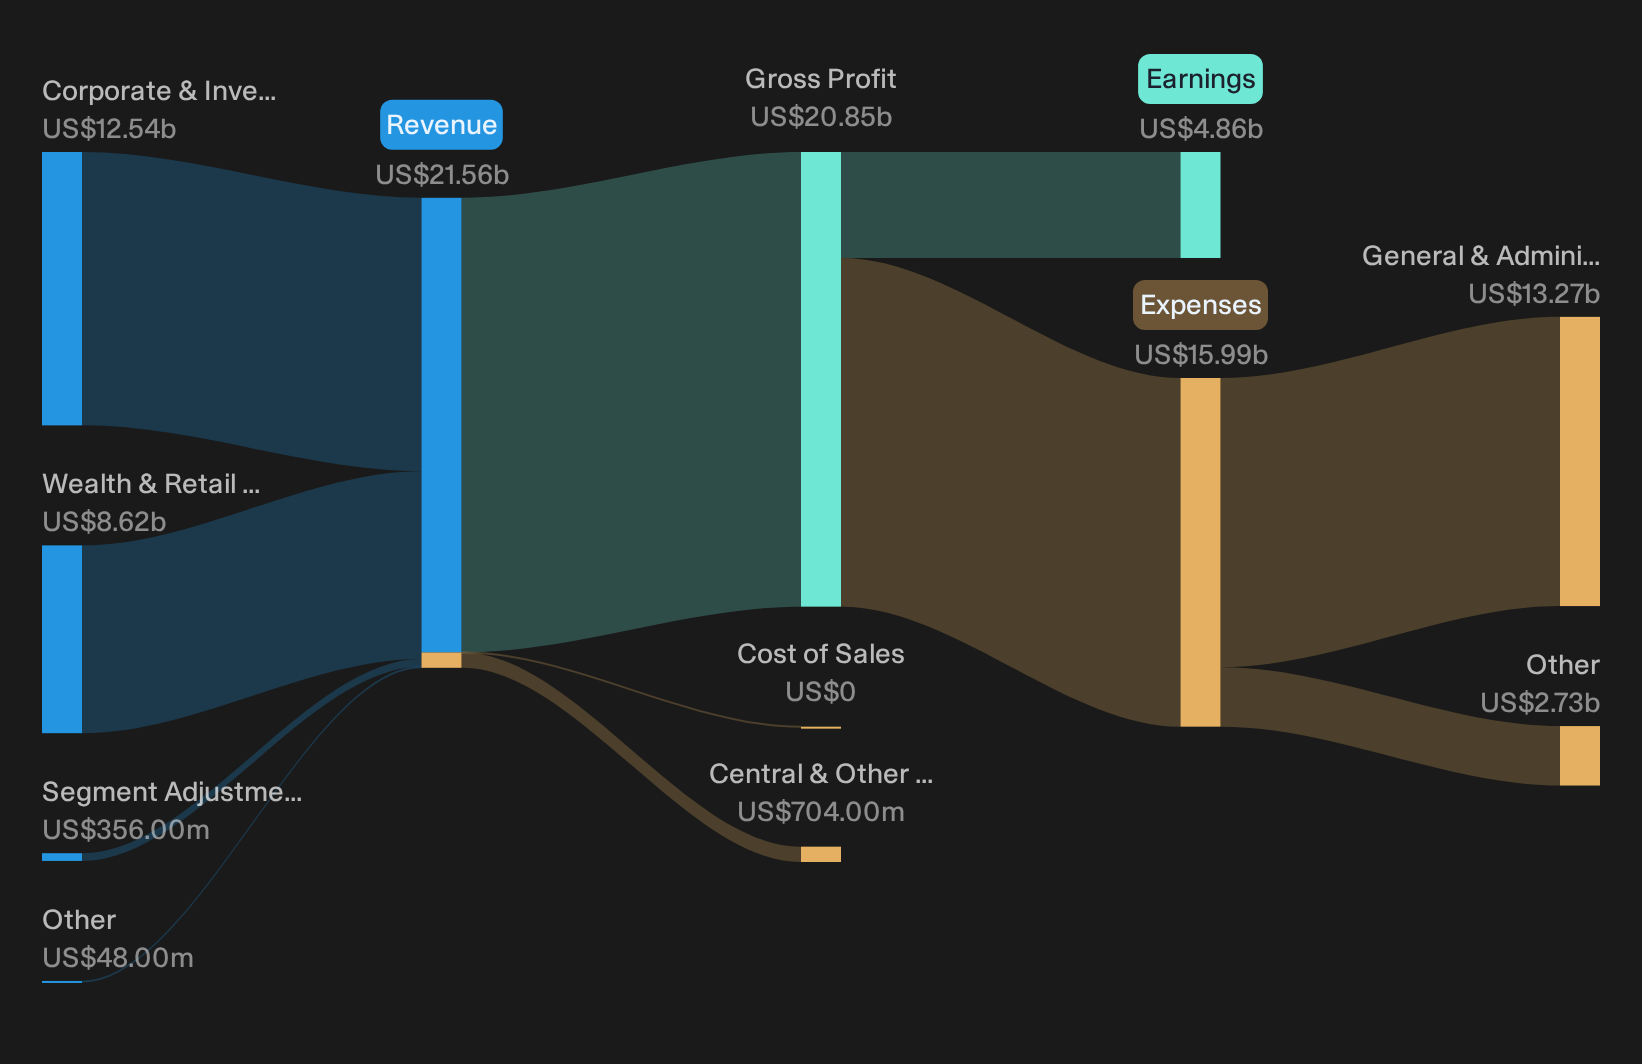
Q3 2026 Earnings Summary
- Total Revenue, Q3 2026 vs Q3 2025: US$5,691m vs. US$4,915m (up about 15.8%)
- Net Income, Q3 2026 vs Q3 2025: US$2,042m vs. US$1,028m (up about 98.7%)
- Basic EPS, Q3 2026 vs Q3 2025: US$0.701 vs. US$0.445 (up about 57.5%)
- Non Performing Loans, Q3 2026 vs Q3 2025: US$5,705m vs. US$5,597m (up about 1.9%)
Earnings grabs the headline, but valuation work often starts with hard cash flowing through the business. Standard Chartered’s reported profit is one view; its cash generation can tell you how much of that result actually shows up in the bank.
When you line up those cash flows against the current share price, the picture may look very different to the income statement. On this cash flow view, the stock could be a whopping 42% undervalued.
Standard Chartered’s Wealth Engine Clears a Key Hurdle
The bullish story hangs on fee engines carrying more weight as net interest income comes under strain, and Q3 gives you a clean checkpoint.
"Record income in Wealth Solutions, strong investment products growth, and consistent affluent net new money of US$42b year to date point to a growing fee based wealth franchise that can support income and earnings resilience even when net interest income is under pressure."
Standard Chartered just posted Wealth Solutions income of $1.1b, its third straight quarter above $1b, and lifted group non interest income to roughly half of total income. Net new money reached $52b year to date, ahead of the $42b cited in the original bullish case, while NII guidance sits at about 4% growth. That combination shows the wealth and markets engines are now doing more of the heavy lifting that narrative demanded.
The price and this Narrative do not agree. → Uncover what this Narrative says Standard Chartered is actually worth.
Standard Chartered: Efficiency Fears Meet New Cost Targets
Bears argue that Standard Chartered is stretching for higher ambitions while cost discipline slips, so the real test is whether expenses are drifting off plan.
"The bank is investing heavily in AI, digitisation and the digitisation of money while also running a large Fit for Growth restructuring programme. If execution slips or benefits arrive later than planned, operating expenses could stay elevated and compress net margins."
Q3 shows operating expenses rising 9% year on year, which gives that concern some bite. Yet management has now pinned guidance to a cost to income ratio of about 60% in 2026 and roughly 57% by 2028, setting explicit milestones that future quarters will confirm or challenge.
Hunt For Mispriced Earnings Power
Standard Chartered reports a strong quarter alongside a recent softer share price. The real opportunity is finding stocks that may be undervalued before the market corrects them.
- Company 1 - 23% below our estimate - turns a record long cycle order book and new autonomous programs into higher volume defense platforms.
- Company 2 - 31% below our estimate - expands fee income by raising capital into tax efficient products focused on renewables, social projects and digital infrastructure.
- Company 3 - 25% below our estimate - adds new copper and polymetallic projects that lift output once permits and development milestones are met.
Three companies from the same screener. Open all 10 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com