


Zoetis has had a tough run on the market in recent years, which naturally raises the question of whether the current share price lines up with what the business earns. With the stock now trading around US$77.80, investors are asking if those earnings still justify today’s valuation.
- Over the last 5 years, Zoetis has fallen 61.1%, which puts the spotlight firmly on whether its earnings can support even the lower share price.
- The recent FDA approval of Convenia RTU for Dogs may support expectations for future earnings, since it could strengthen Zoetis' position in veterinary antibiotic treatments handled directly in clinics.
- Your read on Zoetis is one view; the desks covering it have another. See what analysts think Zoetis's shares could be worth.
The issue now is whether Zoetis' current price can be explained by its earnings when measured against the Fair Ratio benchmark.
If you are considering Zoetis after this earnings-focused sell-off, it may be useful to compare it with a broader group of companies screened for 29 high quality undervalued stocks
Is Zoetis Still Cheap on Earnings?
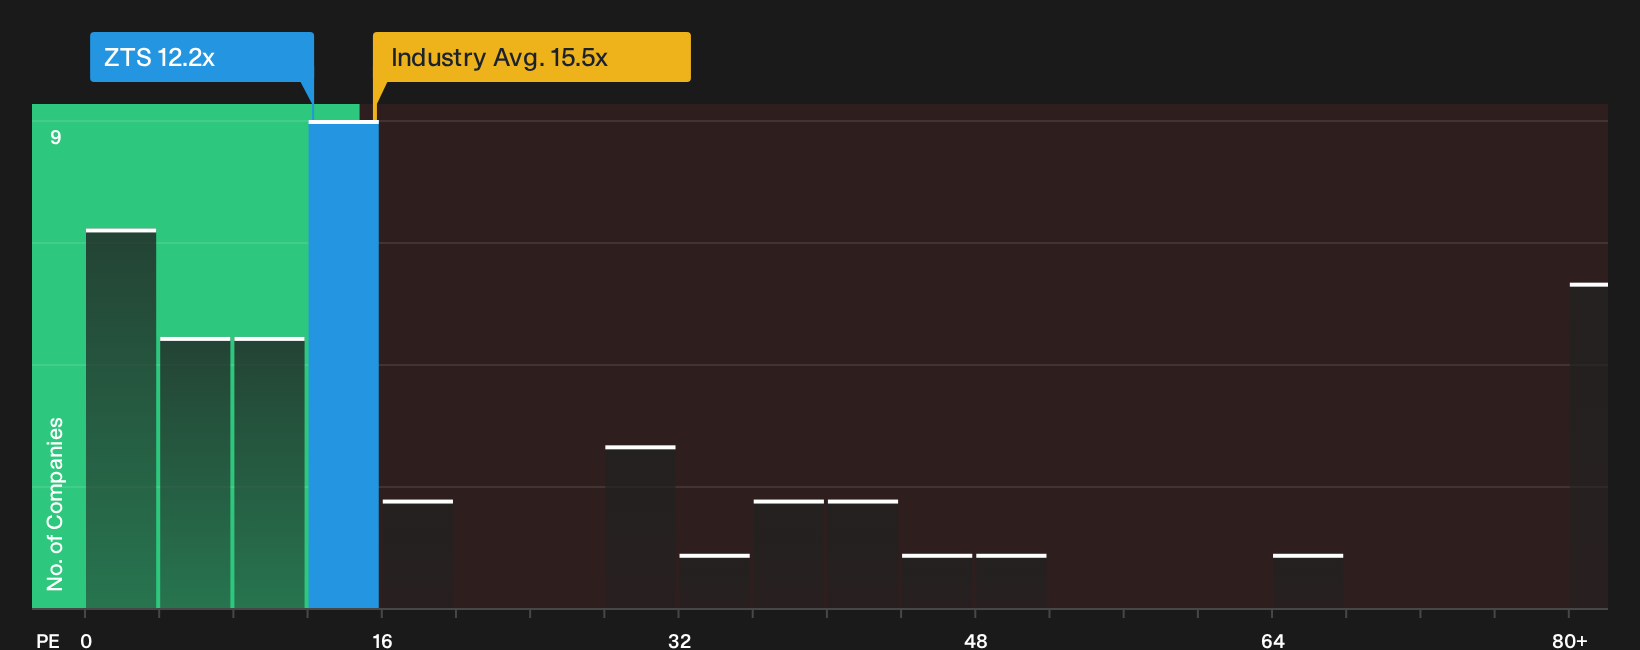
The P/E ratio is usually a straightforward way to see what you are paying for each dollar of profit at a company like Zoetis. On this measure, Zoetis trades on a P/E of 12.2x, compared with about 15.5x for the wider Pharmaceuticals industry and 32.2x across its peer group. Because the Fair Ratio framework suggests a richer multiple would typically be expected for a business with Zoetis' profile, the stock currently prices in a discount rather than a premium on earnings.
Because the recent FDA approval of Convenia RTU for Dogs is a concrete product milestone, the fact that Zoetis still trades below both its Fair Ratio signal and peer P/Es suggests the market is not assigning a high earnings multiple for that new opportunity. For you as a shareholder or potential buyer, the key question is whether its current earnings power and product portfolio justify a P/E closer to those higher benchmarks, or whether the present discount is warranted. Explore the numbers behind Zoetis's P/E valuation.
The Zoetis Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Zoetis valuation puzzle leaves off by spelling out what would need to happen to future growth, profitability and earnings for the current share price to look materially higher or lower. Each one links its number to a specific view on where Zoetis' expansion, margins and key risks go next, giving you a concrete story you can revisit as fresh information comes through.
Community views on Zoetis split between investors who see a resilient animal health leader on sale and those who focus on pipeline execution risk and competition.
Bull case: 16% undervalued
"Being the Pfizer of animal health, Zoetis is able to command pricing power from its fragmented global network of vet clinics and raise prices by about 4% per year..."
Discover why this Narrative puts Zoetis at 16% undervalued.
Bear case: 5% overvalued
"Although Zoetis highlights roughly 12 potential blockbuster candidates and positions renal disease as a roughly US$3b opportunity, the latest quarter showed global revenue of US$2.5b that was flat on a reported basis and down 1% organically with adjusted net income down 2% organically..."
Explore why this Narrative puts Zoetis at 5% overvalued.
One more Zoetis check that sits alongside the P/E story
The last missing piece is what professional analysts think Zoetis might be earning a few years from now, and how that picture lines up against the price you see today. Explore where analysts expect Zoetis to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com