


Independent Bank entered its Q3 2026 report wearing the value badge, trading on an 11.3x P/E and offering a 3.03% dividend yield, with the stock roughly flat over the past month and slightly weaker over 90 days. The headline this quarter is simple. Earnings held solid at US$0.81 per share and net interest margin printed at 3.82%, yet the share price slipped 0.6% on the day. That small dip reflects how loan growth and margin expansion are quietly reshaping this regional lender’s earnings power.
Love the 3.82% net interest margin at Independent Bank but concerned that a flat share price and modest earnings move might signal limited upside in this regional lender peer group. Take a look at our list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$66.26m vs. US$55.31m (up about 19.8%)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$17.85m vs. US$17.50m (up about 2.0%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.81 vs. US$0.85 (down about 4.6%)
- Net Interest Margin (Q3 2026 vs. Q3 2025): 3.82% vs. 3.54% (higher margin level)
Tired of scrolling through dense earnings tables and raw figures for Independent Bank? See the full picture in a clean visual layout, including how its valuation compares, inside the company report for Independent Bank.
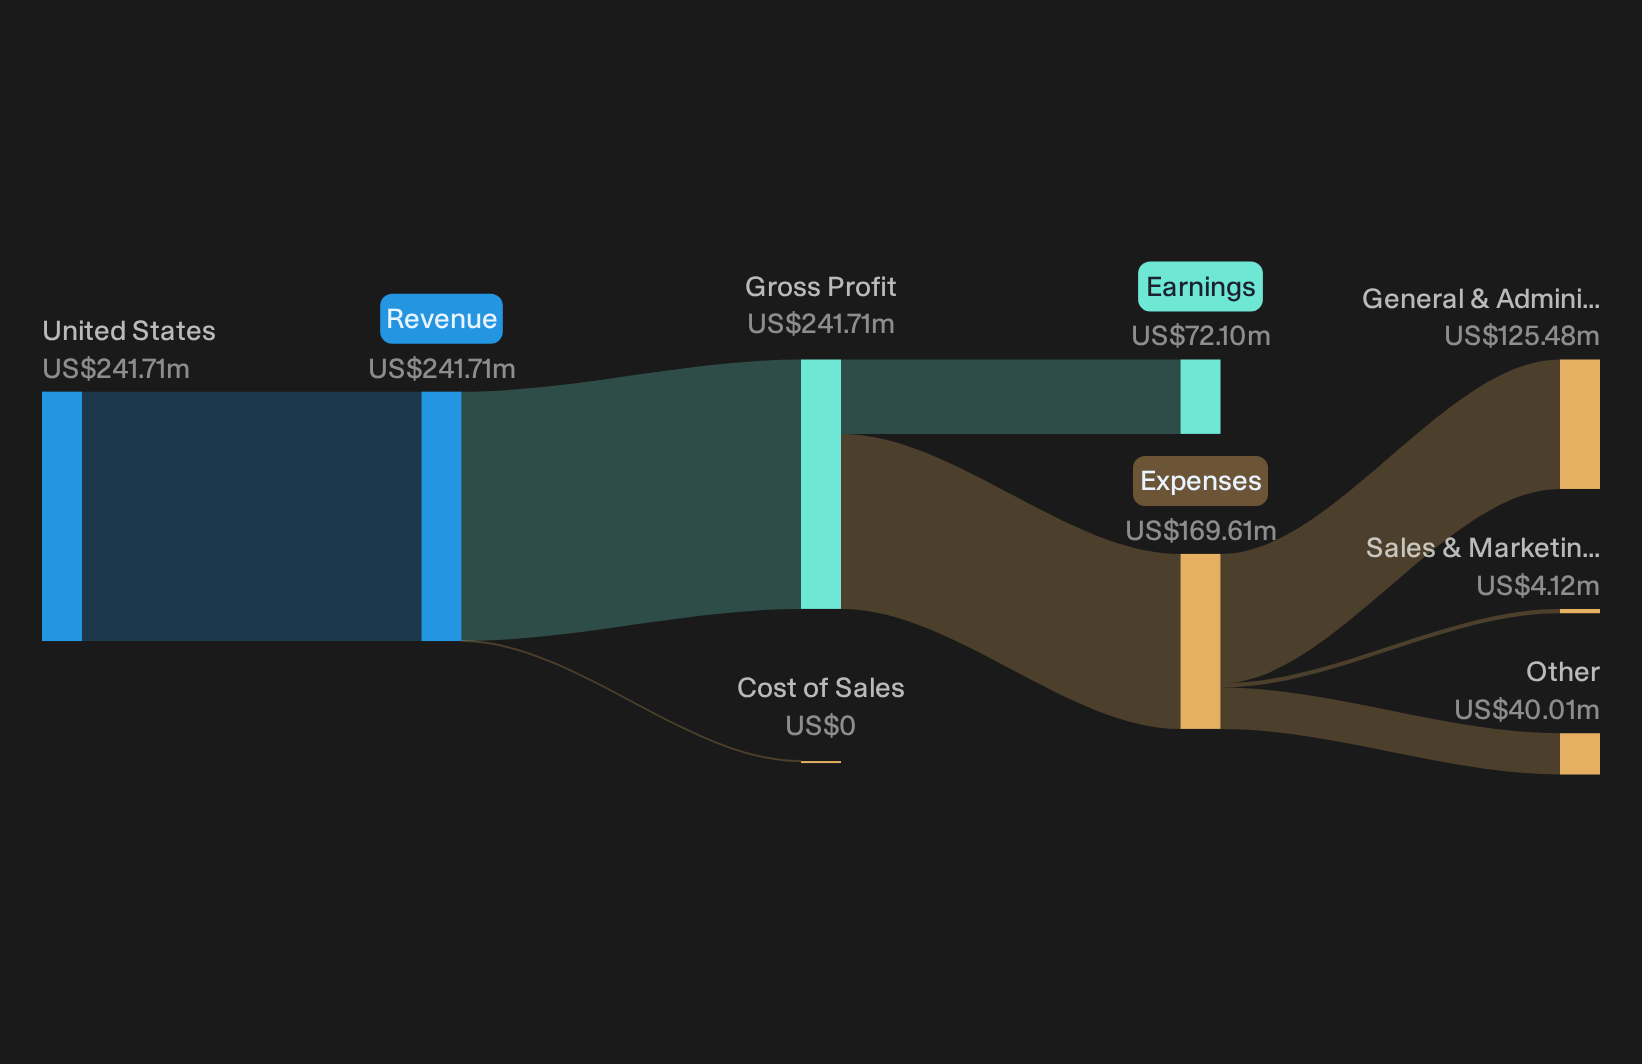
Independent Bank’s Growth Story Meets Hard Evidence
The bullish story on Independent Bank rests on hiring and remixing the balance sheet to lift net interest income without breaking its funding model.
"Ongoing hiring of experienced commercial bankers, with management referencing a total of 53 bankers and low double digit commercial loan growth targets, points to further relationship driven loan expansion that can support revenue and net interest income."
Q3 results line up with that ambition. Total loans rose US$483.1m including Highpoint, with organic net growth of US$116.6m and commercial categories rising about 21% annualized. Net interest income increased 21.8% year on year, while tax equivalent margin reached 3.82% or 3.76% excluding purchase accounting.
Credit And Cost Risks Keep The Brakes On
The bear story focuses on credit concentration and rising overheads potentially eroding the uplift from margin and loan growth.
"Nonperforming loans have risen from US$23.1 million, equal to 0.54% of loans, to US$32.8 million, equal to 0.74% of loans, with roughly two thirds tied to a single commercial development exposure that is still unresolved."
That concern is still live. Nonperforming loans are now US$39.2m or 0.80% of loans, with the same waterfront development in bankruptcy and carrying a specific reserve. Noninterest expense is US$44.8m including US$3.5m of merger costs, keeping the efficiency ratio at 61.3% and tempering earnings leverage.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt For Quietly Mispriced Stocks
Independent Bank just showed how a solid quarter can align with only a muted share move. The real opportunity could sit in stocks that look mispriced before sentiment and valuations adjust.
- Company 1 - 40% below our estimate - builds new production and supply capacity to feed higher margin film and installation channels.
- Company 2 - 43% below our estimate - expands a payment platform that helps large merchants handle rising local and cross-border transactions.
- Company 3 - 46% below our estimate - converts a large backlog of complex projects into work where contract wins and dispute resolutions release cash.
Three companies from the same screener. Open the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com