


Taaleri Oyj stock has been grinding lower in recent weeks, down about 2% over seven days and roughly 3% across the past quarter, even as the latest Q2 2026 report put fresh numbers on the table. The focus is on earnings power. Basic earnings per share came in at about €0.13 on revenue of €13.6 million, backed by a trailing net margin near 31% and a P/E ratio of 10.7 that sits well below peers.
If you are only watching the share chart, this can look like a sleepy Finnish financial. The longer view, built on multi year earnings forecasts and a discounted cash flow estimate at almost 2.5 times the current €7.16 price, presents a more charged valuation picture.
Like the earnings power at Taaleri Oyj but wondering if you could find similar margins with even stronger perceived value support? Check out our list of steady balance sheet stocks in the list of solid balance sheet and fundamentals stocks (207 results)
Q2 2026 Earnings Summary
- Revenue (Q2 2026 vs Q2 2025): €13.57 million vs €13.48 million (effectively flat year on year)
- Net Income, Excl. Extra Items (Q2 2026 vs Q2 2025): €3.54 million vs €1.88 million (strong increase in quarterly profit)
- Basic EPS (Q2 2026 vs Q2 2025): €0.13 per share vs €0.07 per share (clear uplift in earnings per share)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 31.0% vs 32.3% (slight margin compression on a yearly basis)
Taaleri is betting on a fresh private credit strategy. Ask Charlie what Taaleri’s new private credit push really changes.
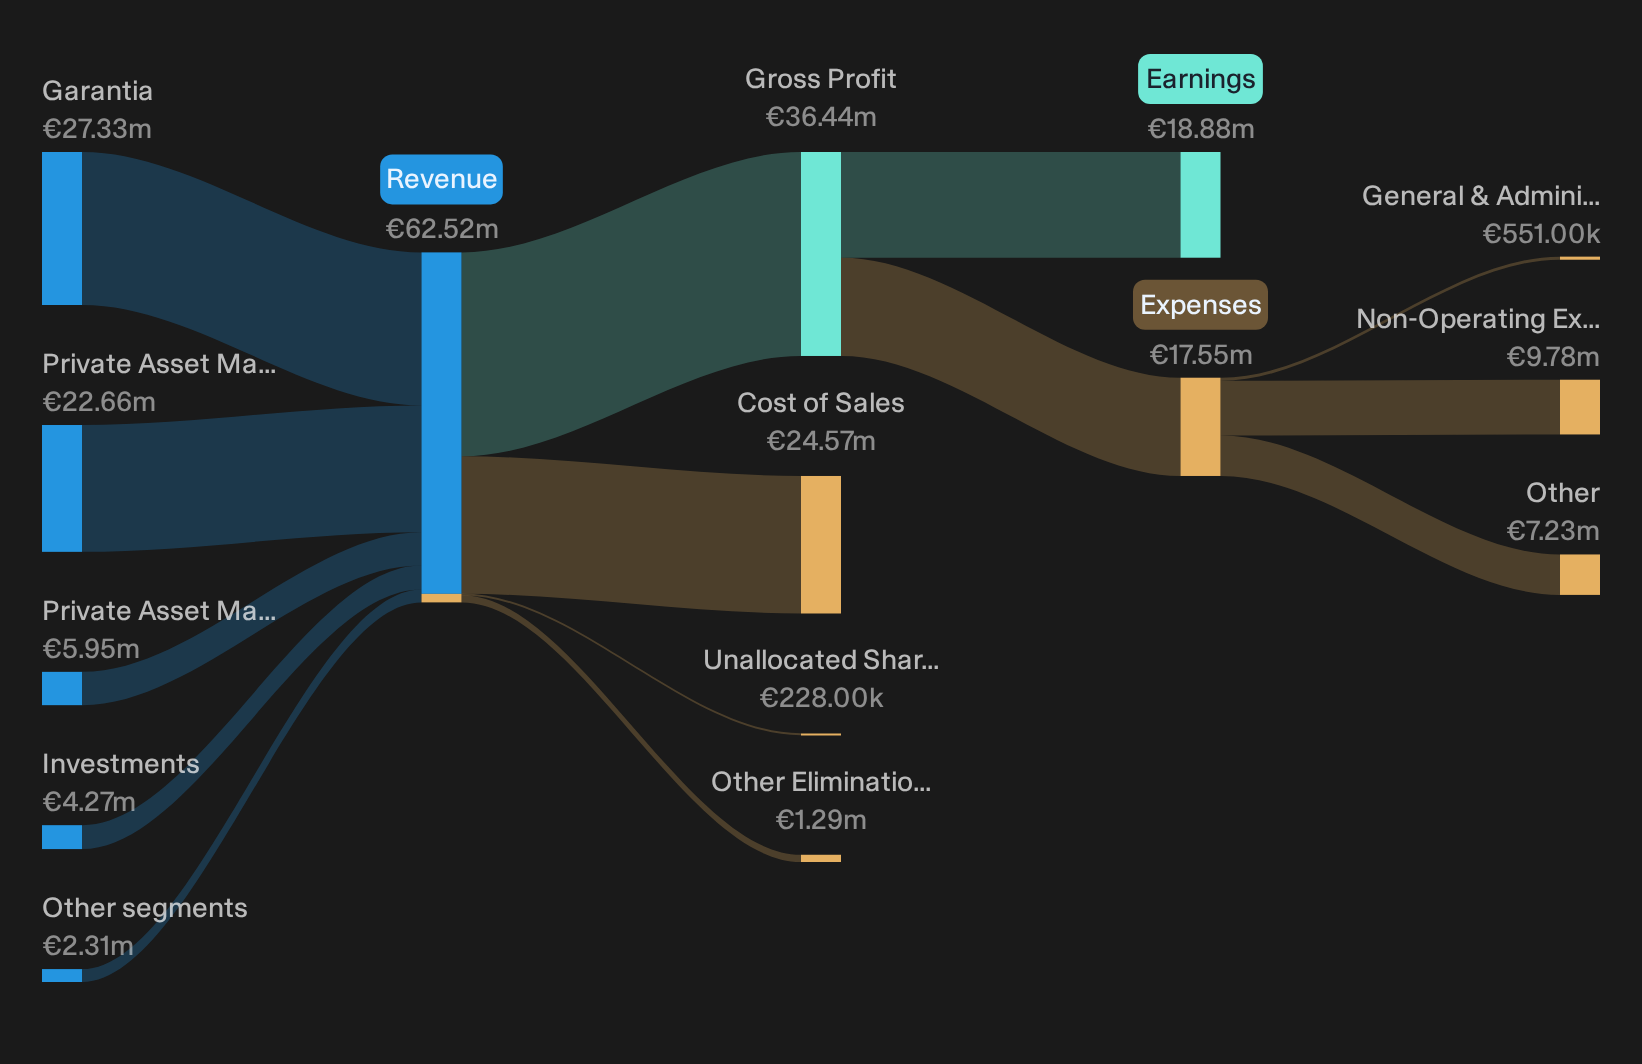
Taaleri bullish story meets early earnings proof
The upbeat view hangs on newer engines like private credit and bioindustry pulling more weight in Taaleri Oyj’s recurring profit mix.
"Further broadening of Taaleri Oyj’s Private Asset Management platform into venture capital and Nordic private credit through Nordic Science Investments and the planned credit strategy, including larger follow-on vintages after the first €45 million fund, can expand fee earning assets and increase recurring management revenue."
Q3 shows that thesis starting to materialise. Nordic Science Investments is consolidated, venture investments are active and delivered a €1.2m performance fee. Management has also hired a four person private credit team, with a launch date for Taaleri Private Credit set for November 2026.
Bearish fair value risk still evident in Taaleri results
The cautious view argues that development bets could chip away at earnings through write downs and valuation swings.
"Capital deployed into newer bioindustry projects and funds can misfire, as shown by the Joensuu Biocoal write downs and the related decision to discontinue the Canadian project, which together reduced results in early 2026 and signal a risk that further development capital investments may generate additional impairments that weigh on net margins and earnings."
Recent numbers partly echo that concern. Renewable Energy operating profit felt the impact of a reduced unrealized performance fee balance. Fair value on Turun Toriparkki moved lower, and earlier write downs in projects like Joensuu Biocoal still frame investor memory around impairment risk.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt For Mispriced Earnings Power
Taaleri Oyj illustrates how a detailed quarterly report and a drifting share price can diverge in message. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 42% below our estimate - targets cloud providers racing to secure high density AI power capacity beyond constrained sites.
- Company 2 - 31% below our estimate - shifts its mix toward composite cylinders and clean energy equipment as automation upgrades free capacity.
- Company 3 - 23% below our estimate - builds surgical robots doctors adopt when they move complex joint procedures into guided systems.
That is three of the list. See the full list of 195 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com