


Peab just released its Q3 2026 numbers and the headline is clear. Earnings per share landed at 3.50 SEK and net income reached 975 million SEK, while the stock closed at SEK96.05 after a flat to slightly soft month in the market. The focus today is on profitability. An improving margin story contrasts with investors who still remember weaker quarters earlier in the year, which makes the muted price reaction appear more emotional than data driven.
Like the earnings power at Peab but wary when sentiment keeps the share price pinned down after solid numbers? Compare this result with list of solid balance sheet and fundamentals stocks (207 results) to see how other financially robust businesses are being treated by the market.
Q3 2026 Earnings Summary
- Revenue, Q3 2026 vs. Q3 2025: SEK15,897 million vs. SEK15,358 million (up about 4%)
- Net Income, Q3 2026 vs. Q3 2025: SEK975 million vs. SEK829 million (up about 18%)
- Basic EPS, Q3 2026 vs. Q3 2025: SEK3.50 vs. SEK2.89 (up about 21%)
- Trailing Net Profit Margin, last 12 months vs. prior 12 months: 3.7% vs. 2.8% (improved profitability on recent earnings)
Earnings jumped while Peab still trades below peers on P/E. Ask Charlie what makes Peab look this cheap.
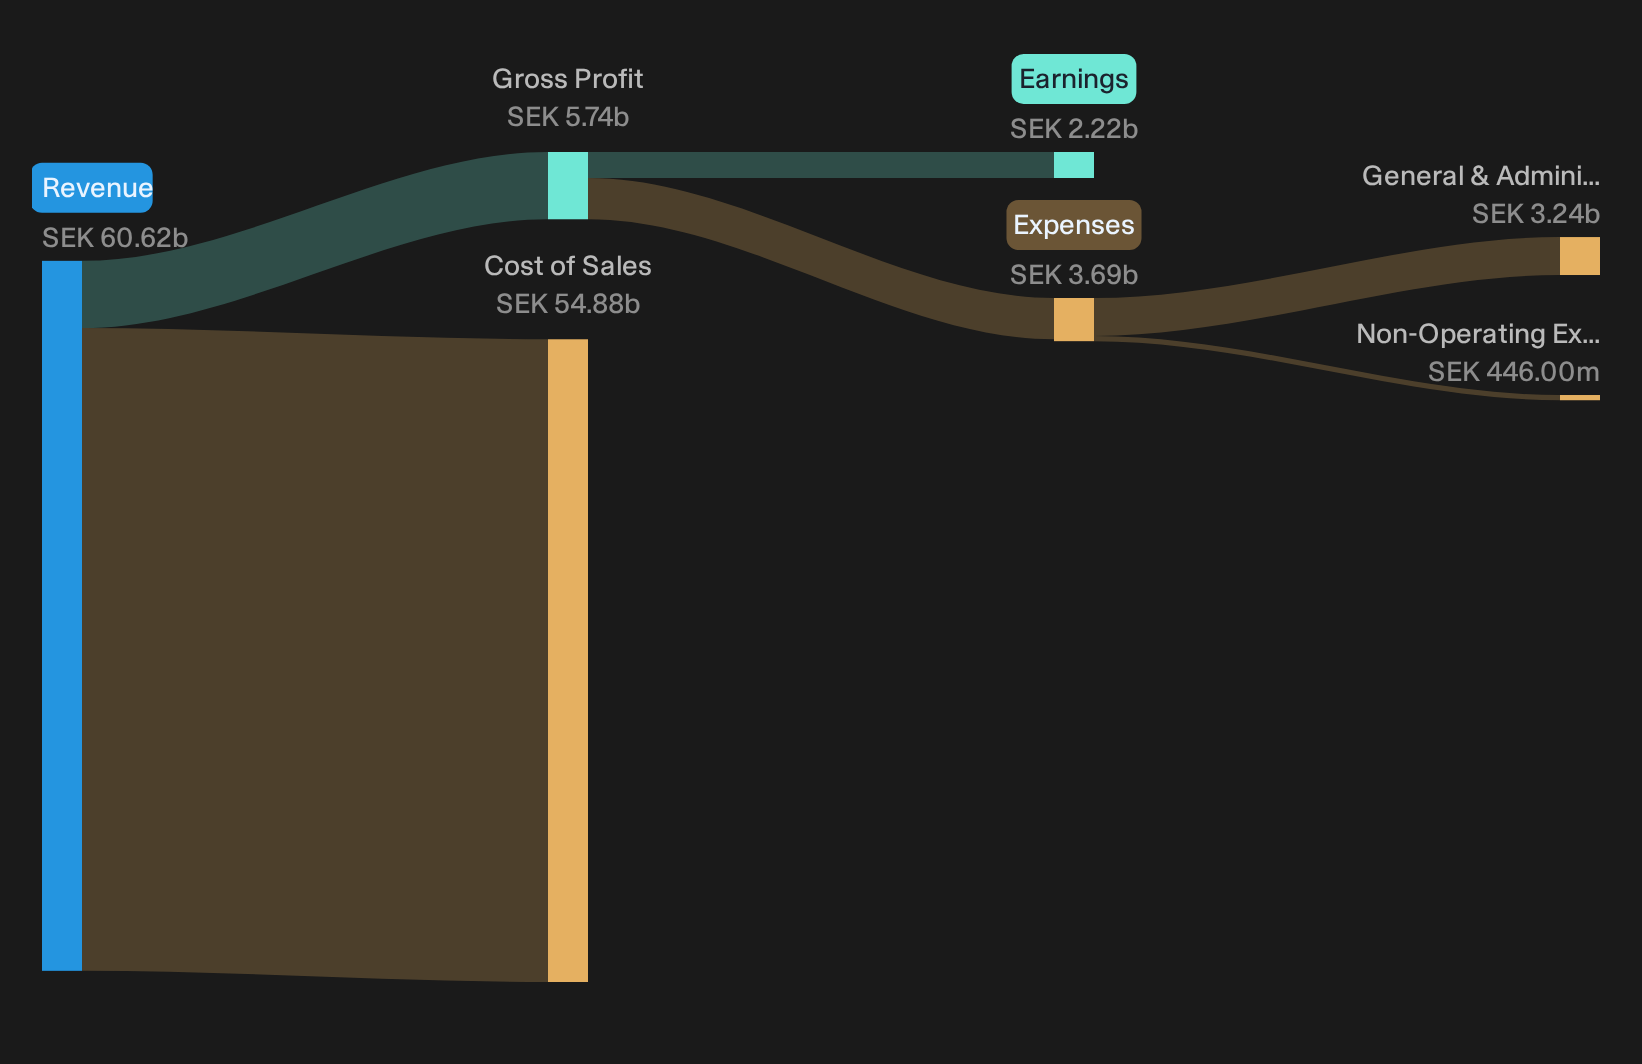
Peab earnings, margin trend backs cautious optimism
Peab looks better on the fundamentals than the flat share price implies. Revenue in Q3 2026 is modestly higher than Q3 2025, yet earnings move faster, with net income and EPS growing at a stronger clip. A higher trailing net profit margin of 3.7% versus 2.8% points to better pricing or cost control. For a construction and infrastructure group often viewed as cyclical, that kind of margin progression supports the idea that a diversified mix of civil projects, housing and industry can still generate improving profitability even when sentiment is lukewarm.
Bear risks soften as profitability improves for Peab
Bears usually focus on cyclical exposure and project risk. The latest figures do not remove those issues, yet they do soften them. Net income and EPS both advance faster than sales, which is hard to reconcile with a thesis built on sustained margin pressure. Trailing margin at 3.7% versus 2.8% also runs against worries about cost inflation eroding earnings. The share price drifting down about 4% over 30 days while profitability trends higher suggests the near term risk story rests more on macro caution than on immediate financial stress inside Peab.
Do analysts view Peab's improving profit margin as durable, or as temporary noise around the projects pipeline? Check the consensus price target analysis for Peab.
Hunt For Quiet Mispricings
Peab shows how earnings strength and a muted share price can drift apart for a while. The real opportunity is spotting stocks that could be undervalued before that gap closes.
- Company 1 - 48% below our estimate - expand a trading focused broker into a broader savings platform as client assets shift toward equities and ETFs.
- Company 2 - 22% below our estimate - convert underpenetrated food and grocery delivery habits into more frequent orders as households move everyday baskets online.
- Company 3 - 41% below our estimate - grow fee related earnings by guiding clients toward higher fee private market strategies and scaling real assets with balance sheet co investments.
Those are three of them. See all 199 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com