


SSH Communications Security Oyj walked into its Q3 2026 report with the share price at €1.80 after a weak month and a flat quarter, already reflecting some fatigue. Then the headline dropped. Revenue held at €5.7m while the quarter still produced a net loss of €0.6m, yet subscription annual recurring revenue in the core cybersecurity products kept climbing.
The stock reaction now looks caught between fear of ongoing losses and enthusiasm for recurring sales. Short term traders focused on red ink. Longer term holders are watching that subscription engine instead.
Love the rising subscription base at SSH Communications Security Oyj but concerned about the continuing quarterly losses? Check out our screener of companies that pair recurring revenue strength with cleaner income statements in the list of solid balance sheet and fundamentals stocks (207 results).
Q3 2026 Earnings Summary
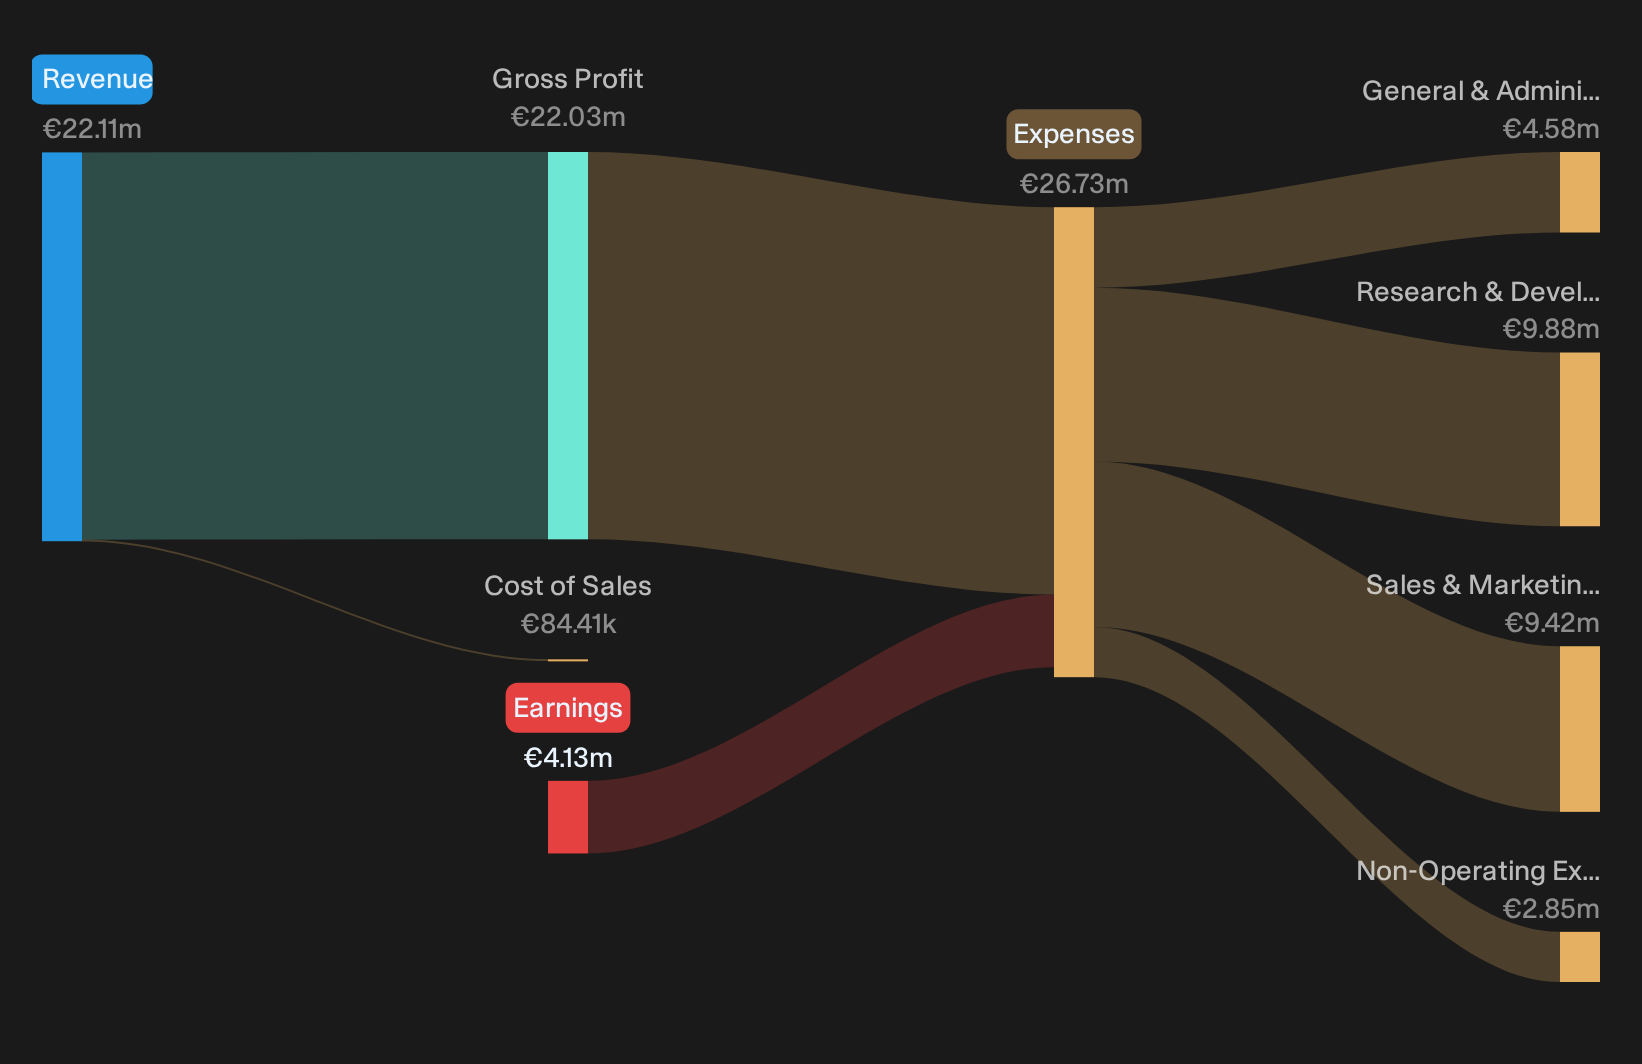
- Revenue (Q3 2026 vs. Q3 2025): €5.7m vs. €5.5m (up 5.3%)
- Net Loss (Q3 2026 vs. Q3 2025): loss of €0.6m vs. breakeven (€0m), moving back into a loss position
- Basic EPS (Q3 2026 vs. Q3 2025): loss of €0.010988 per share vs. loss of €0.02 per share (smaller loss per share)
- Subscription ARR (Annual Recurring Revenue, Q3 2026 vs. Q3 2025): €15.7m vs. €12.7m (up 23.6%)
SSH Communications Security ARR story under the microscope
SSH Communications Security Oyj bulls argue the product and go to market reset should turn subscription into a real engine, not just a slogan.
"Consolidation of product management, engineering and go to market under a functional structure, combined with increased analyst recognition for PrivX, can make sales efforts more efficient and support improved net margins if subscription ARR and multiyear deals continue to build on the current base of €14.6m in deferred revenue."
The latest quarter moves this thesis forward. Subscription ARR reached €15.7m and deferred revenue is now €14.4m, with €11.5m due within 12 months, while subscription sales grew 17.8% and PrivX climbed 33.9%. Net profit is still a loss, so margin improvement remains a work in progress.
Testing SSH Communications Security cost and partnership risks
Bears contend the Leonardo centric pipeline and heavier cost base could leave SSH Communications Security Oyj with rising ARR but stubborn losses.
"Expansion has required sizeable investment in people, with more than 20 hires across the U.S. and other regions and over 40% of resourcing spend going into R&D. If new sales do not scale fast enough, higher operating costs could keep EBIT in loss making territory and limit improvement in net margins."
Q3 supports part of that worry. Operating result stayed negative at €0.5m and EBITDA slipped to €0.3m while operating cash flow fell €0.7m. At the same time, invoicing rose about 39% and a roughly €3m, multi year Key Manager and PrivX contract started to contribute, which argues sales capacity is producing volume even if profitability has not yet caught up.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt For Mispriced Recurring Engines
SSH Communications Security Oyj just showed how rising subscriptions can coexist with ongoing quarterly losses. The real opportunity could sit in stocks that the market has not fully priced yet.
- Company 1 - 31% below our estimate - expands a multi affiliate fund platform that adds managers to grow fee earning assets across specialised strategies.
- Company 2 - 40% below our estimate - grows a beverage platform as coconut water moves from niche to mainstream and private label volumes scale through retail and foodservice channels.
- Company 3 - 18% below our estimate - sells software defined routers and licences that turn satellite and physical AI data needs into recurring connectivity and support contracts.
Those are three of them. See the full list of 199 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com