


Deutsche Bank just dropped its Q3 2026 scorecard and the headline is clear. Profit from ongoing operations stayed solid and group return on tangible equity landed at 10.6%. The equity price told a different story coming into the release, stuck around €30 after a flat week and a weaker 3 month stretch.
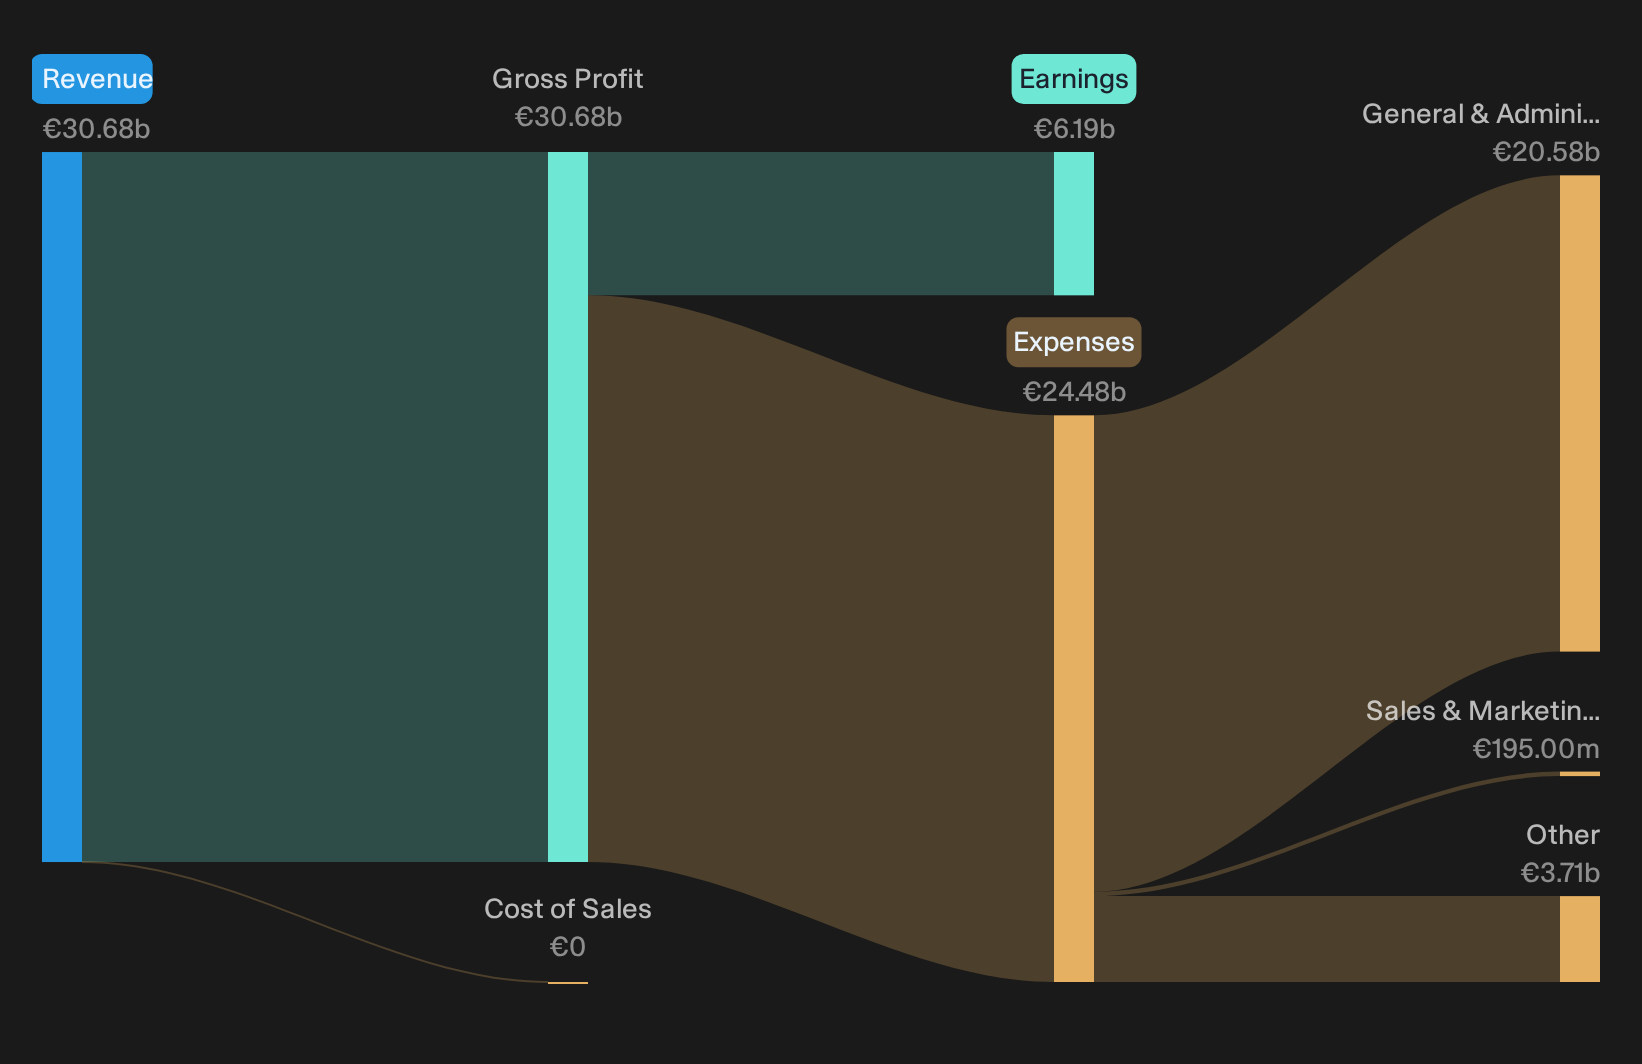
The real flashpoint today is profitability. Net income excluding one off items reached €1.8b for the quarter, backing up a trailing 12 month net profit margin of 20.2%. If the share move looks muted, the earnings profile does not appear to reflect a market already pricing in that level of profitability.
Love Deutsche Bank’s solid profit margin but unconvinced the flat share price reflects that earnings power? Compare this setup with our 195 high quality undervalued stocks
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): €7,836m vs. €7,626m (up about 2.7%)
- Net Income excl. Extra Items (Q3 2026 vs Q3 2025): €1,809m vs. €1,773m (up about 2.0%)
- Basic EPS (Q3 2026 vs Q3 2025): €0.96 vs. €0.91 (up about 6.2%)
- Trailing 12-Month Net Income excl. Extra Items (Q3 2026 TTM vs Q3 2025 TTM): €6,193m vs. €5,405m (up about 14.6%)
Deutsche Bank now calls a 13% RoTE just a floor. Ask Charlie what makes Deutsche Bank so confident about 2028 returns.
Deutsche Bank’s Bull Case: Execution Checkpoint
The optimistic view hangs on Deutsche Bank turning restructuring, asset gathering and AI into a higher quality earnings engine rather than a one off profit story.
"The scale of assets under management gathered so far, combined with continued net inflows across the Private Bank and DWS, gives Deutsche Bank scope to introduce more fee rich investment products and advisory tiers that lift recurring commission income and support earnings quality."
Q3 hits several waypoints. Record net new flows of €17b into the Private Bank and €31b at DWS push client assets to roughly €2.2b. Group revenues reached €8.3b with 9M at €25.5b. Fee driven businesses in the Private Bank, Asset Management and Corporate Bank all delivered higher year on year revenue, pointing to real progress on the fee quality ambition.
One Narrative disagrees with today's price. → See where this Narrative says Deutsche Bank should trade.
Deutsche Bank: Controls And Legal Drag Not Yet Cleared
Bearish investors worry that Deutsche Bank’s cost base will stay heavy because control and reporting issues keep resurfacing.
"As the group shifts toward capital light fee and asset gathering businesses and advertises a more diversified earnings mix, additional regulatory penalties such as the recent fine for misreporting OTC derivative transactions point to unresolved operational and reporting weaknesses that can keep noninterest expenses structurally higher and reduce the benefit of fee income growth on overall profitability."
Q3 cost/income around 61 to 62% and reiterated 2026 expense guidance of €21.3b show spending broadly contained, not spiralling. Yet fresh conduct headlines and ongoing investigations mean the feared structural legal and remediation drag is not disproved by this quarter.
Hunt For Quiet Earnings Disconnects
Deutsche Bank just showed how a steady profit story can exist with a flat share price. The real opportunity is spotting stocks that could be undervalued before any market repricing.
- Company 1 - 44% below our estimate - uses a single integrated platform to cut costs and steer customers toward higher fee offerings in payments, wealth and insurance.
- Company 2 - 42% below our estimate - sells oncology planning software that connects with rival hardware and converts one off licenses into AI assisted recurring contracts for more complex treatments.
- Company 3 - 48% below our estimate - supplies power and connectivity systems that integrate as customers scale AI data centers and semiconductor equipment programs, increasing exposure to higher value projects.
Three companies from the same screener. Open every one of the 195 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com