


Essential Utilities (WTRG) just affirmed its income story. The board approved a quarterly cash dividend of $0.3606 per share, payable on December 1, 2026, to shareholders of record on November 10.
Essential Utilities' latest dividend decision follows a period of improving momentum, with a 30-day share price return of 8.5% and a year-to-date share price gain of 9.31%, contributing to a 1-year total shareholder return of 11.89%.
Scan the wider utilities space by comparing Essential Utilities with a curated 30 resilient stocks with low risk scores that focus on resilience, regulated earnings, and steadier dividend profiles.
After an 8.5% rise over 30 days and a 1-year total return of 11.89%, Essential Utilities now asks a simple question of holders and new buyers alike: Does the current valuation still leave enough upside for the risk taken?
Preferred P/E of 21.6x: Is it justified?
On valuation, Essential Utilities currently trades on a P/E of 21.6x, which prices the stock above the global water utilities average but slightly below its direct peer group and above an estimated fair P/E level.
The P/E ratio compares the share price to earnings per share and is a common way investors gauge how much they are paying for each dollar of profit. For regulated utilities like Essential Utilities, this metric often reflects expectations around predictable cash flows, allowed returns on capital, and the stability investors are willing to pay for in exchange for lower volatility.
In this case, the picture is mixed. Essential Utilities is described as expensive versus the global water utilities industry, which runs at 16.2x P/E, yet it screens as better value against its closer peer set that trades at about 24.5x. The stock also sits above an estimated fair P/E of 19.2x, a level the market could move toward if sentiment around earnings quality, growth of around 7.4% a year, or balance sheet risk changes.
Explore the SWS fair ratio for Essential Utilities.
Result: Price-to-earnings of 21.6x (ABOUT RIGHT)
Still, the Essential Utilities story can be knocked off course if regulators squeeze allowed returns, or if funding its roughly US$12.1b valuation becomes more expensive.
Find out about the key risks to this Essential Utilities narrative.
Another view on Essential Utilities valuation
Price tells one story; cash flows often tell another. While the P/E points to Essential Utilities trading a little rich against its fair ratio of 19.2x, the SWS DCF model suggests a different angle, with the share price of $42.27 sitting about 3.7% below an estimated future cash flow value of $43.91. That raises a simple question for investors: Which signal deserves more weight when the income stream looks steady but the multiples look full?
Look into how the SWS DCF model arrives at its fair value.
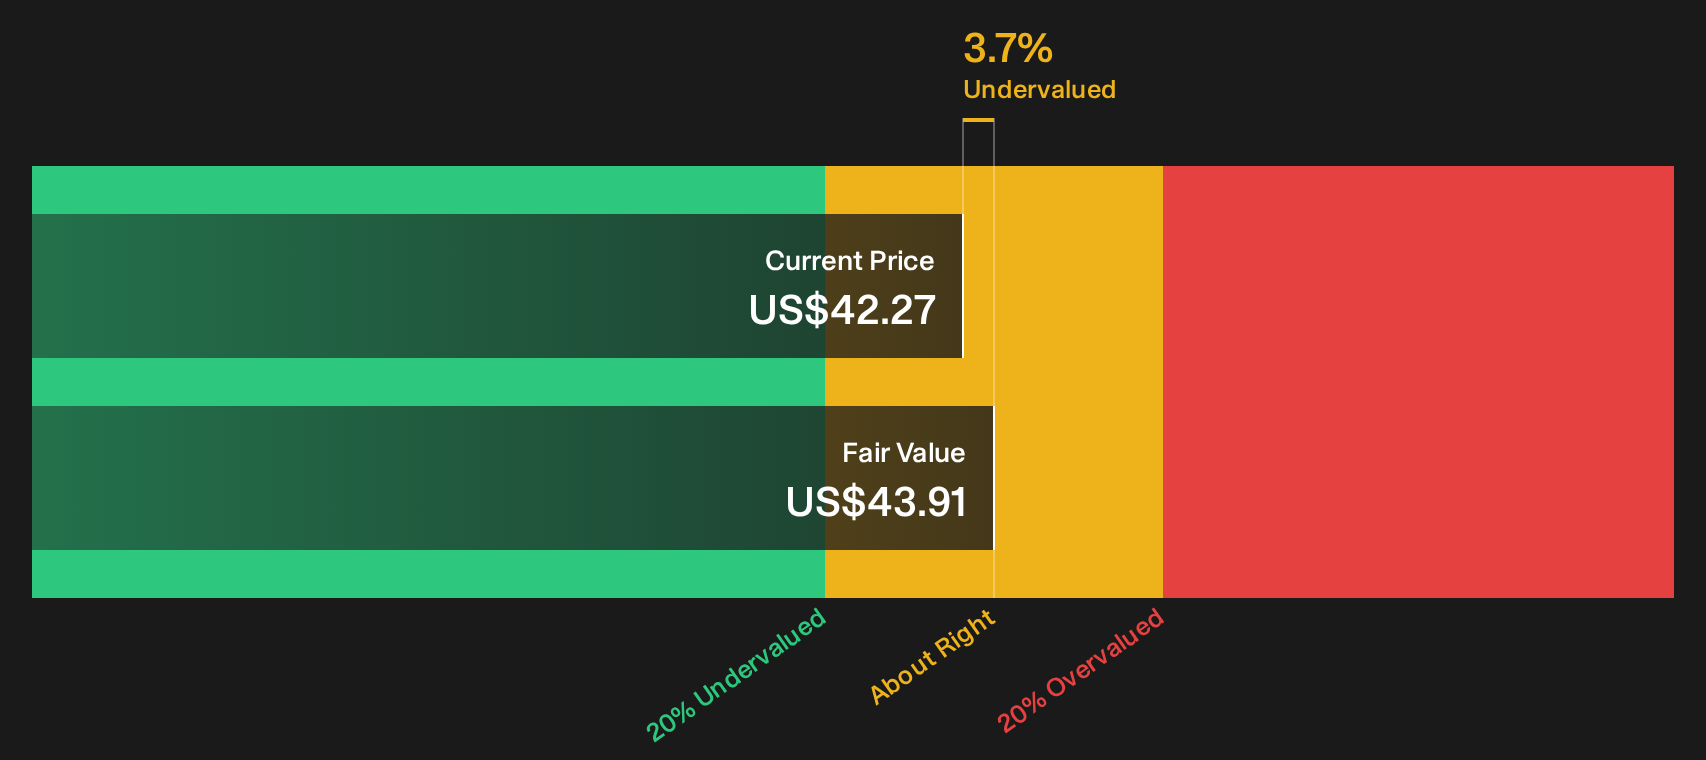
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Essential Utilities for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Essential Utilities valuation can feel confusing. Move quickly from headline impressions to your own judgment by weighing both the upside case and the risk side through the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Essential Utilities?
If Essential Utilities sharpened your focus on income and resilience, do not stop here. Use the Simply Wall Street screener to surface fresh candidates that match your risk and return preferences.
- Target steadier compounding by reviewing companies with robust financials and durable balance sheets through the list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a potentially appealing entry point by scanning a curated 29 high quality undervalued stocks that already filters for fundamentals.
- Build a broader watchlist of potential income pillars by assessing a focused 6 dividend fortresses that screens for higher yielding payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com