


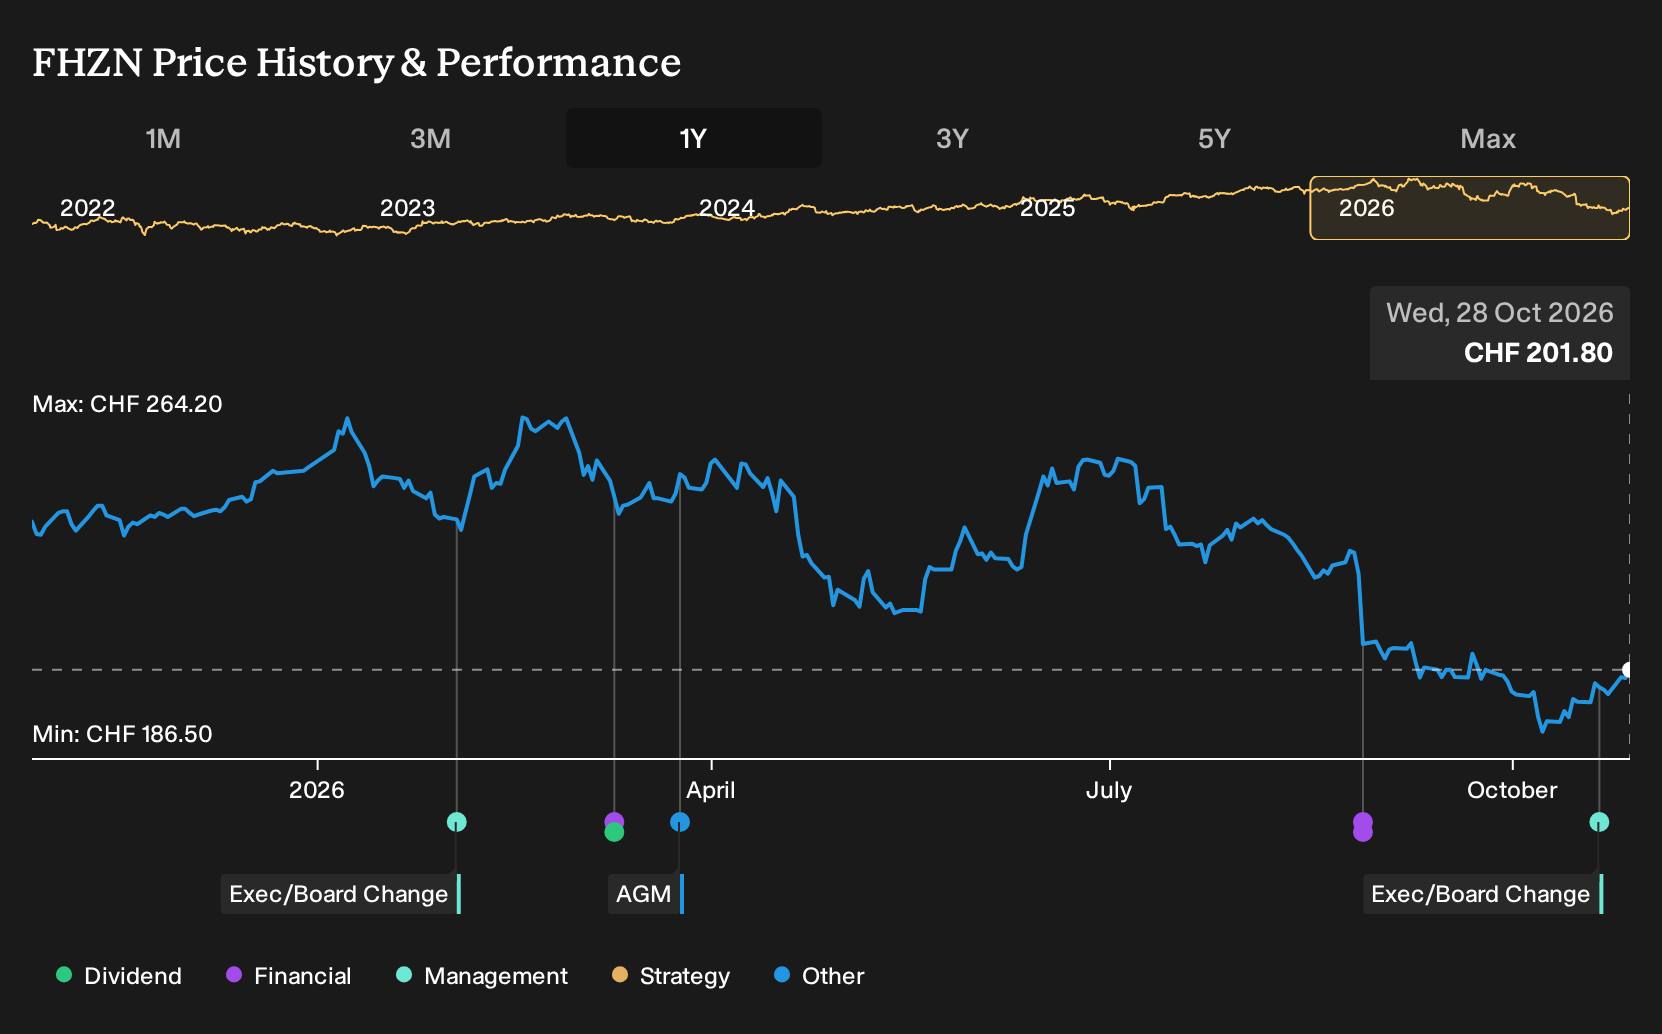
- Zurich Airport Ltd. has outlined Executive Board changes for 2027, including the departure of COO Stefan Tschudin, the move of CCO Stefan Gross to Noida International Airport, and the expansion of Lydia Naef’s remit to cover all non aviation activities as Chief Commercial Officer.
- The reorganisation concentrates non aviation, real estate and construction responsibilities into clearer divisions, which reshapes how Flughafen Zürich manages capital expenditure intensive building projects and commercial revenue streams across the airport campus.
- We will now examine how Flughafen Zürich's investment narrative could shift as Lydia Naef assumes wider non aviation responsibility from 2027.
Flughafen Zürich Investment Narrative Recap
To own Flughafen Zürich, you need to believe the regulated Swiss hub, the higher margin non aviation activities and the international concessions can together support steady earnings while heavy construction and capex roll through. The short term swing factor still sits in execution on Zurich infrastructure projects and early returns from Noida and Brazil rather than this board reshuffle.
The 2027 management changes look more like housekeeping around how the non aviation engine and building projects are organised. They do not alter the known pressure points such as upcoming charge reductions, high debt, heavier depreciation and interest from Noida or a dividend that is not fully backed by free cash flow.
The most relevant recent development tied to this reorganisation is the opening of Noida International Airport in June 2026, which is expected to post negative EBITDA in its early years. With the current Chief Commercial Officer moving across as Executive Chairman, operational focus around passenger ramp up and cost control at Noida becomes even more visible for Flughafen Zürich.
Noida is already forecast as a drag on group profit, with slower passenger ramp and around CHF 80m of annual depreciation and interest from that project flagged as a risk. The new Executive Board set up, including a dedicated Buildings & Constructions division, will be tested on delivery discipline, cost containment and keeping leverage in check while Zurich capex runs at around CHF 400m for 2026.
Flughafen Zürich's narrative projects CHF 1.5b revenue and CHF 348.0m earnings by 2029. This is based on 3.3% yearly revenue growth and a small earnings decline of about CHF 0.9m from CHF 348.9m today.
Uncover how Flughafen Zürich's fair value indicates a 21% potential upside to its current price that could narrow quickly if sentiment improves around Flughafen Zürich's non aviation earnings mix.
Exploring Other Perspectives
Simply Wall St Community members offer three fair value views for Flughafen Zürich, ranging from about CHF 157 to CHF 300, which shows how wide opinions can run. Set that beside risks like charge reductions and heavy capex for Zurich and Noida, and you are looking at genuinely different stories about future resilience.
Explore 2 other Flughafen Zürich fair value estimates, including one that suggests as much as 22% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Flughafen Zürich research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Flughafen Zürich. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flughafen Zürich's overall financial health at a glance.
Looking for more Flughafen Zürich investment ideas?
If the Flughafen Zürich story has sharpened your thinking about earnings quality, capital intensity and risk, it can be helpful to test that same framework on a broader watchlist using the Simply Wall St Screener.
- For investors who care most about quality and valuation together, scan for companies with strong fundamentals and room for re rating through the 196 high quality undervalued stocks.
- If capital preservation and stability matter more to you than chasing headline growth, filter for companies that score well on resilience using the 223 resilient stocks with low risk scores.
- When you want to go beyond well known tickers, focus on lesser known businesses with robust financials by running the 608 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com