


With the Bank of Canada lifting interest rates again and warning that borrowing costs could climb further, cash has suddenly become king for many Canadian companies. Strong, predictable cash generation can help a business handle pricier debt and still reinvest for growth. This article looks at three Canadian stocks that SWS flags as trading below their estimated cash flow value, so you can spot potential bargains hiding in plain sight.
The three stocks highlighted next are only a sample of what the full screen turned up, with 4 more companies showing similarly interesting cash flow profiles and valuation gaps that are not covered below. To see the broader field and identify your own highest conviction ideas, go straight to the Undervalued Stocks Based On Cash Flows screener
OceanaGold (TSX:OGC)
OceanaGold is a mid sized producer that turns a portfolio of operating gold and gold copper mines into the cash flows this screener is built around. This is why its current market pricing has caught the eye of value focused investors.
OceanaGold runs producing gold and gold copper mines in the U.S., the Philippines, and New Zealand, with revenue anchored by Haile at about $796 million, Macraes at $781 million, Didipio at $549 million, and Waihi at $338 million, and the stock valued at roughly $8.1b today.
"Optimization and expansion at Didipio, including restoration of normal underground rates and a targeted 2.5 million tonne annual mining rate by 2026, should increase copper and gold output from an already low cost asset, enhancing consolidated cash flow and margins."
The real swing factor for OceanaGold now is how one key assumption around future operating economics ultimately filters through to those margins and cash returns.
That swing factor is exactly what the full narrative for OceanaGold unpacks, separating one off operating noise from the bigger cash flow story and the risks around it.
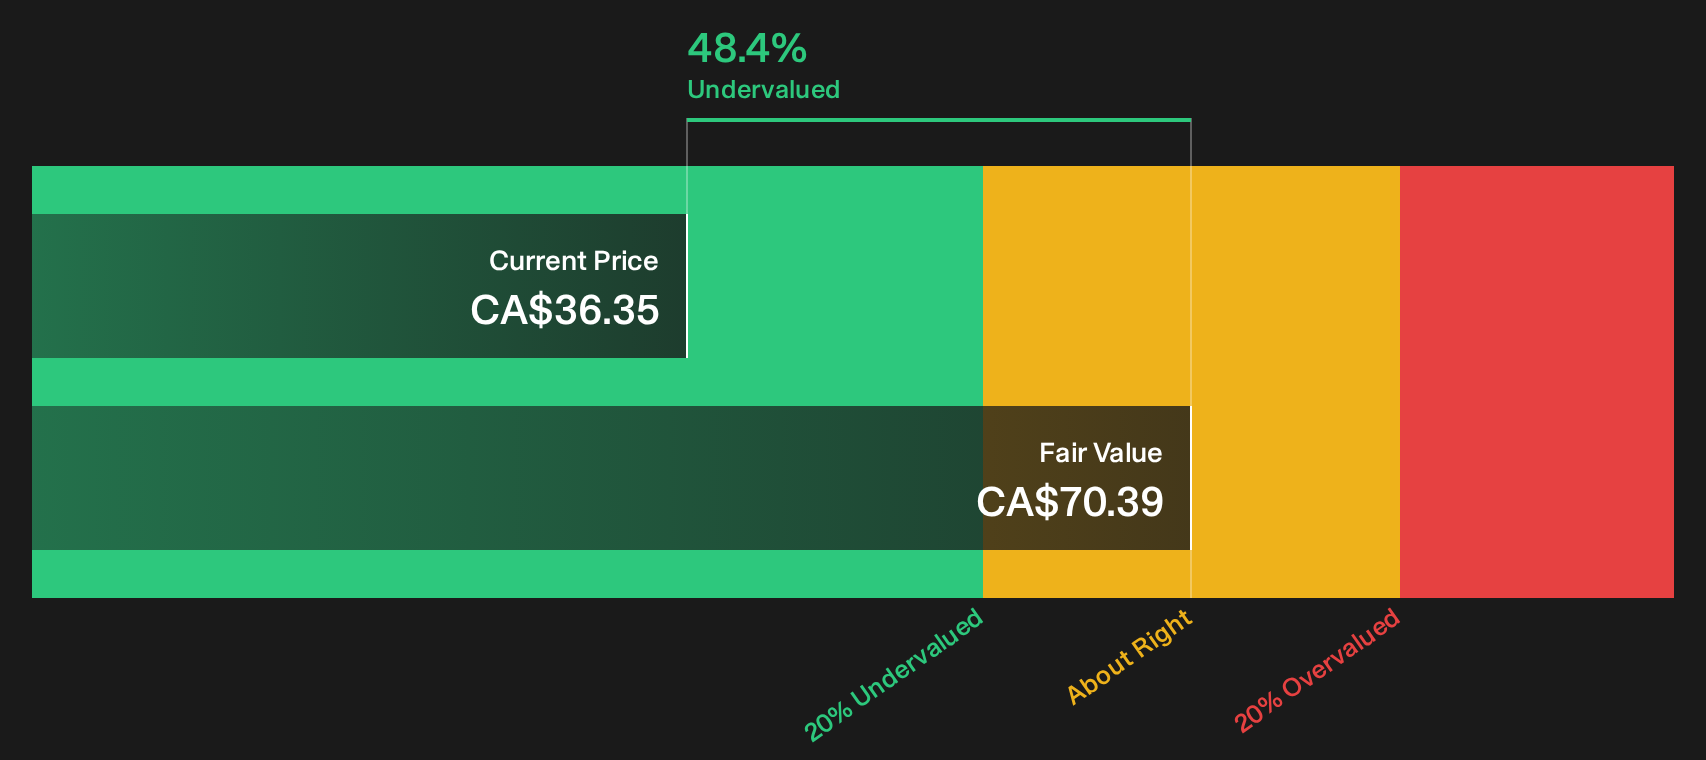
Canadian Natural Resources (TSX:CNQ)
Canadian Natural Resources turns a broad mix of crude oil, natural gas, and NGL production into the kind of recurring cash flows that anchor this undervalued cash flow screener. Most revenue comes from North American exploration and production at about CA$21.3b and oil sands mining and upgrading at roughly CA$20.8b, with midstream and refining contributing around CA$1.0b and a market value near CA$156.6b.
For investors focused on cash flow value, Canadian Natural Resources offers a different angle. It is built around long life assets that can support production even when commodity cycles are choppy.
"The large inventory of long-life, low- or zero-decline oil sands reserves, including mining and synthetic crude oil assets with multi decade reserve life indices, provides scope for Canadian Natural Resources to sustain production levels and associated revenue over an extended period if current operating performance is maintained."
What really matters next is how one unresolved pressure on future earnings shapes the durability of those cash flows investors are counting on.
If that pressure point matters to you, read the full narrative for Canadian Natural Resources to see how Canadian Natural Resources' long life reserves and cash flows could evolve from here.

Nutrien (TSX:NTR)
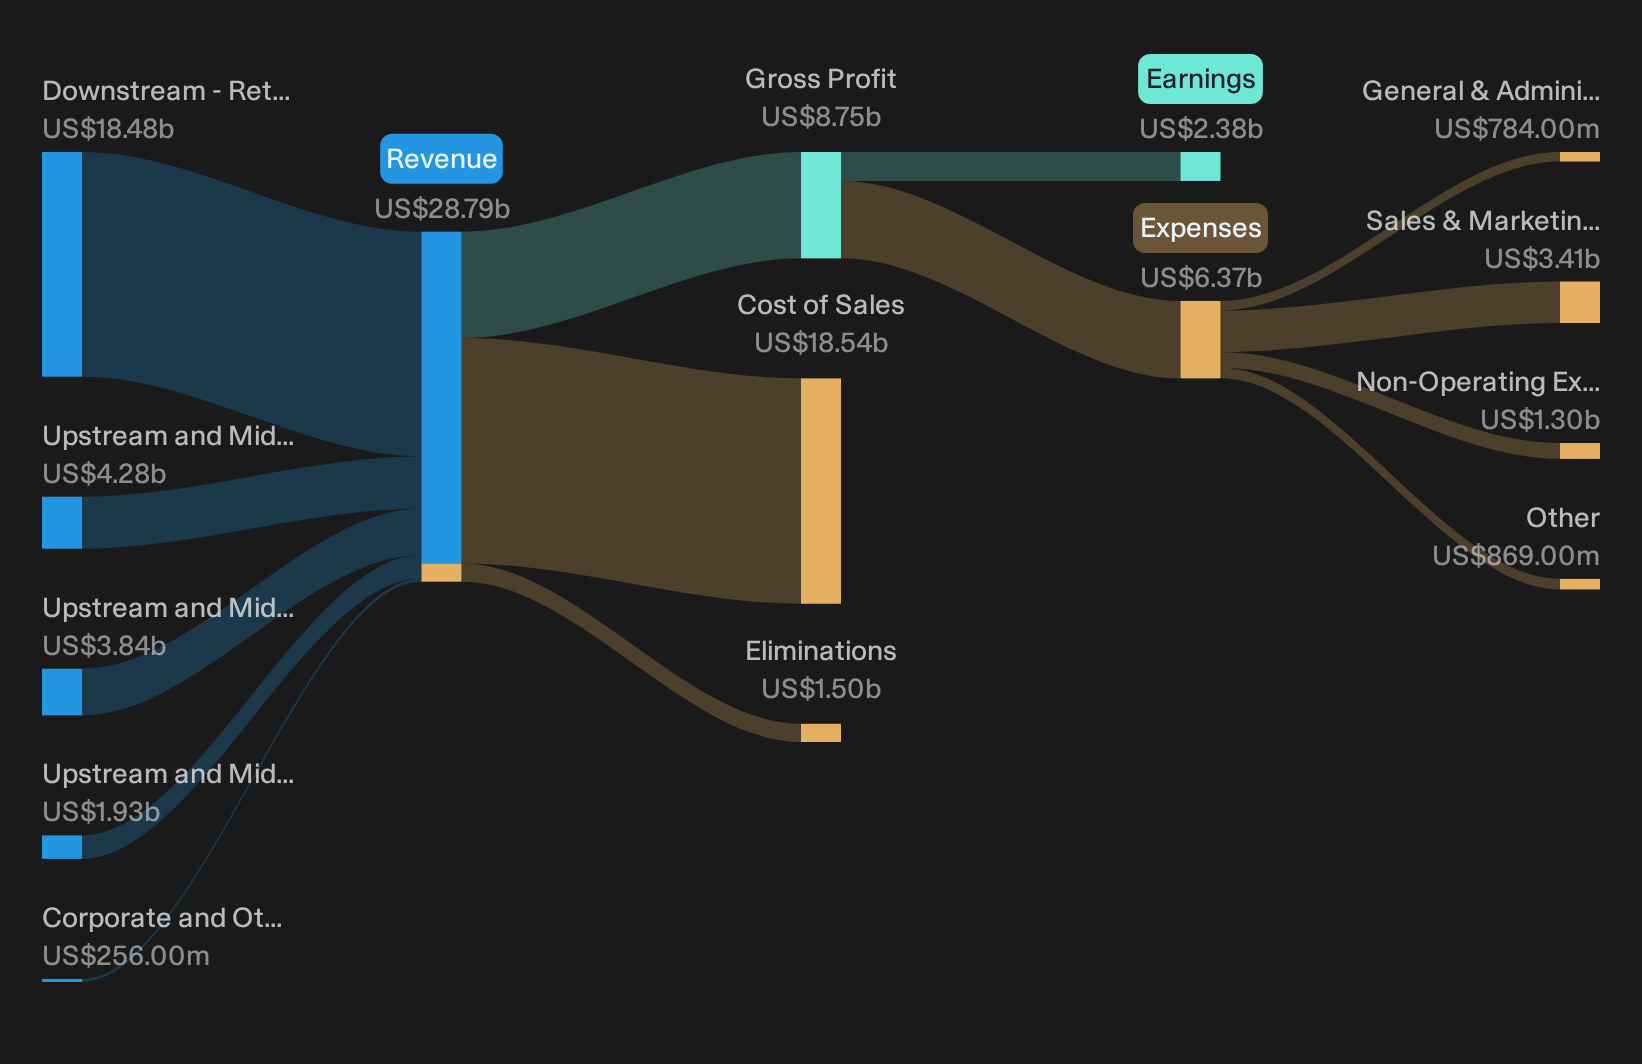
Nutrien is a global fertilizer and farm services group, with its Retail arm turning recurring crop input and financing sales into the kind of cash flows value investors look for. That Retail unit generated about $18.5b, alongside Potash at $3.8b, Nitrogen at $4.3b, and Phosphate at $1.9b, and the stock is valued around $46.5b.
Nutrien fits this cash flow focused screen as a producer and distributor that gets paid year after year when farmers buy nutrients, protection products, and services, then uses those recurring inflows to support its fertilizer production footprint.
"The push for higher yields and resource efficiency in agriculture now links directly to Nutrien’s potash mine automation, with 53% of ore tonnes mined using automation in the first half of 2026. This supports lower controllable cash costs per tonne and can lift net margins and potash adjusted EBITDA as throughput grows."
An important factor for Nutrien is how a less visible shift in its cost base and volume mix ultimately feeds through to cash returns.
To see how that quieter cost and volume shift could accelerate or stall cash generation, read the full narrative for Nutrien and see what the market might be missing.
Seeking Fresh Alternatives Before Momentum Flips
Some of the next breakout stories are already building momentum while they are still under the radar for now. Before the crowd catches on and pricing flies, consider your options early.
- Scan for companies quietly building staying power by running the list of solid balance sheet and fundamentals (6 results) to identify balance sheets that can handle shocks while prices still reflect uncertainty.
- Explore income opportunities by checking the 3 dividend fortresses to see which high yield payers pair strong cash generation with disciplined payout policies.
- Review the 20 cryptocurrency and blockchain stocks to find businesses tying real cash flows to blockchain adoption while prices remain compressed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com