


Bloom Energy (BE) just delivered a powerful one two punch for investors, reporting profitable third quarter results and lifting its 2026 revenue outlook after stronger demand from data center customers.
The recent guidance hike has landed in a volatile stretch for Bloom Energy, with the 1-day share price return of 4.38% coming after a 30-day share price decline of 13.23% and a 7-day drop of 4.38% as investors reassess AI power suppliers. Yet the year-to-date share price return of 131.11% and a 1-year total shareholder return of 70.58%, alongside a very large 3-year total shareholder return above 20x, indicate that long term momentum has remained strong even as sentiment shifts around cash flow and AI exposure.
Spot emerging power players riding the same AI energy wave as Bloom Energy by scanning our curated list of 54 AI infrastructure stocks.Bloom Energy now trades at a clear discount to both its intrinsic value estimate and analyst targets after the guidance bump and volatile pullback. Is that a genuine margin of safety, or is the market pricing cash flow risk correctly?
Most Popular Narrative: 41% Undervalued
Against Bloom Energy's last close of $228.08, the most followed valuation story on Simply Wall St points to a fair value of $386.10. This frames the recent pullback as a wide gap between narrative and market pricing.
The Bloom Energy story is still early days. Wall Street cannot seem to comprehend that so many areas for their growth, international, other market segments, even personal or community power (where they started) are largely untapped.
The main constraint on their opportunity is plain and simple ignorance.
See why 47 investors see Bloom Energy as 41% undervalued.
Result: Fair Value of $386.10 (UNDERVALUED)
Still, Bloom Energy faces real pressure points, including potential shifts in data center spending and any slowdown in adoption from newer international and non-data-center customers.
Find out about the key risks to this Bloom Energy narrative.
Another View: Bloom Energy Through Earnings Multiples
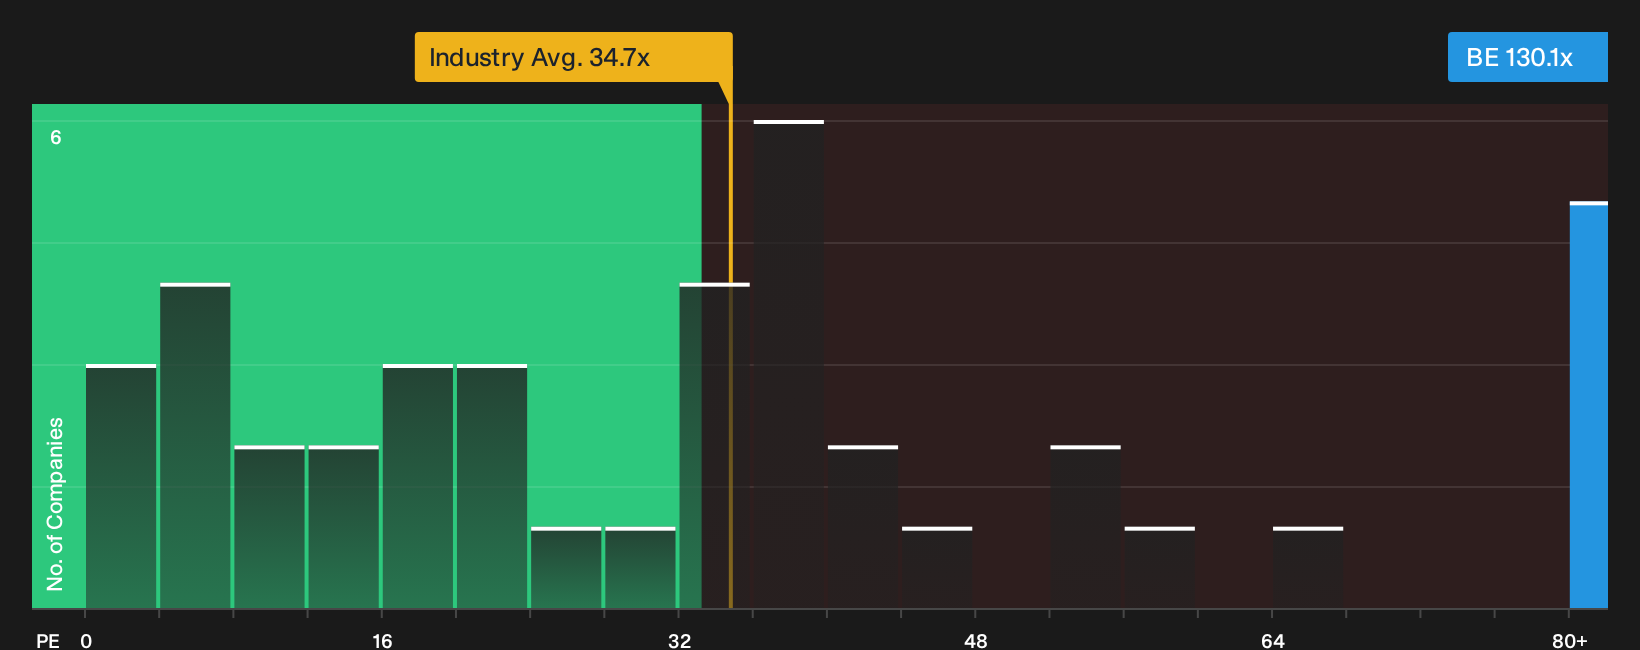
Bloom Energy might look cheap against a $386.10 fair value story, yet its current P/E of 130.1x tells a different tale. That level is far above the US Electrical industry at 34.7x, the peer group at 55.7x, and even the 89.3x fair ratio that our model suggests the market could move toward. If sentiment cools, how much room is there for this valuation to compress before it reconnects with those benchmarks?
For investors weighing that gap between narrative and P/E reality, See what the numbers say about this price — find out in our valuation breakdown. can help frame how much multiple risk they are comfortable holding at today's price.
Next Steps
Sentiment around Bloom Energy is clearly split, with both excitement and caution running high, so move quickly and review the data points yourself to decide where you stand. To weigh both sides of the argument in one place, start by checking the 3 key rewards and 3 important warning signs.
Looking for more Bloom Energy style ideas?
If Bloom Energy has caught your attention, do not stop here. Use targeted stock lists on Simply Wall St to spot other opportunities before they move without you.
- Target reliable compounding by checking companies that combine strong fundamentals with robust cash positions through the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispriced opportunities by reviewing our focused set of 19 high quality undiscovered gems.
- Prioritise resilience in choppy markets and filter for steadier candidates with the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com